


What is a Term Insurance Plan?
Term Plan Life Insurance is a plan in which a person takes a life cover and pays a Premium for the period of cover.
The premium is usually paid annually, however other options as half-yearly and quarterly premium are also available.
In case the person dies during the plan period, the beneficiary named in the policy will get the assured sum, and in case the person lives up to the period of maturity, he gets nothing.
Actual Returns on a Term Insurance Plan
Alternative Offer: Return of Premium in Term Insurance Plan
As there is no return, Term life insurance plans are not popular. Insurance companies, have therefore, come up with another Term insurance Plan Product known as ‘Return of Premium in Term Plan’ where they are returning the entire premium paid during the period of the plan at the end of the term period. However, the premium is much higher compared to a pure term insurance plan.
But Return of Premium in Term Insurance Plan are NOT Profitable
Despite their offer of returning the premium at the end of the plan period in Return of Premium Term Plans, it is NOT at all advisable to buy this product.
Let us take an example to understand why it is so. If a person aged 30 years takes a Return On Premium for 25 years, he will pay Rs9, 000 as premium per year and at then at the end of the plan the insurance company will return the total premium paid of Rs 226, 000.
If it is a pure term insurance plan the premium will be Rs2, 800 per annum and at the end of the period he will get nothing.
| Age (Yrs) | Term (Yrs) | Sum assured (Rs) | Premium (Rs) | Maturity value (Rs) | |
|---|---|---|---|---|---|
| Maturity value (Rs) | 30 | 25 | 10,00,000 | 9000 | 226,000 |
| Pure Term Plan | 30 | 25 | 10,00,000 | 2800 | Nil |
| Premium difference | 6200 |
A quick note on the premium numbers above: they’re illustrative, meant to show you the pattern rather than a quote you can walk into an insurer with.
Your own premium will depend on your age, health, sum assured, and the insurer you choose — but the pattern itself holds up well across the market.
Return of premium plans typically cost anywhere from 60% to 100% more than an equivalent pure term plan, sometimes even more.
Investing Else Where Will Give you Higher Return
Though, the sum of Rs226, 000 looks attractive, let us examine closely.
Let us say the person only takes a pure term plan and not a Return On Premium, in that case he saves Rs 6, 200 per annum and if he invests that money elsewhere he gets a much better return. See the table below.
| Amount invested per annum (Rs) |
Tenure (Yrs) | Assumed rate of return (%) (Yrs) |
Maturity value (Rs) (Yrs) |
|---|---|---|---|
| 6,200 | 25 | 7 | 4,19,600 |
| 6,200 | 25 | 8 | 4,89,500 |
| 6,200 | 25 | 10 | 6,70,700 |
Double Benefits:
The person who opts for the above benefits both ways.
In case he dies, the beneficiary will get the insured sum of Rs.10,00,000 and the proportionate returns from the investment in which Rs.6200 was invested regularly.
If he survives the term, he will get the above return based on his investment at 7% (Rs 4,19,600), 8% (Rs 4,89,500), or 10% (Rs 6,70,700).Check out the “Pure Term Vs Return of Premium Term insurance calculator”.
Here are the workings of the ““Pure Term Vs Return of Premium Term insurance calculator”.” with another similar example.Mr.X aged 40 years take an insurance cover for 31 years.
The sum assured is Rs.1 crore. The premium for return of premium insurance is Rs.55,954 per year and the premium for pure term insurance is Rs.33,957 per year.
Enter these details in the space provided in the ““Pure Term Vs Return of Premium Term insurance calculator”. Enter them in the light yellow highlighted boxes, the rest is calculated automatically.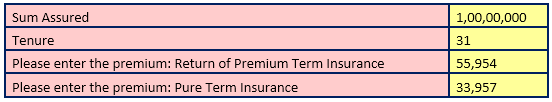 Now you will automatically get the difference between the premiums as an investment amount in the “Pure Term Vs Return of Premium Term insurance calculator”,. (Just as you saw in the above example) You have to enter the rate of interest you expect from the investment.
 Once you enter all the above details in the “Pure Term Vs Return of Premium Term insurance calculator”., you would get the return of premium term insurance workings on the left-hand side and the pure term insurance workings along with the additional investment on the right-hand side.
You would also know what is the survival and death benefits for both pure term and return of premium insurance policy with additional investment.
The survival benefits and death benefits are highlighted in light orange and light green respectively for easy identification.
If Mr. X invests Rs.55,954 per year in return of premium insurance, at the end of the plan he would get the total premium paid Rs. 17,34,574 if he survives the policy term and Rs.1 crore in case of death.
If he invests Rs.33,957 per year in pure term insurance, at the end of the period he will get nothing if he survives the policy term and Rs.1 crore in case of death.
Like in the above example, if he only takes a pure term plan and not a Return On Premium, he saves Rs.21,997 per annum and if he invests that money elsewhere he gets a much better return.
What we suggest, is to go ahead and invest Rs.33,957 in a pure term insurance policy and the difference premium of Rs.21,997 (return of premium – pure term insurance, i.e.Rs.55,954- Rs.33,957) to be invested in any investment, of your choice.
What happens if he invests this way?
If he invests in Equity MF or Hybrid MF or PPF. This is what happens. If he survives the term, he will get the above return based on his investment at 7% (Rs. 24,02,472) or 10% (Rs 39,62,187) or 12% (Rs 60,15,364). (After deduction of Long term capital gain).
Make sure to reduce long term capital gain and you will know what is the additional gain you get via investments.
A quick word on that tax deduction: the working above uses a 10% long-term capital gains rate, which was the rule before Budget 2024.
Equity and equity-oriented hybrid mutual funds are now taxed at 12.5% on long-term capital gains above ₹1.25 lakh in a financial year, so a fresh calculation today would show a slightly smaller net gain on the Equity MF and Hybrid MF columns than what’s pictured here.
The pattern and conclusion don’t change — pure term plus investing the difference still comes out well ahead — only the exact rupee figure would shift a little.
One more thing worth saying plainly: these return figures assume the money is invested in market-linked instruments like equity or hybrid mutual funds.
Mutual fund investments are subject to market risk, and the actual returns you get could be higher or lower than what is shown here — think of these as illustrations to help you compare the two approaches, not a promise of what you will earn.
Which is more profitable?
In case he opts for the pure term policy and selects an investment. This is what he gets.
A. In case of death, the beneficiary will get the sum assured of Rs.1 crore and the proportionate returns from the investment in which Rs.21,997 was invested regularly.
If he survives the term, he will get the above return based on his investment at 7% (Rs.24,02,472) or 10% (Rs 39,62,187) or 12% (Rs.60,15,364).
(or)
In case he opts for a return of the premium policy. This is what he gets.
B. In case of death, his beneficiary gets Rs.1 crore.
In case he survives the policy period, he gets Rs.17,34,574.In both cases, opting for option A is the best, i.e investing a sum in pure term insurance policy and making an investment, rather than opting for a return of the premium policy. Your benefits will be much more.
Frequently Asked Questions
i. What exactly is a Return of Premium (ROP) term plan?
It’s a term insurance plan that pays back all the premiums you’ve paid if you outlive the policy term, on top of the usual death benefit if you don’t. A regular, or “pure,” term plan pays out only on death and gives you nothing back if you survive the term.
ii. What are the biggest mistakes people make with Return of Premium plans?
The most common one is comparing the headline “you get your money back” benefit without comparing it against what that extra premium could have earned elsewhere. As the example above shows, the gap is usually large enough that a pure term plan plus a separate investment comes out ahead — often by a wide margin, and with more flexibility besides.
iii. Do all life insurers in India offer a Return of Premium option?
Most major life insurers offer some version of it, either as a standalone plan or as an add-on to their regular term plan. Since the exact plans and pricing change often, it’s best to check current options directly with an insurer or a licensed advisor rather than relying on any fixed list.
iv. Is Return of Premium term insurance ever worth it?
For most people, no — the maths in this article shows why. It can occasionally make sense for someone who values the psychological comfort of a guaranteed payback and knows they won’t invest the difference disciplined on their own, but that’s a narrow case, not the norm.
So What is the Conclusion
What conclusions one may derive out of this article is that taking a ‘Return of Premium Term Plan’ is NOT at all advisable and to be strictly avoided. Invest in Pure Term Insurance Plans.
Taking pure term insurance policies online is much cheaper than taking the term insurance plans offline or through agents.
To take the right critical illness insurance, health insurance, life insurance and other investments, preparing a fundamentally strong, fool proof financial plan is required.
A pure term plan and a separate investment can look like two decisions, but they really work best as one plan — the kind a Certified Financial Planner at Holistic Investment can help you put together, based on your actual goals rather than a generic example like the one above.


Leave a Reply