 Listen to this article
You have an insurance advisor for your policies.
A relationship manager at the bank for your mutual funds.
Maybe a stockbroker for direct equity, and a separate PMS manager for the portfolio you built after your last big liquidity event.
Each of them is probably competent at their own job.
But ask yourself one question: could any single one of them tell you, right now, your true net worth across every asset you own — without making three phone calls first?
For most HNI families, the honest answer is no.
And that gap — not any one advisor’s mistake — is where the real cost of fragmented wealth management quietly builds up.
This guide walks through why that happens, what it actually costs you, and a practical, non-disruptive way to fix it.
Table of Contents:
The Hidden Cost of Fragmented Wealth Management
Why HNIs End Up With Multiple Wealth Managers in the First Place
Fragmented vs Consolidated: What Actually Changes
The Question That Matters More Than Returns: What Happens the Day You’re Not There to Explain It?
What Consolidation Actually Means (It’s Not What You Think)
Audit Your Current Setup: A Practical Checklist
How to Consolidate Without Disrupting What’s Already Working
Common Mistakes HNIs Make While Consolidating
Choosing Your Single Point of Contact: What to Look For
The Hidden Cost of Fragmented Wealth Management
Here’s a scenario worth sitting with for a moment.
A promoter sells part of his business.
Over the next few years, he ends up with a term policy and two ULIPs from one agent, five mutual fund folios opened at different banks, a direct equity account with a broker he met at a conference, and a PMS mandate a friend recommended.
Nobody sat down and planned this. It just accumulated — one good-enough decision at a time.
Five years later, he has no real idea whether his equity exposure across all these accounts is 40% or 70% of his net worth, because no single person is looking at all of it together.
India’s own wealth numbers make this a bigger story than one promoter’s portfolio.
India now has roughly 19,877 ultra-high-net-worth individuals — people with $30 million or more in net worth — making it the world’s 6th-largest UHNWI market, and that number is expected to cross 25,000 by 2031.
That’s a lot of people accumulating wealth faster than they’re organising it — and fragmentation is the natural, almost invisible by-product of fast wealth creation.
Why HNIs End Up with Multiple Wealth Managers in the First Place
Nobody wakes up and decides to hire five different people to manage their money.
It happens gradually, for reasons that each made sense at the time.
An insurance policy bought years ago, from someone you trusted then.
A mutual fund folio opened because a bank RM called at the right moment.
A PMS mandate started after a large pay-out, recommended by a friend who’d had a good year.
Each decision, in isolation, was reasonable. The problem is that nobody was ever hired to look at the sum of all of them.
Myth: “More advisors means more diversification of advice, so it’s actually safer.”
Reality: More advisors usually means more duplication — three different “conservative” fund recommendations that turn out to be nearly identical large-cap funds — and less accountability, because no one person owns the whole outcome.
Fragmented vs Consolidated: What Actually Changes
It helps to see this side by side rather than in the abstract.
| What You Need | Fragmented (Multiple Providers) | Consolidated (One Coordinating Relationship) |
| Your true net worth today | You’d need to call 3–4 people and manually add up statements | Available as one aggregated view, on request, from one person |
| Spotting overlap | Three “different” funds may hold largely the same top stocks — nobody’s checking | Overlap across equity, MF and PMS is reviewed as one exposure |
| Insurance vs investment clarity | ULIPs sold as “investments” sit alongside actual investments, uncompared | Insurance is assessed for protection value, separately from your investment plan |
| Advice when markets fall | Each advisor defends their own product; no one owns the full picture | One planner is accountable for the whole portfolio’s behaviour |
| If something happens to you | Your spouse must locate and contact several unfamiliar people, each holding a fragment | One relationship your family already knows can walk them through everything |
A portfolio only your advisor can explain isn’t diversified — it’s just complicated.
The Question That Matters More Than Returns: What Happens the Day You’re Not There to Explain It?
Most conversations about wealth management focus on returns. Which fund performed better. Which advisor timed the market well.
But for an HNI family, there’s a more important question that almost never gets asked out loud: if something happened to you tomorrow, could your spouse actually step in?
Not eventually. Not after months of searching through emails and old statements. Tomorrow.
If your insurance is with one person, your mutual funds are spread across three different bank relationship managers who change every eighteen months, your PMS is with a fourth, and your Demat account login is saved only on your phone — the honest answer for most families is no.
This isn’t a hypothetical risk. India is heading into a period of enormous wealth transfer between generations, and family offices themselves are being restructured for exactly this reason.
India is expected to see US$1.3–1.5 trillion in intergenerational wealth transfer over the next decade, and the number of formal family offices has grown from roughly 45 in 2018 to over 300 todays — largely to bring exactly this kind of coordination in-house.
You don’t need a formal family office to get the same protection.
You need one relationship your spouse already knows, trusts, and has met more than once — someone who can explain the whole picture without you in the room.
The best inheritance isn’t the money. It’s not having to figure out where all of it is.
What Consolidation Actually Means (It’s Not What You Think)
Let’s clear up a common misunderstanding first.
Myth: Consolidating means moving every rupee to one company — one insurer, one AMC, one PMS provider.
Reality: Consolidation is about coordination, not concentration.
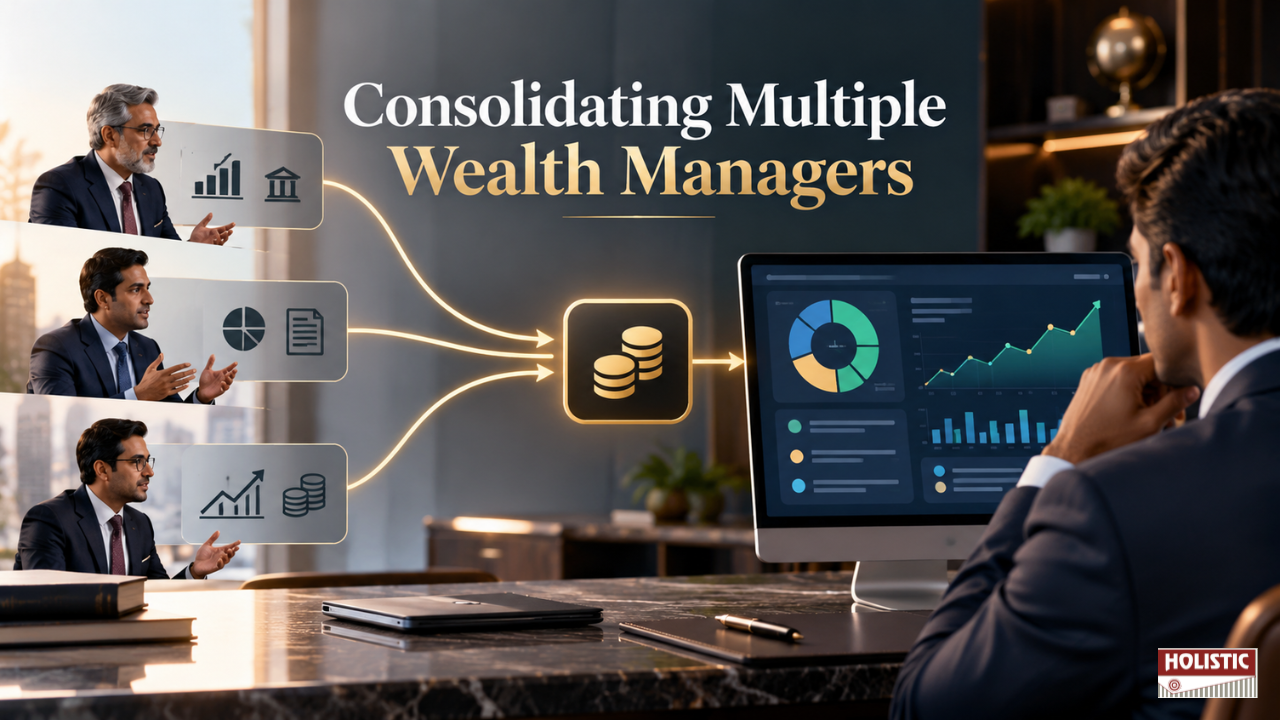
It means one professional relationship holds the complete map — even if your actual money stays spread across multiple, well-chosen products for genuine diversification.
Think of it as the difference between having five separate maps of the same city, each drawn by a different person who’s only seen their own neighbourhood — versus one map that shows the whole city, even though the roads themselves haven’t changed.
The insurance can still sit with a strong insurer.
The mutual funds can still be genuinely diversified across fund houses.
What changes is that one Certified Financial Planner sees all of it, understands how the pieces fit (or don’t), and can speak for the whole portfolio — to you, and if needed, to your family.
Audit Your Current Setup: A Practical Checklist
Before consolidating anything, get an honest picture of what you actually have.
Most people are surprised by what this checklist turns up.
- List every provider you currently work with — insurance, mutual funds, PMS, direct equity, PPF/EPF, real estate, and any informal investments.
- For each one, note who your actual point of contact is — by name, not just “the bank.” RMs change roles far more often than people expect.
- Check whether your spouse or nominee has ever met or spoken to each of these people, even once.
- Pull your last statement from each provider and check the overlap in underlying holdings — you may be paying three different people to hold the same large-cap stocks.
- Separate every policy that’s sold as “investment cum insurance” and evaluate its actual protection cover on its own, honestly.
- Write down, in one page, where the login credentials, physical documents, and nominee details for each account actually live.
If that last point made you slightly uneasy, that’s exactly the gap this whole exercise is meant to close.
How to Consolidate Without Disrupting What’s Already Working
Consolidation doesn’t mean tearing everything down and starting over. A sensible transition happens in three stages.
1. Audit. Complete the checklist above with one advisor acting purely as an auditor first — not as someone trying to sell you a replacement product.
2. Select. Decide, product by product, what stays as-is, what gets replaced because it’s genuinely redundant or underperforming, and what simply needs to be re-registered under one coordinating relationship.
3. Transition. Move records, nominations, and points of contact over gradually — there’s rarely a good reason to redeem a well-performing fund or surrender a useful policy just to make the paperwork tidier.
The goal at every stage is the same: reduce the number of people your family would need to track down, without reducing the quality of what you’re actually invested in.
Common Mistakes HNIs Make While Consolidating
- Consolidating in a hurry after a health scare or bad market year, rather than as a planned exercise — rushed decisions during stressful periods rarely hold up well.
- Surrendering long-held insurance policies purely to “tidy up,” without checking the actual protection or surrender-cost impact first.
- Choosing consolidation with a single product-selling company rather than a planning-first relationship — which just swaps one kind of fragmentation for a new kind of concentration risk.
- Never actually introducing the spouse or family member to the new single point of contact — defeating the entire purpose of doing this in the first place.
Choosing Your Single Point of Contact: What to Look For
Not every wealth manager is built to be this single coordinating relationship. A few things are worth checking before you commit.
- They should be comfortable discussing insurance, mutual funds, PMS, and direct equity together — not just the one product they happen to sell.
- They should be able to show you an aggregated, one-page view of your net worth — not just their own product’s performance.
- They should be willing to have at least one meeting with your spouse or family, not only with you.
- Their registration status should be transparent and checkable — whether they operate as an AMFI-registered distributor, a SEBI-registered investment adviser, or both, you should know exactly which hat they’re wearing for which recommendation.
- They should be comfortable saying “this one doesn’t need to change” as often as they suggest something new.
Final Word
None of this is about finding the single best-performing fund or the cleverest tax structure. It’s about making sure the whole picture — your whole picture — lives somewhere your family can actually reach.
Wealth is built by consistency far more often than by brilliance.
But it’s protected by clarity — and clarity is exactly what fragmented wealth management quietly takes away.
If you’ve read this far and found yourself mentally listing your own scattered accounts, that’s usually the sign that it’s time for an honest, no-pressure conversation — not a sales pitch, just a second pair of eyes on what you already have.
If that’s useful, you can book an Initial Guidance Call (No Cost) with a Certified Financial Planner — no obligation, just a conversation about where things stand today.
Holistic Investment is an AMFI-registered Mutual Fund Distributor and APMI-registered PMS Distributor — not a SEBI-registered Investment Adviser. Nothing in this article is investment advice or a recommendation to buy, sell, surrender, or switch any specific product; it is shared purely for financial education.
Frequently Asked Questions
Q1. How can I reduce the complexity of managing multiple wealth managers for different asset classes?
Start with an audit, not a switch. List every provider and product you currently hold, identify genuine overlaps, and bring everything under one coordinating relationship who can see and explain the full picture — while leaving well-performing individual products untouched.
Q2. Is it risky to consolidate all my wealth with one advisor?
Consolidating your relationship isn’t the same as concentrating your money. Your investments can, and usually should, remain diversified across products and institutions — what changes is that one person is accountable for seeing and coordinating all of it.
Q3. What’s the difference between a multi-family office and simply consolidating with one wealth manager?
A multi-family office is a formal, dedicated institutional structure, typically justified only at very large net worth. For most HNIs, a single coordinating Certified Financial Planner relationship achieves the same core benefit — one point of contact and one aggregated view — without that overhead.
Q4. Will my spouse be able to manage our investments if something happens to me?
Only if they already know who to call and that person already has the complete picture. This is usually the single biggest gap in fragmented wealth management, and the main reason consolidation matters more than chasing marginally better returns.
Q5. Do I need to close my existing insurance policies and mutual funds to consolidate?
No. Consolidation is about coordination, not liquidation. Well-performing products can stay exactly where they are — what should change is who has visibility into all of them together.
Q6. How much wealth do I need before consolidation makes sense?
There’s no fixed threshold. The moment you can no longer answer “what is my total net worth right now” without calling more than one person, it’s already worth doing.
Q7. What documents should I keep ready for my family in case of an emergency?
A single, updated one-page summary listing every provider, the point of contact for each, nominee details, and where physical documents and login credentials are stored — shared with your spouse or a trusted family member, not just saved on your own phone.
Leave a Comment