 Listen to this article
Can the INL Milestone Plan help you achieve your life goals?
Is the INL Milestone Plan suitable for achieving your financial goals?
Can the INL Milestone Plan help you stay on track with your financial goals?
Can the INL Milestone Plan protect your financial goals from unexpected events?
This article examines the plan’s key features, advantages, and drawbacks, while also exploring the suitability of endowment plans for long-term financial goals.
Table of Contents
What is the INL Milestone Plan?
What are the features of the INL Milestone Plan?
Who is eligible for the INL Milestone Plan?
What are the benefits of the INL Milestone Plan?
Grace Period, Discontinuance and Revival of the INL Milestone Plan
Free Look Period for the INL Milestone Plan
Surrendering the INL Milestone Plan
What are the advantages of the INL Milestone Plan?
What are the disadvantages of the INL Milestone Plan?
Research Methodology of the INL Milestone Plan
Benefit Illustration – IRR Analysis of INL Milestone Plan
INL Milestone Plan Vs. Other Investments
INL Milestone Plan Vs. Other Investments
Final Verdict on INL Milestone Plan
1. What is the INL Milestone Plan?
INL Milestone Plan is a non-linked, Participating, Individual, Savings Life Insurance Plan.
The plan offers a lump sum benefit at maturity and a lump sum life insurance cover, which protects your family against any unforeseen eventualities.
2. What are the features of the INL Milestone Plan?
- Life Protection: Provides life insurance cover throughout the policy term to protect your family.
- Savings: Offers a lump-sum maturity benefit to help you meet your financial goals.
- Waiver of Premium Benefit: Helps keep the policy benefits intact for your loved ones even in your absence.
- Settlement Option: Allows you to receive the maturity proceeds as regular income over a period of 5, 10, or 15 years.
- Bonus: Provides the benefit of accrued bonuses, if any, from the first policy year to enhance your savings.
- Flexible Premium Payment: Choose a premium payment term of 5, 6, 7, 8, 10, 12, or 15 years to suit your financial plans.
- Additional Protection Through Riders: Enhance your insurance coverage against specific contingencies by paying an additional premium for optional riders.
- Tax Benefits: You may be eligible for tax benefits, subject to the applicable income tax laws and conditions.
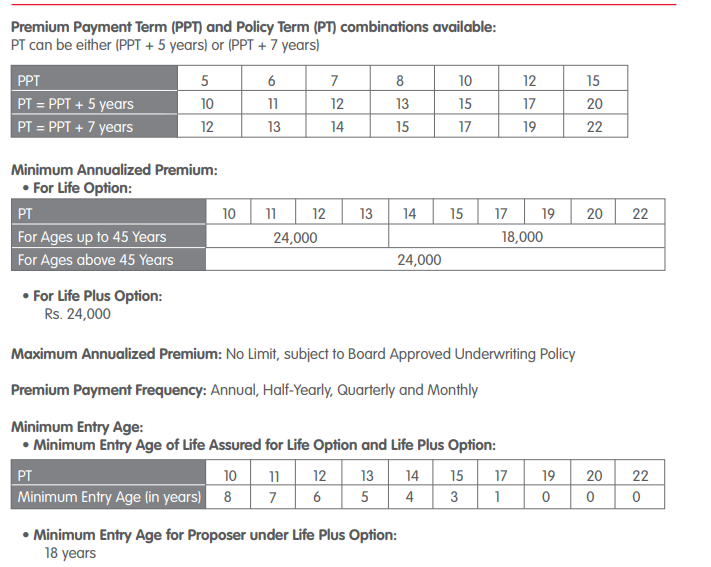
3. Who is eligible for the INL Milestone Plan?
4. What are the benefits of the INL Milestone Plan?
i. Maturity Benefit
On survival of the Life Assured till the end of the INL Milestone Policy Term, provided the policy is in-force and all due premiums have been paid, the aggregate of the following benefits will be payable:
- Sum Assured on Maturity
- Accrued Compounded Reversionary Bonus (if any)
- Terminal Bonus (if any)
Sum Assured on Maturity is equal to the Base Sum Assured for this Policy.
Settlement Option
On maturity of an in-force or Paid-up Policy, you may choose the Settlement Option to convert a part or whole of the Maturity Benefit into a level stream of payments.
You may choose a Settlement Benefit Period of 5, 10 or 15 years.
Bonus
Compounded Reversionary Bonus, if any, will be declared annually and shall apply as a percentage of Base Sum Assured and accrued Reversionary Bonus, if any.
Once declared, they form part of the guaranteed benefits under this policy.
Compounded Reversionary Bonus, once declared, shall accrue to the INL Milestone Policy provided the Policy is not in lapse or paid-up status.
For policies with Policy Term of 10, 11, 12, 13, 14, and 15 years, Terminal Bonus (if any) shall be payable on maturity, death and surrender after completion of Premium Paying Term.
For policies with Policy Term of 17, 19, 20 and 22 years, Terminal Bonus (if any) shall be payable on maturity, death and surrender post end of 10th Policy Year i.e. from 11th Policy Year onwards.
ii. Death Benefit
On Death of the Life Assured under Life Option and Life Plus Option
On death of the Life Assured during the Policy Term, provided the Policy is in force as on the date of death, i.e. all due Premiums have been paid, the Claimant will receive the higher of:
- Sum Assured on Death plus accrued Compounded Reversionary Bonus plus Terminal Bonus (if any) or
- 105% of Total Premiums Paid up to the date of death of the Life Assured
Where, Sum Assured on Death is the higher of:
- Base Sum Assured; or
- Sum Assured on Maturity; or
- Multiple of Annualised Premium as per the table
| Entry Age of Life Assured/Premium Payment Term | Less than 50 years | 50 years to 55 years | Greater than 55 years |
| 5/6/7/8 | 11 Times | 5 Times | 5 Times |
| 10/12/15/ | 11 Times | 11 Times | 5 Times |
On Death of the Proposer under Life Plus Option
On death of the Proposer during the Premium Payment Term, all future Premiums shall be waived off under the Base Policy, provided the INL Milestone Policy is in force, i.e. all due Premiums have been paid as on the date of death.
The Policy shall continue with all the Benefits as applicable on the Life Assured.
5. Grace Period, Discontinuance and Revival of the INL Milestone Plan
i. Grace Period
If you are unable to pay your premium by the due date, you will be given a grace period of 30 days (15 days for monthly frequency).
ii. Premium Discontinuance
The policy shall acquire a surrender value after completion of the first policy year provided one full year premium has been paid.
If you discontinue the payment of premiums before your policy has acquired a surrender value, your policy will lapse at the end of the grace period and the Death Benefit and rider benefits, if any, will cease immediately.
No bonus will accrue, and no benefits will be paid when the policy is in lapsed status.
If the policy has acquired a surrender value and no future premiums are paid, you may choose to continue your policy on a reduced paid-up basis.
iii. Revival
You can revive your lapsed/paid-up policy and the riders for its full coverage within five years from the due date of the first unpaid premium but before policy maturity.
6. Free Look Period for the INL Milestone Plan
You are provided with a free look period of 30 days beginning from the date of receipt of the Policy Document, whether received electronically or otherwise, to review the terms and conditions stipulated in the Policy Document.
In the event you disagree with any of the Policy terms or conditions, or otherwise and have not made any claim, you shall have the option to return the INL Milestone Policy to the Company for cancellation, stating the reasons for the same.
7. Surrendering the INL Milestone Plan
The policy shall acquire a surrender value after completion of the first policy year provided one full year’s premium has been paid.
If your policy has acquired a Surrender Value and you choose to discontinue your policy, you will be entitled to the surrender value, which is the higher of Guaranteed Surrender Value (GSV) or Special Surrender Value (SSV).
In case of Life Plus Option, on death of the Proposer, the Policy can be surrendered only when the Life Assured becomes a major.
8. What are the advantages of the INL Milestone Plan?
- Loan Facility: You can avail of a loan against the policy for up to 70% of the applicable surrender value.
- Optional Riders: Enhance the base policy coverage by adding riders at an additional cost.
- Waiver of Premium on Death: Under the Life Plus Option, the waiver of premium benefit is triggered upon the death of the life insured, subject to the policy terms and conditions.
9. What are the disadvantages of the INL Milestone Plan?
- Uncertain Returns: The policy includes non-guaranteed bonuses, making the overall returns uncertain.
- Inadequate Life Cover: The sum assured may be insufficient to meet your family’s future financial needs.
10. Research Methodology of the INL Milestone Plan
Under the INL Milestone Plan, the maturity benefit is paid at the end of the policy term after the limited premium payment period is completed.
The final payout depends on the bonuses declared by the insurer.
To assess the plan’s potential returns, we can use the figures illustrated in the policy brochure and calculate the Internal Rate of Return (IRR), which measures the annualised return based on the timing and amount of cash flows.
Benefit Illustration – IRR Analysis of INL Milestone Plan
Consider a 40-year-old male who purchases the INL Milestone Plan with a sum assured of ₹11 lakh, a policy term of 15 years, and a premium payment term of 10 years.
The annual premium is ₹1 lakh.
| Male | 40 years |
| Sum Assured | ₹ 11,00,000 |
| Policy Term | 15 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 1,00,000 |
The sum assured on maturity is ₹8.35 lakh, to which the applicable bonuses are added.
The brochure illustrates two bonus scenarios based on assumed rates of 4% and 8%.
These figures are not guaranteed and are provided solely for illustration.
| At 4% p.a. | At 8% p.a. | ||||
| Age | Year | Annualised premium / Maturity benefit | Death benefit | Annualised premium / Maturity benefit | Death benefit |
| 40 | 1 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 41 | 2 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 42 | 3 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 43 | 4 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 44 | 5 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 45 | 6 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 46 | 7 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 47 | 8 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 48 | 9 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 49 | 10 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 50 | 11 | 0 | 11,00,000 | 0 | 11,00,000 |
| 51 | 12 | 0 | 11,00,000 | 0 | 11,00,000 |
| 52 | 13 | 0 | 11,00,000 | 0 | 11,00,000 |
| 53 | 14 | 0 | 11,00,000 | 0 | 11,00,000 |
| 54 | 15 | 0 | 11,00,000 | 0 | 11,00,000 |
| 55 | 11,94,389 | 16,92,730 | |||
| IRR | 1.69% | 5.04% | |||
Under the 4% scenario, the accrued Compounded Revisionary Bonus (CRB) is ₹2.27 lakh, and the terminal bonus is ₹1.30 lakh.
This results in a total maturity benefit of ₹11.94 lakh and an IRR of just 1.69%.
Under the 8% scenario, the accrued CRB is ₹5.54 lakh, while the terminal bonus is ₹3.12 lakh.
The total maturity benefit amounts to ₹16.92 lakh, translating into an IRR of 5.04% as per the INL Milestone Plan maturity calculator.
Despite a 15-year policy term, the returns are disappointing, even under the higher bonus illustration.
The 4% scenario delivers a particularly low return, while the 8% scenario offers limited growth over the long investment horizon.
Overall, the INL Milestone Plan may not be an effective choice for building a substantial corpus to meet long-term financial goals.
11. INL Milestone Plan Vs. Other Investments
As discussed earlier, the potential returns from the INL Milestone Plan fail to keep pace with inflation.
Let us now examine an alternative investment strategy with a similar annual cash outflow to the previous illustration and compare the potential outcomes using the same metric.
INL Milestone Plan Vs. Other Investments
A pure term insurance policy with a sum assured of ₹11 lakh costs an annual premium of ₹8,800 for a 15-year policy term and a 10-year premium payment period.
From the annual outlay of ₹1 lakh, the insurance premium is paid first, and the remaining amount is invested to build wealth.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 11,00,000 |
| Policy Term | 15 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 8,800 |
| Investment | ₹ 91,200 |
The choice of investment instruments should align with your risk tolerance and financial goals.
For this illustration, we consider the Public Provident Fund (PPF) as a debt-oriented investment and an equity mutual fund as an equity-oriented investment.
| Term Insurance + PPF | Term insurance + Equity Mutual Fund | ||||
| Age | Year | Term Insurance premium + PPF | Death benefit | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 40 | 1 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 41 | 2 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 42 | 3 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 43 | 4 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 44 | 5 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 45 | 6 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 46 | 7 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 47 | 8 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 48 | 9 | -1,00,000 | 11,00,000 | -1,00,000 | 11,00,000 |
| 49 | 10 | -97,500 | 11,00,000 | -1,00,000 | 11,00,000 |
| 50 | 11 | -500 | 11,00,000 | 0 | 11,00,000 |
| 51 | 12 | -500 | 11,00,000 | 0 | 11,00,000 |
| 52 | 13 | -500 | 11,00,000 | 0 | 11,00,000 |
| 53 | 14 | -500 | 11,00,000 | 0 | 11,00,000 |
| 54 | 15 | -500 | 11,00,000 | 0 | 11,00,000 |
| 55 | 19,09,957 | 28,93,745 | |||
| IRR | 6.21% | 10.24% | |||
PPF Investment
PPF requires a minimum annual contribution of ₹500 and has a 15-year maturity period.
Since the term insurance premium is payable for only 10 years, the investment contributions are adjusted in the subsequent years to comply with the PPF rules.
Under this illustration, the final maturity value is ₹19.09 lakh, generating an IRR of 6.21%.
Equity Mutual Fund Investment
Equity mutual fund investments are subject to capital gains tax upon redemption, wherever applicable.
In this illustration, the investment grows to ₹31.58 lakh before tax and ₹28.93 lakh after tax, translating into a post-tax IRR of 10.24%.
The tax calculation is provided below.
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 15 years | 31,58,994 |
| Purchase price | 9,12,000 |
| Long-Term Capital Gains | 22,46,994 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 21,21,994 |
| Tax paid on LTCG | 2,65,249 |
| Maturity value after tax | 28,93,745 |
This comparison highlights the potential benefits of keeping insurance and investments separate.
By opting for adequate life cover through a pure term insurance policy and investing the surplus in suitable instruments, you can potentially achieve better returns and greater flexibility than with the INL Milestone Plan.
12. Final Verdict on INL Milestone Plan
The INL Milestone Plan combines life insurance coverage with a maturity benefit and bonuses.
However, the bonuses are non-guaranteed, making the final benefits uncertain and difficult to predict.
This uncertainty can make it challenging to align the proceeds with specific financial goals.
Moreover, the sum assured may be insufficient to meet your family’s future financial needs.
The returns analysis indicates that the maturity benefit, including bonuses, may not generate sufficient returns to keep pace with inflation and the rising costs of long-term financial goals.
Overall, the plan may fall short of delivering adequate life protection as well as meaningful wealth creation and it also has a high agent commission.
When choosing a financial product, it is important to assess whether its potential returns can help you meet your goals after accounting for inflation.
Investing in the INL Milestone Plan may limit your ability to build the required corpus for your long-term needs.
An alternative strategy demonstrates the benefits of separating insurance and investment.
A pure term insurance policy provides substantial life cover at a relatively affordable premium, while investing the surplus in suitable financial instruments offers greater flexibility and the potential to build wealth in line with your goals.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
For personalised guidance on choosing appropriate insurance coverage and investment products, consider consulting a Certified Financial Planner (CFP).
A CFP can help you develop a comprehensive financial plan tailored to your needs, risk tolerance, and long-term objectives.
Leave a Comment