 Listen to this article
Can the HDFC Life Aajeevan Growth Nivesh and Income Plan truly provide long-term financial growth and a reliable income stream, or do its benefits come with important trade-offs?
Does the HDFC Life Aajeevan Growth Nivesh and Income Plan offer the right balance between wealth creation and regular income, or are there better financial alternatives available?
Is the HDFC Life Aajeevan Growth Nivesh and Income Plan a smart choice for building wealth and generating income, or could its limitations affect your financial goals?
Let us examine the plan’s features and evaluate whether it offers an effective retirement solution.
Table of Contents:
What is the HDFC Life Aajeevan Growth Nivesh and Income?
What are the features of the HDFC Life Aajeevan Growth Nivesh and Income?
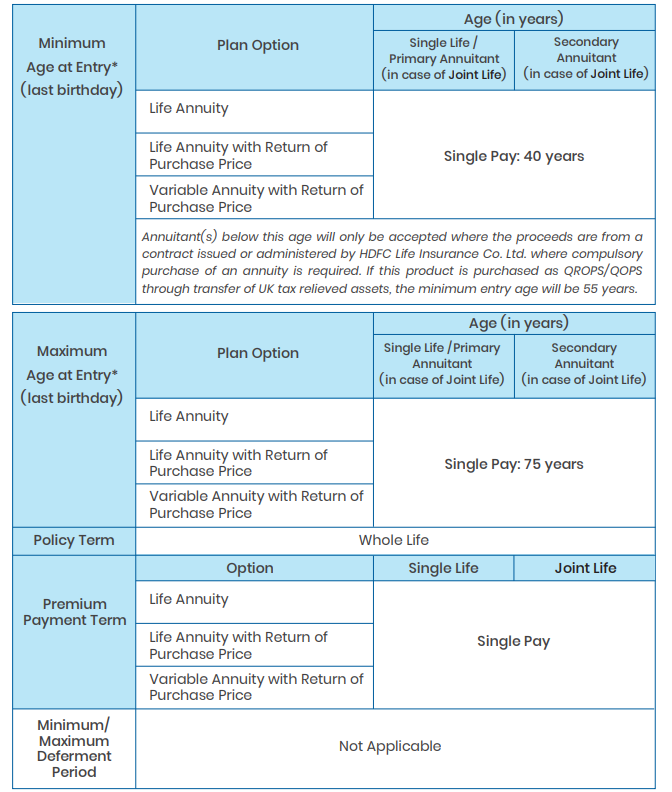
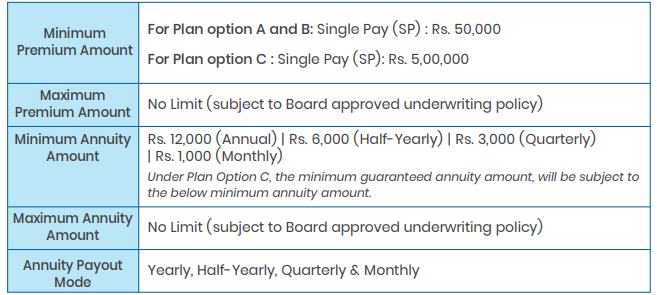
Who is eligible for the HDFC Life Aajeevan Growth Nivesh and Income?
What are the plan options and their benefits of the HDFC Life Aajeevan Growth Nivesh and Income?
Free Look Period for the HDFC Life Aajeevan Growth Nivesh and Income
Surrendering the HDFC Life Aajeevan Growth Nivesh and Income
What are the advantages of the HDFC Life Aajeevan Growth Nivesh and Income?
What are the disadvantages of the HDFC Life Aajeevan Growth Nivesh and Income?
Research Methodology of HDFC Life Aajeevan Growth Nivesh and Income Plan
Benefit Illustration – IRR Analysis of HDFC Life Aajeevan Growth Nivesh and Income
HDFC Life Aajeevan Growth Nivesh and Income Vs. Other Investments
HDFC Life Aajeevan Growth Nivesh and Income Vs. Fixed-Income Investments
HDFC Life Aajeevan Growth Nivesh and Income Vs. Inflation-adjusted Income
Final Verdict on the HDFC Life Aajeevan Growth Nivesh and Income
What is the HDFC Life Aajeevan Growth Nivesh and Income?
HDFC Life Aajeevan Growth Nivesh and Income is a Non-Participating, Non-Linked, General Annuity, Individual, Savings Plan.
It provides lifetime income, offering stability along with the potential to maximise your income through exposure to the NIFTY 50 benchmark.
What are the features of the HDFC Life Aajeevan Growth Nivesh and Income?
- Guaranteed Income with Market-Linked Upside: Offers a variable annuity with a Return of Purchase Price option, combining lifelong income with potential upside linked to the Nifty 50 benchmark.
- Flexible Payout Options: Choose between a lump-sum payout and a lifetime annuity, depending on your income requirements.
- Simple and Transparent: No complex fund choices or periodic switching required.
- Single and Joint Life Coverage: Caters to both individual and joint-life retirement needs.
- Three Annuity Options: Choose from three available annuity options to suit your retirement preferences.
Who is eligible for the HDFC Life Aajeevan Growth Nivesh and Income?
What are the plan options and their benefits of the HDFC Life Aajeevan Growth Nivesh and Income?
You can choose any of the following annuity options at inception.
A. Life Annuity
B. Life Annuity with Return of Purchase Price
C. Variable Annuity with Return of Purchase Price
1. Survival Benefit
Life Annuity
The annuity will be paid in arrears as per the payment frequency chosen by the HDFC Life Aajeevan Growth Nivesh and Income Plan policyholder, as long as the annuitant(s) is/are alive.
Guaranteed Annuity Payout: Annuity Rate * Single Premium
Life Annuity with Return of Purchase Price
The annuity will be paid in arrears as per the payment frequency chosen by the HDFC Life Aajeevan Growth Nivesh and Income Plan policyholder, as long as the annuitant(s) is/are alive.
Guaranteed Annuity Payout: Annuity Rate * Single Premium.
Variable Annuity with Return of Purchase Price
Under this option, the annuitant will receive a lifetime guaranteed annuity payout, at a minimum guaranteed annuity rate, as prescribed in the regulatory provisions, along with the variable annuity payouts linked to a publicly available benchmark.
Here, the guaranteed annuity proportion is 60% of the Purchase Price.
The annuity payout shall be equal to the sum of the following:
- Guaranteed Annuity Pay-out = Guaranteed Annuity Proportion * Annuity Rate * Single Premium, and
- Variable Annuity Payout
2. Death Benefit
Life Annuity
No Benefits will be paid upon death under this option. The HDFC Life Aajeevan Growth Nivesh and Income Plan policy shall terminate, and all other benefits shall cease.
Life Annuity with Return of Purchase Price
100% of the Purchase Price is paid as the death benefit. Upon payment of the death benefit, the policy shall terminate, and all other benefits shall cease.
Variable Annuity with Return of Purchase Price
The sum of the following is paid as the death benefit.
- 100% of the Purchase Price, and
- Variable Pay-out Death Benefit, if any
Upon payment of the death benefit, the policy shall terminate, and all other benefits shall cease.
Free Look Period for the HDFC Life Aajeevan Growth Nivesh and Income
In case the insured is not agreeable to any policy terms and conditions under this product, the insured shall have the option of returning the policy to us, stating the reasons thereof, within 30 days from the date of receipt of the policy, whether received electronically or otherwise.
Surrendering the HDFC Life Aajeevan Growth Nivesh and Income
Surrender value payable will be equal to the higher of the Guaranteed Surrender Value (GSV) and Special Surrender Value (SSV).
Guaranteed Surrender Value (GSV):
For Option A, GSV will be 0.
For Option B & Option C, GSV will be calculated using the following formula: GSV = GSV Factor * Purchase Price – Guaranteed Annuity Payouts (till date of surrender)
Special Surrender Value (SSV):
For Option A, SSV will be 0
For Option B & Option C, SSV will be calculated using the following formula: SSV =Maximum of
- 90% * Purchase Price – annuity instalments paid during the year of surrender
- F3 * (F1 * Guaranteed Annuity pay-out p.a. + F2 * DB Multiple * Total Premiums Paid) – guaranteed annuity instalments paid during the year of surrender + Variable Surrender Benefit Payout (if applicable)
Where F1 is the annuity factor, F2 is the assurance factor, and F3 is the discounting factor in the deferment period.
What are the advantages of the HDFC Life Aajeevan Growth Nivesh and Income?
- Additional Annuity Benefit: Higher purchase prices qualify for an additional annuity, calculated as a percentage of the Purchase Price.
- Loan Facility: Loans are available only under Option B and Option C.
- Single-Premium Convenience: A one-time investment with no recurring premium commitments, offering a simple and hassle-free purchase experience.
What are the disadvantages of the HDFC Life Aajeevan Growth Nivesh and Income?
- No Inflation Protection: The annuity amount remains fixed throughout your lifetime and does not increase to offset inflation.
- Annuity Rate Lock-in: The annuity rate is determined and locked in at the time of policy inception (Option A &B)
- Taxable Income: Annuity payouts are taxable as per your applicable income tax slab.
- Limited Liquidity: Option A does not offer a surrender or loan facility.
- Market-Linked Risk: Under Option C, annuity payouts are influenced by market performance, making the income less predictable.
Research Methodology of HDFC Life Aajeevan Growth Nivesh and Income Plan
Calculating the Internal Rate of Return (IRR) helps assess whether this plan is a suitable investment for your long-term financial goals.
Comparing its IRR with alternative investment avenues can help you make an informed decision. Let us evaluate the returns using a quotation generated from the insurer’s official portal.
Benefit Illustration – IRR Analysis of HDFC Life Aajeevan Growth Nivesh and Income
Consider a 60-year-old male investing a single premium of ₹10 lakh under Plan Option B – Life Annuity with Return of Purchase Price. He opts for annual annuity payouts and receives ₹62,200 every year.
| Male | 60 years |
| Purchase Price | ₹10 Lakhs |
| Life Expectancy | 85 years |
| Annuity (per annum) | ₹ 62,200 |
Since the annuity is payable for life, we assume a life expectancy of 85 years. On his demise at age 85, the nominee receives the original Purchase Price of ₹10 lakh.
Based on these projected cash flows, the plan delivers an IRR of 6.11% as per the HDFC Life Aajeevan Growth Nivesh and Income Plan maturity calculator.
| Age | Option B: Life Annuity with Return of Purchase Price |
| 60 | -10,00,000 |
| 61 | 62,200 |
| 62 | 62,200 |
| 63 | 62,200 |
| 64 | 62,200 |
| 65 | 62,200 |
| 66 | 62,200 |
| 67 | 62,200 |
| 68 | 62,200 |
| 69 | 62,200 |
| 70 | 62,200 |
| 71 | 62,200 |
| 72 | 62,200 |
| 73 | 62,200 |
| 74 | 62,200 |
| 75 | 62,200 |
| 76 | 62,200 |
| 77 | 62,200 |
| 78 | 62,200 |
| 79 | 62,200 |
| 80 | 62,200 |
| 81 | 62,200 |
| 82 | 62,200 |
| 83 | 62,200 |
| 84 | 62,200 |
| 85 | 10,00,000 |
| IRR | 6.11% |
A bank Fixed Deposit (FD) could potentially offer a higher return while providing greater flexibility and access to the invested corpus, subject to its applicable terms and premature withdrawal conditions.
In contrast, an annuity investment involves committing the purchase price for lifelong income. Under Option B, the purchase price is returned to the nominee only upon the annuitant’s death.
Overall, the HDFC Life Aajeevan Growth Nivesh and Income Plan offers limited returns and liquidity under this option.
There are alternative investment strategies that may provide better returns and greater flexibility. Let us explore them in the next section.
HDFC Life Aajeevan Growth Nivesh and Income Vs. Other Investments
Instead of locking your entire retirement corpus into an annuity plan, you can explore investment options that generate a regular income while giving you greater control over your money.
These alternatives offer competitive returns and the flexibility to structure cash flows according to your retirement needs.
HDFC Life Aajeevan Growth Nivesh and Income Vs. Fixed-Income Investments
Here are some fixed-income investment options that offer potentially better returns and greater liquidity than the HDFC Life Aajeevan Growth Nivesh and Income Plan:
- Bank Fixed Deposits (FDs): A relatively safe investment option offering fixed interest rates and predictable returns, making them suitable for retirees seeking regular income.
- Senior Citizens’ Savings Scheme (SCSS): A government-backed savings scheme offering attractive interest rates and periodic income with relatively low investment risk.
- RBI Floating Rate Savings Bonds: Government-backed bonds with interest rates linked to market benchmarks, providing regular interest payouts. However, the interest rate is subject to periodic revisions.
| Fixed income instrument | Interest Rate |
| Senior Citizen Savings Schemes (SCSS) | 8.20% |
| Bank FD | 6% – 7% |
| RBI Floating Rate Bonds | 8.05% (Floating) |
These fixed-income instruments offer better access to your invested corpus, subject to their respective withdrawal and maturity conditions.
However, relying entirely on fixed-income investments may not protect your retirement savings from inflation, which gradually erodes purchasing power.
To address this limitation, consider incorporating equity into your retirement portfolio for long-term growth.
A balanced allocation between equity and debt, supported by periodic rebalancing and a systematic withdrawal strategy, can help generate inflation-adjusted cash flows while preserving your corpus over the long term.
HDFC Life Aajeevan Growth Nivesh and Income Vs. Inflation-adjusted Income
Using the same example as the HDFC Life Aajeevan Growth Nivesh and Income Plan, let us evaluate how a retirement corpus of ₹10 lakh can be utilised to generate an initial annual income of ₹62,200 while retaining the potential for long-term growth.
We assume an asset allocation of 60:40, with ₹6 lakh (60%) invested in equity for capital appreciation and ₹4 lakh (40%) allocated to debt instruments to support regular withdrawals. The assumed annual returns are 12% for equity and 6% for debt.
| Age | Equity Portion | Shift from Equity to Debt | Debt Portion | ||||
| Opening Balance | Yearly withdrawal | Closing Balance | Opening Balance | Yearly withdrawal | Closing Balance | ||
| 61 | 6,00,000 | 0 | 6,72,000 | 0 | 4,00,000 | 62,200 | 3,58,068 |
| 62 | 6,72,000 | 0 | 7,52,640 | 0 | 3,58,068 | 62,200 | 3,13,620 |
| 63 | 7,52,640 | 0 | 8,42,957 | 0 | 3,13,620 | 62,200 | 2,66,505 |
| 64 | 8,42,957 | 0 | 9,44,112 | 0 | 2,66,505 | 62,200 | 2,16,564 |
| 65 | 9,44,112 | 0 | 10,57,405 | 0 | 2,16,564 | 62,200 | 1,63,625 |
| 66 | 10,57,405 | 4,00,000 | 7,36,294 | 4,00,000 | 5,63,625 | 65,932 | 5,27,555 |
| 67 | 7,36,294 | 0 | 8,24,649 | 0 | 5,27,555 | 65,932 | 4,89,320 |
| 68 | 8,24,649 | 0 | 9,23,607 | 0 | 4,89,320 | 65,932 | 4,48,792 |
| 69 | 9,23,607 | 0 | 10,34,440 | 0 | 4,48,792 | 65,932 | 4,05,831 |
| 70 | 10,34,440 | 0 | 11,58,572 | 0 | 4,05,831 | 65,932 | 3,60,293 |
| 71 | 11,58,572 | 11,58,572 | 0 | 11,58,572 | 15,18,866 | 69,888 | 15,35,916 |
| 72 | 0 | 0 | 0 | 0 | 15,35,916 | 69,888 | 15,53,990 |
| 73 | 0 | 0 | 0 | 0 | 15,53,990 | 69,888 | 15,73,148 |
| 74 | 0 | 0 | 0 | 0 | 15,73,148 | 69,888 | 15,93,456 |
| 75 | 0 | 0 | 0 | 0 | 15,93,456 | 69,888 | 16,14,982 |
| 76 | 0 | 0 | 0 | 0 | 16,14,982 | 74,081 | 16,33,355 |
| 77 | 0 | 0 | 0 | 0 | 16,33,355 | 74,081 | 16,52,830 |
| 78 | 0 | 0 | 0 | 0 | 16,52,830 | 74,081 | 16,73,474 |
| 79 | 0 | 0 | 0 | 0 | 16,73,474 | 74,081 | 16,95,356 |
| 80 | 16,95,356 | 74,081 | 17,18,552 | ||||
| 81 | 17,18,552 | 78,526 | 17,38,427 | ||||
| 82 | 17,38,427 | 78,526 | 17,59,495 | ||||
| 83 | 17,59,495 | 78,526 | 17,81,827 | ||||
| 84 | 17,81,827 | 78,526 | 18,05,499 | ||||
| 85 | 18,05,499 | 78,526 | 18,30,591 | ||||
The initial annual withdrawal is ₹62,200, with a 6% increase every five years to account for inflation. To maintain the desired asset allocation and ensure sufficient funds for regular income, a portion of the equity investment is transferred to debt every five years.
The final transfer takes place at age 71, helping maintain liquidity and stability during the later retirement years.
Based on these assumptions, the portfolio retains a corpus of approximately ₹18 lakh at age 85, even after meeting inflation-adjusted withdrawal requirements throughout the period.
This is significantly higher than the ₹10 lakh Purchase Price returned to the nominee under the HDFC Life plan.
This strategy offers three key advantages:
- Regular Income: Provides periodic withdrawals to meet retirement expenses.
- Inflation Protection: Gradually increases withdrawals to account for rising living costs.
- Corpus Sustainability: Retains the potential for capital appreciation while managing withdrawals through an equity-debt allocation.
The key takeaway is that retirement planning need not be restricted to purchasing an annuity.
A well-structured investment portfolio can provide regular income, flexibility and the potential to preserve and grow your retirement corpus.
Final Verdict on the HDFC Life Aajeevan Growth Nivesh and Income
The HDFC Life Aajeevan Growth Nivesh and Income Plan is an immediate annuity product designed to provide a regular income throughout your lifetime.
With three annuity options and flexible payout frequencies, it may appear attractive to senior citizens looking for a predictable post-retirement income.
However, Option C introduces market-linked variability in annuity payouts, as a portion of the Purchase Price is exposed to market movements.
When you invest independently, you have the flexibility to rebalance your portfolio based on your age, changing financial needs and market conditions. The plan does not offer the same level of control.
A closer evaluation also reveals relatively modest returns and limited liquidity. Once invested, your corpus is largely locked in, leaving you dependent on the annuity payouts. You cannot readily access the capital to meet unexpected expenses or other financial goals.
Relying entirely on this plan as your primary source of retirement income could therefore create financial constraints in the long run and it also has a high agent commission.
As discussed earlier, a balanced portfolio combining equity for long-term growth and debt for stability and regular withdrawals can offer better flexibility and growth potential than relying solely on an annuity.
More importantly, the investment strategy can be customised to suit your retirement goals, cash-flow requirements and risk tolerance.
Do not depend entirely on ready-made annuity or pension products to fund your retirement.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
Instead, consult a Certified Financial Planner who can develop a customised retirement income strategy that balances regular cash flows, inflation protection, liquidity and long-term financial security.
Leave a Comment