 Listen to this article
Is the Axis Max Life Online Savings Plan a comprehensive financial solution for achieving life goals?
Can the Axis Max Life Online Savings Plan provide life insurance coverage along with investment returns?
Can the Axis Max Life Online Savings Plan help you achieve your important financial goals?
Let us examine the Axis Max Life Online Savings Plan Plus in detail to assess whether it lives up to these claims and whether it deserves a place in your investment portfolio.
Table of Contents
What is the Axis Max Life Online Savings Plan Plus?
What are the features of the Axis Max Life Online Savings Plan Plus?
Who is eligible for the Axis Max Life Online Savings Plan Plus?
What are the benefits of the Axis Max Life Online Savings Plan Plus?
What are the investment strategies and fund options in the Axis Max Life Online Savings Plan Plus?
What are the charges of the Axis Max Life Online Savings Plan Plus?
Grace Period, Discontinuance and Revival of the Axis Max Life Online Savings Plan Plus
Free Look Period for the Axis Max Life Online Savings Plan Plus
Surrendering the Axis Max Life Online Savings Plan Plus
What are the advantages of the Axis Max Life Online Savings Plan Plus?
What are the disadvantages of the Axis Max Life Online Savings Plan Plus?
Research Methodology of the Axis Max Life Online Savings Plan Plus
Benefit Illustration – IRR Analysis of Axis Max Online Savings Plan Plus
Axis Max Life Online Savings Plan Plus Vs. Other Investments
Axis Max Life Online Savings Plan Plus Vs. Pure-term + PPF/Equity Mutual Fund
Final Verdict on Axis Max Life Online Savings Plan Plus
1. What is the Axis Max Life Online Savings Plan Plus?
Axis Max Life Online Savings Plan Plus is a Unit Linked Non-Participating Individual Life Insurance Savings Plan.
It offers life insurance protection for your family and provides market-linked returns.
Under this plan, you can choose from the five plan variants based on your life stage needs.
2. What are the features of the Axis Max Life Online Savings Plan Plus?
The plan offers five variants – Wealth, Wealth Whole Life, Gold, Platinum and Titanium – designed to cater to different life stages and financial goals.
- Zero Premium Allocation Charge: No premium allocation charges are levied under this product.
- Return of Policy Administration Charges: Get a refund of up to 150% of the policy administration charges.
- Enhanced Premium Funding: Choose between 1x, 2x or 3x premium funding in the event of the life insured’s demise.
- Additional Allocation for Women: Female life insureds are eligible for an additional allocation benefit.
- Wide Choice of Investment Options: Choose from 28 investment funds and 5 investment strategies based on your risk appetite.
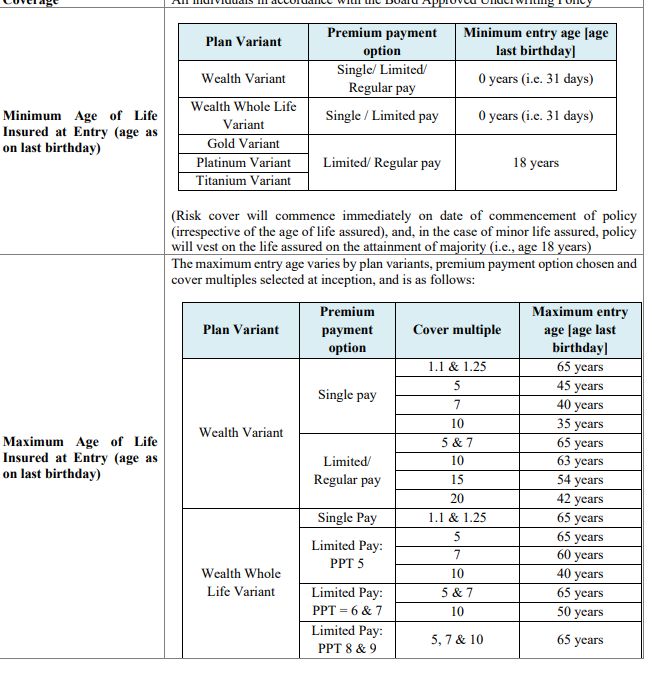
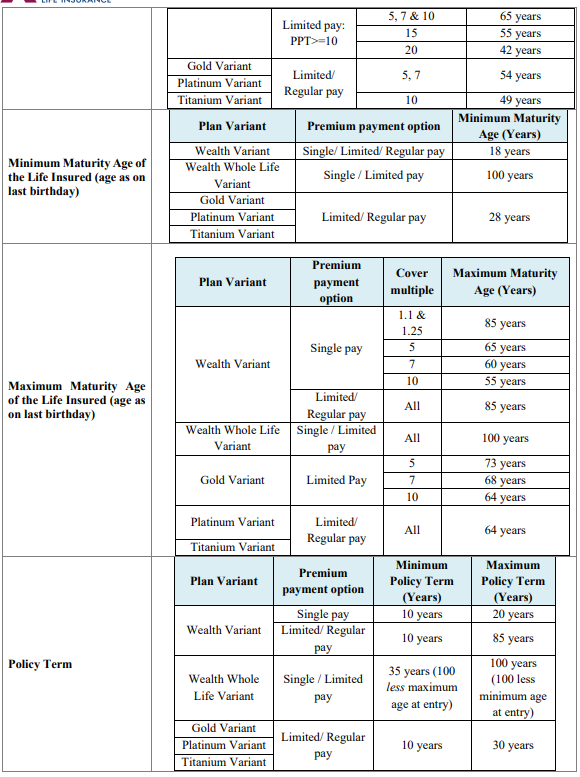
3. Who is eligible for the Axis Max Life Online Savings Plan Plus?
4. What are the benefits of the Axis Max Life Online Savings Plan Plus?
| S. No. | Plan Variant | Base Death Benefit | Funding of Premium | Family Income Benefit |
| 1 | Wealth Variant | Yes | No | No |
| 2 | Wealth Whole Life Variant | Yes | No | No |
| 3 | Gold Variant | Yes | Yes (1X) | Yes |
| 4 | Platinum Variant | Yes | Yes (2X) | Yes |
| 5 | Titanium Variant | Yes | Yes (3X) | No |
a. Death Benefit
For Wealth Variant and Wealth Whole Life Variant:
On death of the Life Insured anytime during the term of the policy, the death benefit payable shall be the highest of the following benefits:
- Sum Assured chosen at inception or annualised / single premium chosen at inception times cover multiple (reduced by applicable partial withdrawals, if any); or
- 105% of Total Premiums Paid up to the date of death of the Life Insured (reduced by applicable partial withdrawals, if any; or
- the total Fund Value (as on the date of intimation of death of the Life Insured)
For ‘Gold Variant’ or ‘Platinum Variant’ or ‘Titanium Variant’:
On death of the Life Insured anytime during the term of the policy, the death benefit payable to the claimant shall be the sum of the following:
Lump Sum Benefit: Higher of Sum Assured chosen at inception (or annualised premium chosen at inception times cover multiple) or 105% of the total premiums paid up to the date of death (whichever is applicable) plus
Family Income Benefit (applicable for Gold and Platinum variants only): A Family Income Benefit equal to 1% of the Sum Assured chosen at inception (or annualised premium chosen at inception times cover multiple) will be paid each month starting from the policy anniversary date of every month following or coinciding with the date of death of the life insured till the end of the policy term (including the payout at the maturity date), subject to a minimum of 36 monthly payments and a maximum of 120 monthly payments. Plus
Funding of Premium: The Company will fund X times (where X=1, 2, or 3 for Gold, Platinum & Titanium variants respectively) of all future outstanding premiums as and when due under the policy on each future premium due date(s). Fund Value as on the date of maturity will be paid at the end of the policy term.
b. Maturity Benefit
Upon maturity, if the Life Insured is alive (except where the ‘Gold Variant’ or ‘Platinum Variant’ or ‘Titanium Variant’ has been opted; in case of death of Life Insured, the maturity benefit will be paid to the claimant) and the policy is in force or if this Axis Max Life Online Savings Plan Plus policy is a paid-up Policy, then the Fund Value applicable on the Maturity Date shall be payable.
You will have the option to receive the Maturity benefit as a lump sum or as a systematic payout for a maximum of five years under the Settlement Option.
Return of Policy Administration Charges
A fixed percentage of total Policy Administration Charges deducted shall be added back as Return of Policy Administration Charge to the Fund Value at maturity or at the end of (85 less Age at entry) policy year, whichever is earlier
5. What are the investment strategies and fund options in the Axis Max Life Online Savings Plan Plus?
Under Axis Max Life Online Savings Plan Plus, you have a range of 27 funds and 5 investment strategies to choose from.
You may choose only one of the five available investment strategies.
Self-Managed Portfolio Strategy
In this strategy, the policyholder manages his/her investments by choosing amongst the following investment funds in proportion of his/her choice:
|
|
Asset Allocation | |||||
| S no | Funds | Risk Rating | Government Securities | Corporate Bonds | Money Market & Cash Instruments |
Equities |
|
1 |
High Growth | Very High | 0-30 | 0-30 | 0-30 | 70-100 |
| 2 | Nifty Small Cap Quality Index Fund | Very High | 0 | 0 | 0-20 |
80-100 |
|
3 |
Nifty Alpha 50 | Very High | 0 | 0 | 0-20 | 80-100 |
| 4 | Nifty 500 Momentum 50 | Very High | 0 | 0 | 0-20 |
80-100 |
|
5 |
Mid cap Momentum Index | Very High | 0 | 0 | 0-20 | 80-100 |
| 6 | Nifty Momentum Quality 50 Fund | Very High | 0 | 0 | 0-20 |
80-100 |
|
7 |
Sustainable Wealth 50 Index Fund | Very High | 0 | 0 | 0-20 | 80-100 |
| 8 | Smart Innovation Fund | Very High | 0-30 | 0-30 | 0-30 |
70-100 |
|
9 |
Nifty 500 Multifactor 50 Index Fund | Very High | 0 | 0 | 0-20 | 80-100 |
| 10 | BSE 500 Value 50 Index Fund | Very High | 0 | 0 | 0-20 |
80-100 |
|
11 |
BSE 500 Dividend Leaders 50 Index Fund | Very High | 0 | 0 | 0-20 | 80-100 |
| 12 | India Consumption Opportunities Fund | Very High | 0-30 | 0-30 | 0-30 |
70-100 |
|
13 |
BSE Dividend Stability Index Fund | Very High | 0 | 0 | 0-20 | 80-100 |
| 14 | India Sector Leaders Opportunities Fund | Very High | 0 | 0 | 0-20 |
80-100 |
|
15 |
Rising India Manufacturing Fund | Very High | 0-20 | 0 | 0-20 | 80 – 100 |
| 16 | Flexi Cap Fund | Very High | 0-20 | 0-20 | 0-20 |
80-100 |
|
17 |
BSE 500 Value 50 Index Fund II | Very High | 0 | 0-20 | 0-10 | 90-100 |
| 18 | Diversified Equity Fund II | High | 0-20 | 0-20 | 0-20 |
80-100 |
|
19 |
Growth Super Fund II | High | 0-20 | 0-20 | 0-20 | 80-100 |
| 20 | Growth Fund | High | 0-30 | 0-30 | 0-40 |
20-70 |
|
21 |
Sustainable Equity Fund | High | 0-20 | 0-20 | 0-30 | 70-100 |
| 22 | Pure Growth Fund | High | 0 | 0 | 0-40 |
60-100 |
|
23 |
Balanced Fund | Medium | 20-50 | 20-40 | 0-40 | 10 to 40 |
| 24 | Conservative Fund | Low | 50-80 | 0-50 | 0-40 |
0-15 |
|
25 |
Dynamic Bond Fund | Low | 60-100 | 0-40 | 0 | |
| 26 | Secure Fund | Low | 50-100 | 0-50 | 0-40 |
0 |
|
27 |
Secure Plus Fund | Low | 60-100 | 0-40 | 0-40 | 0 |
|
28 |
Money Market II Fund | Low | 0 | 0 | 100 |
0 |
Systematic Transfer Plan (STP)
This option can be chosen by the policyholder only if the annual pay mode of premium frequency has been chosen.
The annual premium received, net of the premium allocation charge and GST, shall be allocated first to Secure Plus Fund; i.e. units will be purchased in Secure Plus Fund based on the applicable NAV at that time. Immediately thereafter and on each subsequent monthly anniversary, units available in Secure Plus Fund will be systematically transferred to any of the equity-oriented funds (to be chosen at inception of policy).
Lifecycle Based Portfolio Strategy
In this investment strategy, the investments will be distributed between Fund 1 & Fund 2 with their proportions varying as per the different life stages.
Fund 1 would essentially be an equity-oriented fund, whereas Fund 2 would be a debt-oriented fund.
|
Fund options for Fund 1 |
Fund options for Fund 2 |
| Diversified Equity Fund II |
Conservative Fund |
|
Growth Super Fund II |
Secure Fund |
| Growth Fund |
Secure Plus Fund |
At inception, the premium received, net of premium allocation charges and GST, will be distributed between the two funds based on life assureds’ entry age as per the table below.
The attained age shall be checked at every policy anniversary, and the funds will be redistributed according to the attained age as given in the following table.
|
Age last birthday |
Proportion in Fund 1 | Proportion in Fund 2 |
| Up to 25 | 85% |
15% |
|
26-30 |
80% | 20% |
| 31-35 | 75% |
25% |
|
36-40 |
70% | 30% |
| 41-45 | 65% |
35% |
|
46-50 |
50% | 50% |
| 51-55 | 35% |
65% |
|
56 and above |
30% |
70% |
Trigger Based Portfolio Strategy
Within this strategy, any premium paid by the Axis Max Life Online Savings Plan Plus policyholder will be allocated to two funds – Fund 1 and Fund 2- in a 75%: 25% proportion.
The fund allocation may subsequently fluctuate due to market movements. The policyholder’s portfolio will be rebalanced, and the funds will be re-allocated based on a pre-defined trigger event, which would be checked at every monthly anniversary of the policy.
This trigger event is defined as an upward movement of x% in the NAV of Fund 1 since the previous rebalancing.
| Fund options for Fund 1 | Fund options for Fund 2 |
| Diversified Equity Fund II | Conservative Fund |
| Growth Super Fund II | Secure Fund |
| Growth Fund | Secure Plus Fund |
Dynamic Fund Allocation (DFA) strategy
Under this strategy, switching of existing fund value shall happen on the policy anniversary, and allocation of premium received between funds shall happen on the date of receipt of such premium in the proportion mentioned in the table below.
| Years to maturity | Proportion in Growth Super Fund II | Proportion in Secure Fund |
| 16 and further | 80% | 20% |
| 11 to 15 | 60% | 40% |
| 6 to 10 | 40% | 60% |
| 0 to 5 | 20% | 80% |
6. What are the charges of the Axis Max Life Online Savings Plan Plus?
Premium Allocation Charge
Nil.
Policy Administration Charge (All Years)
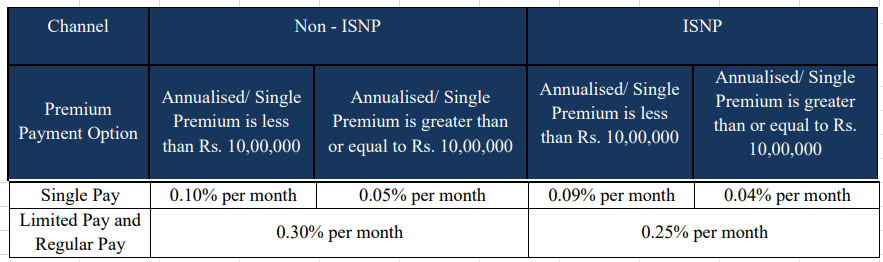
The Axis Max Life Online Savings Plan Plus policy administration charge (as a percentage of annualized/single premium) will be deducted as below, subject to a cap of Rs. 500 per month.
Fund Management Charge
|
Fund Name |
Fund Management Charge (p.a.) |
|
High Growth Fund II |
1.35% |
| Midcap Momentum Index Fund |
1.25% |
|
Nifty Alpha 50 Fund |
1.25% |
| Nifty 500 Momentum 50 Fund |
1.25% |
|
Sustainable Wealth 50 Index Fund |
1.25% |
| Smart Innovation Fund |
1.25% |
|
Nifty 500 Multifactor 50 Index Fund |
1.25% |
| BSE 500 Value 50 Index Fund |
1.25% |
|
India Consumption Opportunities Fund |
1.25% |
| BSE 500 Dividend leaders 50 Index Fund |
1.25% |
|
Diversified Equity Fund II |
1.35% |
|
Growth Super Fund II |
1.35% |
| BSE 500 Value 50 Index Fund II |
1.35% |
|
BSE Dividend Stability Index Fund |
1.35% |
| India Sector Leaders Opportunities Fund |
1.35% |
|
Rising India Manufacturing Fund |
1.35% |
| Flexi Cap Fund (SFIN: |
1.35% |
|
Growth Fund |
1.25% |
| Sustainable Equity Fund |
1.25% |
|
Pure Growth Fund |
1.25% |
| Nifty Momentum Quality 50 Fund |
1.25% |
|
Balanced Fund |
1.10% |
| NIFTY Smallcap Quality Index Fund |
1.00% |
|
Conservative Fund |
0.90% |
| Dynamic Bond Fund |
0.90% |
|
Secure Fund |
0.90% |
| Secure Plus Fund |
0.90% |
|
Money Market II Fund |
0.90% |
| Discontinuance Policy Fund |
0.50% |
Mortality Charge
The charge will be levied on the basis of ‘Sum at Risk’ on every monthly anniversary by cancelling units from the unit account.
The mortality charge on death benefit will be on an attained age basis of the life insured over the duration of the contract.
Surrender / Discontinuance Charge
This charge shall be levied on the Fund Value at the time of Discontinuance of Policy or effecting Complete Withdrawal (Surrender), whichever is earlier.
This charge is expressed as the lower of (X% of Annualised premium, X% of Fund Value, ‘Y’ fixed rupee amount) where X and Y vary according to the year of premium discontinuance/surrender.
Rider Charge
Nil
Switch Charge
All switches will be free of charge.
Premium Redirection Charge
There is no charge for premium redirection.
Smart Withdrawal Charge
Smart withdrawals are free of charge.
Partial Withdrawal Charge
Partial withdrawals are free of any charge.
Alteration Charge
No charge is applicable for any premium, premium payment term or policy term.
Miscellaneous Charges
There are no miscellaneous charges.
Inference from the Charges: Certain charges under the Axis Max Life Online Savings Plan Plus, such as mortality charges and fund management charges, are necessary to provide insurance coverage and manage the investment funds.
However, charges such as policy administration charges and discontinuance/surrender charges add to the overall cost of the product. These additional charges are generally not applicable in the same manner to standalone market-linked investments, such as mutual funds.
Over the long term, these charges reduce the amount available for investment and adversely affect the accumulated fund value, thereby impacting your overall returns.
7. Grace Period, Discontinuance and Revival of the Axis Max Life Online Savings Plan Plus
Grace Period
In case the premium is not paid by the premium due date, a Grace Period of 30 days (15 days for monthly mode) from the due date of the first unpaid premium will be allowed.
Discontinuance
Discontinuance of payment of premium during the first five policy years (Lock-in Period): the fund value after deducting the applicable discontinuance charges shall be credited to the discontinued policy fund and the risk cover and rider cover, if any, shall cease. The proceeds of the discontinued policy fund shall be paid to the policyholder at the end of the revival period or lock-in period, whichever is later
In case of Discontinuance of payment of premium post first five policy years (i.e. after the expiry of the Lock-in Period): the policy shall be converted into a reduced paid-up policy with the paid-up sum assured, where paid-up sum assured is reduced proportionately.
Revival
You will have a revival period of three years from the date of first unpaid premium to revive the policy.
8. Free Look Period for the Axis Max Life Online Savings Plan Plus
Free Look means a period of thirty (30) days beginning from the date of receipt of the policy document, whether received electronically or otherwise, to review the terms and conditions of the policy.
If the Axis Max Life Online Savings Plan Plus policyholder disagrees with any of the policy terms or conditions, or otherwise and has not made any claim, the policyholder shall have the option to return the policy for cancellation, stating the reasons for the same.
9. Surrendering the Axis Max Life Online Savings Plan Plus
Surrender within five years of the Effective Date of the policy (i.e. within the Lock-in Period): the Company will credit the Fund Value by creation of units into the Discontinuance Policy Fund after deducting applicable Surrender / Discontinuance Charges.
At the expiry of five years from the effective date of the policy (i.e. at the expiry of the Lock-in Period), the Company will close the Unit Account and pay you the value of units in the Discontinuance Policy Fund as at that date, and the policy will terminate
Surrender after five years from the Effective Date of the policy (i.e. after the completion of Lock-in Period): The company shall close the Unit Account and pay the Surrender Value which is equal to the Fund Value of the Units in the Segregated Fund(s) on the date of receipt of surrender request and the policy shall terminate thereafter.
10. What are the advantages of the Axis Max Life Online Savings Plan Plus?
- Premium Redirection and Fund Switching: You can redirect future premiums to other available funds and switch your existing investments between funds.
- Partial Withdrawals: Unlimited partial withdrawals are permitted after completion of the first five policy years.
- Smart Withdrawal Facility: Allows you to withdraw a predetermined percentage of the fund value at regular intervals.
- Additional Riders: You can enhance your policy coverage by opting for additional riders, subject to applicable terms and conditions.
- Settlement Option: You can extend the policy beyond its maturity date for up to five years, during which the fund value can be received in instalments.
- Premium Reduction: After completion of the first five policy years, you can reduce the premium by up to 50% of the original annualised premium.
11. What are the disadvantages of the Axis Max Life Online Savings Plan Plus?
- No Loan Facility: The policy does not offer a loan facility against the accumulated fund value.
- Limited Initial Liquidity: No liquidity is available during the first five policy years, restricting access to your money during this period.
- Inadequate Life Cover: The sum assured offered may be insufficient to meet your family’s financial protection needs.
- Charges Reduce Investment: Various charges are deducted before the premium is invested, thereby reducing the amount available for wealth creation.
- Limited Fund Diversification: Although the plan offers several fund options, many appear repetitive in terms of their underlying assets under management (AUM), raising questions about the actual diversification available.
12. Research Methodology of the Axis Max Life Online Savings Plan Plus
The primary objective of investing in the market is to generate attractive returns over the long term.
To evaluate the return potential of the Axis Max Life Online Savings Plan Plus, let us examine a case study presented in the policy brochure.
The following analysis, including Internal Rate of Return (IRR) calculations, will help us understand the plan’s effectiveness and compare it with other investment avenues.
Benefit Illustration – IRR Analysis of Axis Max Online Savings Plan Plus
Consider a 25-year-old female purchasing the Axis Max Life Online Savings Plan Plus with a sum assured of ₹12 Lakhs.
The policy has a term of 30 years, a premium-paying term of 10 years and an annualised premium of ₹1.20 Lakh. She opts for the Wealth Variant.
|
Female |
25 years |
| Sum Assured |
₹ 12,00,000 |
|
Policy Term |
30 years |
| Premium Paying Term |
10 years |
|
Annualised Premium |
₹ 1,20,000 |
On consistently paying all the premiums, she will receive the accumulated fund value as the maturity benefit.
The policy brochure illustrates two assumed investment return scenarios: 8% p.a. and 4% p.a. These rates are only illustrative, are not guaranteed and should not be considered the maximum or minimum possible returns.
|
|
At 4% p.a. | At 8% p.a. | |||
| Age | Year | Annualised premium / Maturity benefit | Death benefit | Annualised premium / Maturity benefit |
Death benefit |
|
25 |
1 | -1,20,000 | 12,00,000 | -1,20,000 | 12,00,000 |
| 26 | 2 | -1,20,000 | 12,00,000 | -1,20,000 |
12,00,000 |
|
27 |
3 | -1,20,000 | 12,00,000 | -1,20,000 | 12,00,000 |
| 28 | 4 | -1,20,000 | 12,00,000 | -1,20,000 |
12,00,000 |
|
29 |
5 | -1,20,000 | 12,00,000 | -1,20,000 | 12,00,000 |
| 30 | 6 | -1,20,000 | 12,00,000 | -1,20,000 |
12,00,000 |
|
31 |
7 | -1,20,000 | 12,00,000 | -1,20,000 | 12,00,000 |
| 32 | 8 | -1,20,000 | 12,00,000 | -1,20,000 |
12,00,000 |
|
33 |
9 | -1,20,000 | 12,00,000 | -1,20,000 | 12,00,000 |
| 34 | 10 | -1,20,000 | 12,00,000 | -1,20,000 |
12,00,000 |
|
35 |
11 | 0 | 12,00,000 | 0 | 12,00,000 |
| 36 | 12 | 0 | 12,00,000 | 0 |
12,00,000 |
|
37 |
13 | 0 | 12,00,000 | 0 | 12,00,000 |
| 38 | 14 | 0 | 12,00,000 | 0 |
12,00,000 |
|
39 |
15 | 0 | 12,00,000 | 0 | 12,00,000 |
| 40 | 16 | 0 | 12,00,000 | 0 |
12,00,000 |
|
41 |
17 | 0 | 12,00,000 | 0 | 12,00,000 |
| 42 | 18 | 0 | 12,00,000 | 0 |
12,00,000 |
|
43 |
19 | 0 | 12,00,000 | 0 | 12,00,000 |
| 44 | 20 | 0 | 12,00,000 | 0 |
12,00,000 |
|
45 |
21 | 0 | 12,00,000 | 0 | 12,00,000 |
| 46 | 22 | 0 | 12,00,000 | 0 |
12,00,000 |
|
47 |
23 | 0 | 12,00,000 | 0 | 12,00,000 |
| 48 | 24 | 0 | 12,00,000 | 0 |
12,00,000 |
|
49 |
25 | 0 | 12,00,000 | 0 | 12,00,000 |
| 50 | 26 | 0 | 12,00,000 | 0 |
12,00,000 |
|
51 |
27 | 0 | 12,00,000 | 0 | 12,00,000 |
| 52 | 28 | 0 | 12,00,000 | 0 |
12,00,000 |
|
53 |
29 | 0 | 12,00,000 | 0 | 12,00,000 |
| 54 | 30 | 0 | 12,00,000 | 0 |
12,00,000 |
|
55 |
23,10,872 | 59,75,949 |
|
||
|
|
IRR | 2.59% | 6.43% |
|
|
Under the 4% return scenario, the projected maturity fund value is ₹23.10 Lakhs, translating into an IRR of just 2.59% as per the Axis Max Life Online Savings Plan Plus maturity calculator.
Under the 8% return scenario, the fund value increases to ₹59.75 Lakhs, with an IRR of 6.43% as per the Axis Max Life Online Savings Plan Plus maturity calculator.
Our Assessment
The projected returns raise concerns about the plan’s ability to help you achieve long-term financial goals.
Even under the optimistic 8% illustration, the IRR is only 6.43%, which may not adequately compensate for inflation over a 30-year period.
Considering the long investment horizon, the accumulated corpus may fall short of meeting the inflated costs of your future goals.
The relatively low returns could therefore undermine your wealth-creation objectives, making the Axis Max Life Online Savings Plan Plus a less suitable choice for long-term financial planning.
13. Axis Max Life Online Savings Plan Plus Vs. Other Investments
The Axis Max Life Online Savings Plan Plus is a market-linked product, yet its illustrated returns are lower than those offered by conventional debt instruments.
This raises concerns about its suitability as a long-term investment. Let us compare the plan with alternative investment options using the same assumptions as in the earlier illustration.
This time, we will separate the insurance and investment components rather than combine them in a single product.
Axis Max Life Online Savings Plan Plus Vs. Pure-term + PPF/Equity Mutual Fund
A pure-term life insurance policy with a sum assured of ₹12 Lakhs costs an annual premium of just ₹7,600. The policy term is 30 years, with a premium-paying term of 10 years.
By setting aside the amount required for life insurance, you are left with ₹1,12,400 annually out of the original ₹1.20 Lakh premium for wealth creation.
|
Pure Term Life Insurance Policy |
|
|
Sum Assured |
₹ 12,00,000 |
| Policy Term |
30 years |
|
Premium Paying Term |
10 years |
| Annualised Premium |
₹ 7,600 |
|
Investment |
₹ 1,12,400 |
Depending on your risk appetite, you can invest this amount in debt or equity instruments.
For our comparison, we will consider the Public Provident Fund (PPF) as the debt investment option and an Equity Mutual Fund as the market-linked alternative.
|
|
Term Insurance + PPF |
Term insurance + Equity Mutual Fund |
|||
|
Age |
Year | Term Insurance premium + PPF | Death benefit | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 25 | 1 | -1,20,000 | 12,00,000 | -1,20,000 |
12,00,000 |
|
26 |
2 | -1,20,000 | 12,00,000 | -1,20,000 | 12,00,000 |
| 27 | 3 | -1,20,000 | 12,00,000 | -1,20,000 |
12,00,000 |
|
28 |
4 | -1,20,000 | 12,00,000 | -1,20,000 | 12,00,000 |
| 29 | 5 | -1,20,000 | 12,00,000 | -1,20,000 |
12,00,000 |
|
30 |
6 | -1,20,000 | 12,00,000 | -1,20,000 | 12,00,000 |
| 31 | 7 | -1,20,000 | 12,00,000 | -1,20,000 |
12,00,000 |
|
32 |
8 | -1,20,000 | 12,00,000 | -1,20,000 | 12,00,000 |
| 33 | 9 | -1,20,000 | 12,00,000 | -1,20,000 |
12,00,000 |
|
34 |
10 | -1,17,500 | 12,00,000 | -1,20,000 | 12,00,000 |
| 35 | 11 | -500 | 12,00,000 | 0 |
12,00,000 |
|
36 |
12 | -500 | 12,00,000 | 0 | 12,00,000 |
| 37 | 13 | -500 | 12,00,000 | 0 |
12,00,000 |
|
38 |
14 | -500 | 12,00,000 | 0 | 12,00,000 |
| 39 | 15 | -500 | 12,00,000 | 0 |
12,00,000 |
|
40 |
16 | 0 | 12,00,000 | 0 | 12,00,000 |
| 41 | 17 | 0 | 12,00,000 | 0 |
12,00,000 |
|
42 |
18 | 0 | 12,00,000 | 0 | 12,00,000 |
| 43 | 19 | 0 | 12,00,000 | 0 |
12,00,000 |
|
44 |
20 | 0 | 12,00,000 | 0 | 12,00,000 |
| 45 | 21 | 0 | 12,00,000 | 0 |
12,00,000 |
|
46 |
22 | 0 | 12,00,000 | 0 | 12,00,000 |
| 47 | 23 | 0 | 12,00,000 | 0 |
12,00,000 |
|
48 |
24 | 0 | 12,00,000 | 0 | 12,00,000 |
| 49 | 25 | 0 | 12,00,000 | 0 |
12,00,000 |
|
50 |
26 | 0 | 12,00,000 | 0 | 12,00,000 |
| 51 | 27 | 0 | 12,00,000 | 0 |
12,00,000 |
|
52 |
28 | 0 | 12,00,000 | 0 | 12,00,000 |
| 53 | 29 | 0 | 12,00,000 | 0 |
12,00,000 |
|
54 |
30 | 0 | 12,00,000 | 0 | 12,00,000 |
| 55 | 65,86,682 | 1,88,02,682 |
|
||
|
|
IRR | 6.83% | 11.19% |
|
|
1. Pure-Term Insurance + PPF
Since the PPF account requires a minimum annual investment of ₹500 to remain active, adjustments have been made to the contributions during the final years of the investment period to meet this requirement over its 15-year tenure.
The resulting maturity corpus is ₹65.86 Lakhs, translating into an IRR of 6.83%. Interestingly, this is higher than the 6.43% IRR under the 8% illustrated return scenario of the Axis Max Life Online Savings Plan Plus. In other words, a conventional debt instrument like PPF delivers better returns than this market-linked insurance product.
2. Pure-Term Insurance + Equity Mutual Fund
For investors with a higher risk appetite and a long investment horizon, an Equity Mutual Fund can be a suitable wealth-creation avenue.
The projected pre-tax maturity value of the investment is ₹2.13 Crores. After accounting for applicable capital gains tax, the post-tax corpus stands at ₹1.88 Crores, translating into a post-tax IRR of 11.19%.
| Equity Mutual Fund Tax Calculation | |
|
Maturity value after 30 years |
2,13,10,351 |
| Purchase price |
11,24,000 |
|
Long-Term Capital Gains |
2,01,86,351 |
| Exemption limit |
1,25,000 |
|
Taxable LTCG |
2,00,61,351 |
| Tax paid on LTCG |
25,07,669 |
|
Maturity value after tax |
1,88,02,682 |
This substantially higher corpus provides greater potential to meet your long-term financial goals.
More importantly, the post-tax return has the potential to outpace inflation and support long-term wealth creation.
The comparison clearly demonstrates the advantage of keeping insurance and investments separate.
A pure-term policy provides the required life cover at a relatively low cost, while the remaining amount can be invested independently in instruments suited to your risk appetite and financial goals.
Combining life insurance with market-linked investments, as in the Axis Max Life Online Savings Plan Plus, does not necessarily deliver an efficient outcome.
Instead of compromising on both protection and wealth creation, it is worth considering separate products for each purpose.
14. Final Verdict on Axis Max Life Online Savings Plan Plus
The Axis Max Life Online Savings Plan Plus is a conventional Unit-Linked Insurance Plan (ULIP) offering five different variants.
The death benefits differ depending on the variant selected.
Additional benefits, such as premium waiver and family income benefits, further increase the premium outgo.
On the investment front, the plan provides equity exposure, which may appeal to investors looking to build a substantial corpus for their long-term financial goals.
Given the important role of equity in long-term wealth creation, the product may initially seem attractive.
However, our analysis of the projected returns reveals that the plan falls short of expectations for a long-term investment.
Various charges reduce the returns over the policy term, while the sum assured may be inadequate to meet your family’s future financial needs and it also has a high
agent commission.
The combination of low returns and insufficient life cover makes the Axis Max Life Online Savings Plan Plus an unsuitable choice for your equity investment portfolio.
Your equity allocation deserves a more efficient investment avenue capable of generating better long-term returns.
Consider opting for a pure-term insurance policy to secure adequate life cover and build a separate investment portfolio based on your risk appetite, financial goals and investment horizon.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
If you need professional guidance, consult a qualified financial planner who can evaluate your requirements and develop a comprehensive financial plan tailored to your needs.
Leave a Comment