
 Listen to this article
Can the ABSLI Smart Wealth Pension Plan truly help you build a substantial retirement corpus, or could market risks and policy charges affect your financial future?
Does the ABSLI Smart Wealth Pension Plan offer the right combination of long-term wealth creation and retirement security, or are there better alternatives available?
Is the ABSLI Smart Wealth Pension Plan a smart retirement investment choice, or could alternative retirement strategies offer better returns, flexibility, and control over your savings?
In this article, we take a closer look at the plan, examining its key features, benefits and drawbacks, along with a detailed benefit illustration to evaluate its actual returns and suitability for retirement planning.
Table of Contents:
What is the ABSLI Smart Wealth Pension Plan?
What are the features of the ABSLI Smart Wealth Pension Plan?
Who is eligible for the ABSLI Smart Wealth Pension Plan?
What are the benefits of the ABSLI Smart Wealth Pension Plan?
What are the investment strategies and fund options of the ABSLI Smart Wealth Pension Plan?
What are the charges of the ABSLI Smart Wealth Pension Plan?
Grace Period, Discontinuance and Revival of the ABSLI Smart Wealth Pension Plan
Free Look Period for the ABSLI Smart Wealth Pension Plan
Surrendering the ABSLI Smart Wealth Pension Plan
What are the advantages of the ABSLI Smart Wealth Pension Plan?
What are the disadvantages of the ABSLI Smart Wealth Pension Plan?
Research Methodology of ABSLI Smart Wealth Pension Plan
Benefit Illustration – IRR Return Analysis of ABSLI Smart Wealth Pension Plan
ABSLI Smart Wealth Pension Plan Vs. Other Investments
ABSLI Smart Wealth Pension Plan Vs. Pure-term + PPF/Equity Mutual Fund
Final Verdict on the ABSLI Smart Wealth Pension Plan
What is the ABSLI Smart Wealth Pension Plan?
ABSLI Smart Wealth Pension Plan is a Unit-Linked Non-Participating Pension Plan. It builds long-term savings with the potential of market-linked growth to build a retirement corpus.
At retirement, the accumulated corpus can also be converted to create a regular income stream through an annuity plan to build a retirement income.
What are the features of the ABSLI Smart Wealth Pension Plan?
- Three Plan Options: Choose from Advantage, Prime and Elite options.
- Dedicated Retirement Corpus: Build a retirement fund with a choice of five investment funds and four investment strategies.
- Flexible Life Cover: Choose between Single Life and Joint Life options, with a Waiver of Premium benefit in case of the life assured’s death.
- Premium Allocation Benefits: Get up to 600% of Return of Premium Allocation Charges and additional Loyalty Additions.
- Special Benefit for Women: Higher benefits are offered for female lives.
- Tax-Free Maturity Withdrawal: Withdraw up to 60% of the fund value on maturity, subject to applicable tax provisions.
- Annuity Booster: Receive an additional annuity booster of up to 1%.
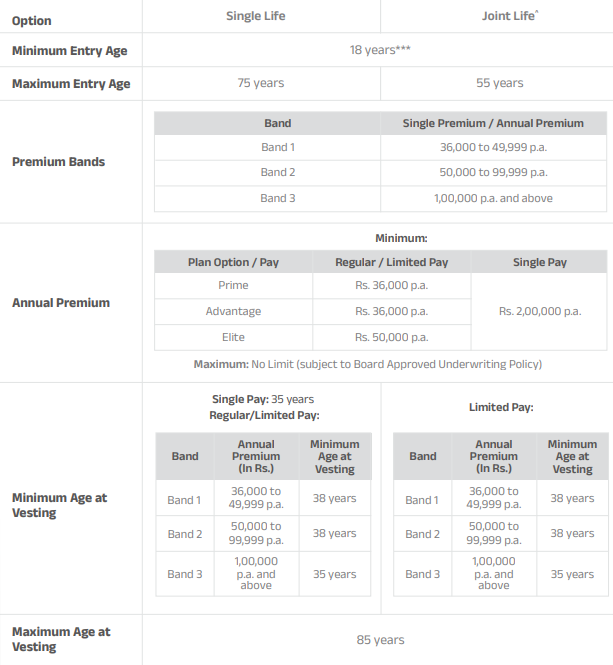
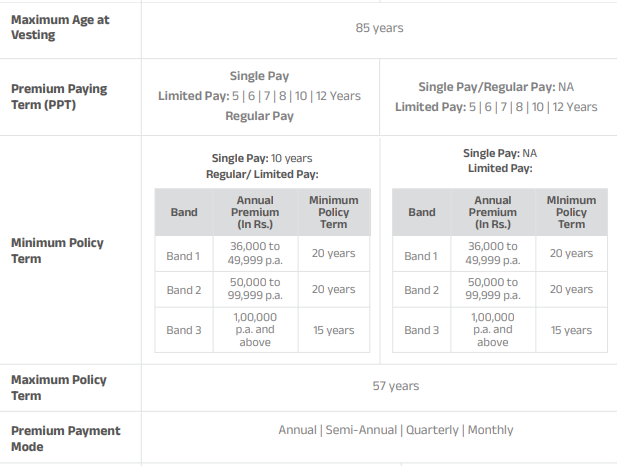
Who is eligible for the ABSLI Smart Wealth Pension Plan?
What are the benefits of the ABSLI Smart Wealth Pension Plan?
1. Vesting Benefit
Single Life
On survival of the Life Insured till the Vesting Date, Fund Value (including Top-up Fund Value) shall be payable, provided all the due premiums are paid, and the ABSLI Smart Wealth Pension Plan policy is in force.
Joint Life
On survival of at least one of the Lives Insured till the Vesting Date, Fund Value (including Top-up Fund Value) shall be payable, provided all the due premiums are paid, and the policy is in force.
Options to avail Vesting Benefit: On the Vesting Date, the Policyholder can opt for one of the following:
| 100% to purchase an annuity | Commute up to 60% and balance to purchase Annuity |
| To purchase an immediate annuity or deferred annuity from the insurer at the then prevailing annuity rate. | To commute/withdraw up to 60% of the entire Vesting Benefit and utilise the balance amount to purchase an immediate annuity or deferred annuity from the insurer at the then prevailing annuity rate. |
| You will also have an option to purchase an immediate annuity or deferred annuity from another insurer at the then prevailing annuity rate, by utilising not more than 50% of the entire proceeds of the policy net of commutation | You shall have an option to purchase an immediate annuity or deferred annuity from another insurer at the then prevailing annuity rate, by utilising not more than 50% of the proceeds of the policy net of commutation. |
2. Death Benefit
Single Life
On the death of the life assured during the ABSLI Smart Wealth Pension Plan policy term, provided all the due premiums have been paid, and the policy is in force, the nominee shall get the higher of:
- Fund Value (including Top-up Fund Value) as on the date of intimation of death; or
- 105% of Total Premiums Paid (including Top-up premium, if any)
The policy shall terminate on the date of intimation of death of the life assured.
Joint Life
On first death of either of the life assured:
On death during the policy term, provided all the due premiums are paid, and the policy is in force –
- The company will waive off all future due premiums after the date of first death of any of the lives assured
- Policy shall continue till the end of policy term or until the death of last survivor
- Loyalty addition, Return of Premium allocation charge and Annuity Booster will be applicable as and when due
On the death of the surviving life assured (subsequent death):
On death during the ABSLI Smart Wealth Pension Plan policy term, nominee shall get the higher of –
- Fund Value (including Top-up Fund Value) as on date of intimation of death
- 105% of Total Premiums Paid, including top-up premiums, if any and policy terminates.
On death of both the lives assured together:
On death during the ABSLI Smart Wealth Pension Plan policy term, provided all the due premiums are paid, and the policy is in force, the nominee shall get the higher of –
- Fund Value (including Top-up Fund Value) as on the date of intimation of death
- 105% of Total Premiums Paid including top-up premiums, if any and policy terminates.
Options to avail Death Benefit:
The nominee shall have the following options:
- Withdraw the entire proceeds as a lump sum
- To utilise the entire proceeds or part thereof for purchasing an annuity (immediate or deferred) from us at the then prevailing rate.
Note: In case proceeds of the policy (net of commutation) on vesting are not sufficient to purchase the minimum annuity as allowed by the Authority, as amended from time to time, the nominee will be paid the proceeds of the policy as a lump sum
What are the investment strategies and fund options of the ABSLI Smart Wealth Pension Plan?
Under the ABSLI Smart Wealth Pension Plan, you can choose to invest your premiums in one of the four investment strategies.
The Annualised Premium/Single Premium (net of premium allocation charge) will be allocated to the Investment Option selected.
A. Self-Managed Option:
You have the option of choosing any of the 5 funds based on your needs and risk appetite. If you wish to diversify risk, you can choose to allocate premium in varying proportions amongst the 5 segregated funds.
Our only requirement is that the percentage allocated to any segregated fund should be in increments of 5%, ranging from 5% to 100%. The total allocation across all funds must be 100%.
| S.no | Fund | Risk Profile | Asset Allocation | ||
| Debt Instruments | Money Market & Cash | Equities & Equity Related Securities | |||
| 1 | Pension Maximiser | High | 0-20% | 0-20% | 80-100% |
| 2 | Pension Income Advantage | Very Low | 60-100% | 0-40% | 0% |
| 3 | Pension Nourish | Very Low | 90-100% | 0% | 0-10% |
| 4 | Pension Growth | Very Low | 80-90% | 0% | 10-20% |
| 5 | Pension Enrich | Low | 65-80% | 0% | 20-35% |
B. Smart Investment Option:
Under the Smart Investment Option, the portfolio will be structured as per vesting date and risk profile (Conservative, Moderate, Aggressive).
We will invest the Annualised Premiums/Single Premium (net of premium allocation charge) between the two segregated funds – Pension Maximiser Fund (equity fund) and Pension Income Advantage (debt fund) in a predetermined proportion based on the outstanding vesting term and risk profile (Conservative, Moderate, Aggressive).
Over time, the allocation is managed such that it will automatically switch from riskier assets to safer assets progressively as the plan approaches the vesting date.
The proportion invested in Pension Maximiser Fund (equity fund) and Pension Income Advantage (debt fund) will be according to the schedule given
| Outstanding term to Vesting | Risk Profile and Exposure in % to funds | |||||
| Aggressive | Moderate | Conservative | ||||
| Pension Maximiser Fund | Pension Income Advantage Fund | Pension Maximiser Fund | Pension Income Advantage Fund | Pension Maximiser Fund | Pension Income Advantage Fund | |
| 21 & above | 90% | 10% | 70% | 30% | 50% | 50% |
| 16 to 20 | 80% | 20% | 60% | 40% | 40% | 60% |
| 8 to 15 | 65% | 35% | 50% | 50% | 30% | 70% |
| 4 to 7 | 50% | 50% | 25% | 75% | 15% | 85% |
| 0 to 3 | 20% | 80% | 10% | 90% | 5% | 95% |
C. Life-Cycle Investment Option:
Under the Life-Cycle Option, the portfolio will be structured as per your age and risk profile – all you need is to decide your risk profile – Conservative, Moderate or Aggressive.
The company will automatically shift investments from riskier assets to safer assets progressively as per your age.
We will invest Annualised Premiums/Single Premium and top-up premium (net of allocation charge) between the two segregated funds, Pension Maximiser Fund (Equity Fund) and Pension Income Advantage Fund (Debt Fund), in a predetermined proportion based on the selected risk profile and age when the premium is invested.
The percentage allocation to the Pension Maximiser Fund according to age and risk profile is as given below:
| Age Group | Risk Profile | ||
| Aggressive | Moderate | Conservative | |
| 18-30 | 90% | 70% | 50% |
| 31-40 | 80% | 60% | 50% |
| 41-50 | 70% | 50% | 30% |
| 51-60 | 55% | 35% | 15% |
| 61-70 | 40% | 20% | 0% |
| 71+ | 25% | 5% | 0% |
D. Return Optimiser Investment Option:
Under this option, all your Annualised Premiums/Single Premium and top-up premium (net of premium allocation charges) are invested in the Pension Maximiser Fund, and it will be tracked every day for each policyholder for a predetermined upside movement of 10% or more over the net invested amount.
In the situation where your gain from the Pension Maximiser Fund reaches 10% or more of the net invested amount, the amount equal to the appreciation will be transferred to the Pension Income Advantage Fund at the prevailing unit price.
This ensures that your gains are protected from any future market volatility.
What are the charges of the ABSLI Smart Wealth Pension Plan?
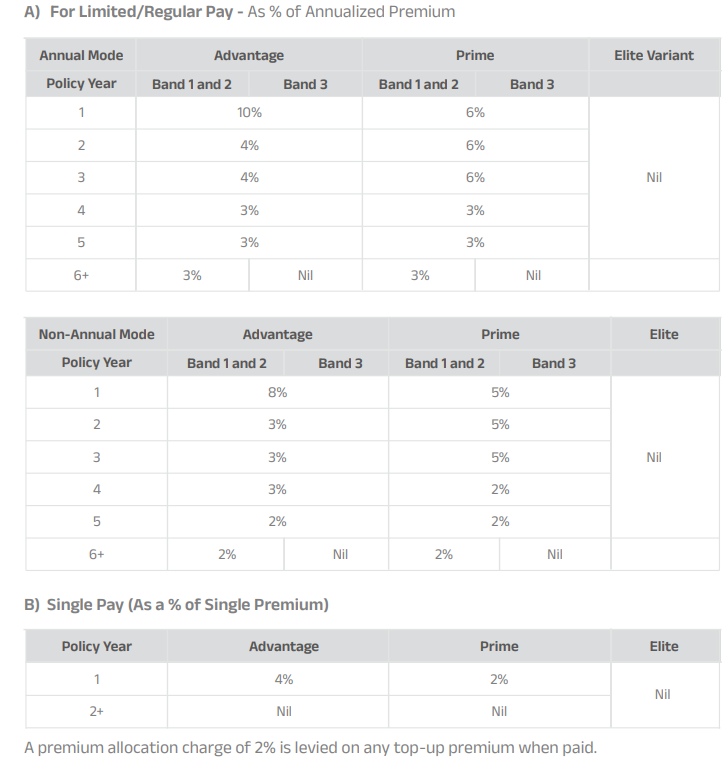
i. Premium Allocation Charge
A certain percentage of each premium will be allocated to purchase units at the prevailing unit price, and the balance shall be taken as Premium Allocation Charge.
ii. Fund Management Charge
| Fund | Fund Management Charge (p.a.) |
| Pension Maximiser | 1.35% |
| Pension Income Advantage | 1.00% |
| Pension Nourish | 1.00% |
| Pension Growth | 1.00% |
| Pension Enrich | 1.25% |
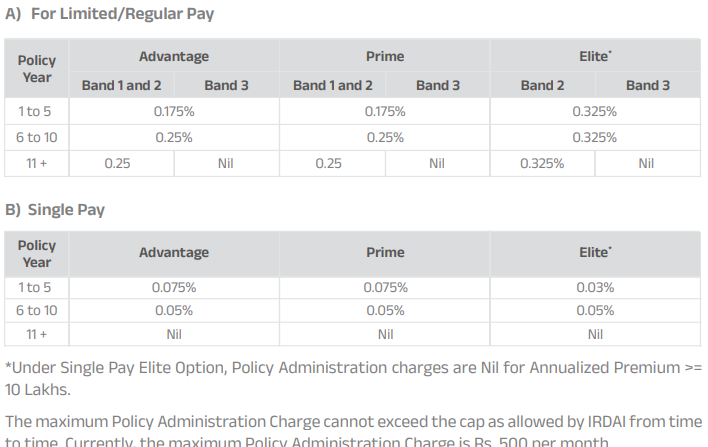
iii. Policy Administration Charge
The policy administration charge will be deducted at each monthly anniversary by cancellation of units proportionately from each segregated fund you have at that time at the prevailing unit price.
The charge as per premium band is shown below:
iv. Mortality Charge
Mortality charge is based on the Sum at Risk and is deducted from the Fund Value on each Monthly Processing Date by redemption of Units in the Funds.
Mortality Charge is guaranteed throughout the ABSLI Smart Wealth Pension Plan policy term.
Mortality charge = Sum at Risk (SAR) multiplied by the applicable mortality rate for the month, based on the attained age of the life assured
| Attained Age | Age 25 | Age 35 | Age 45 | Age 55 | Age 65 |
| Male | 0.545 | 0.703 | 1.509 | 4.395 | 9.32 |
| Female | 0.548 | 0.61 | 1.152 | 3.247 | 7.506 |
v. Discontinuance Charge
Policy Discontinuance Charges are deducted from the Fund Value only in case you discontinue the Premium payment during the Policy during the Lock-in Period as per the Policy Discontinuance provision.
vi. Miscellaneous Charges
The current charge is ₹ 50 per request for change in premium payment frequency, change in Premium Payment Term and postponement of Vesting Date.
Inference from charges: These charges add to the overall cost of the investment and are generally not applicable to other market-linked investment options. Over the long term, they can eat into the fund value and significantly reduce your overall returns.
Grace Period, Discontinuance and Revival of the ABSLI Smart Wealth Pension Plan
For Regular/Limited Pay Policies
Grace Period
You will be given a Grace Period of 30 days (15 days in case the premium paying mode is monthly) to make the payment of due Instalment Premium(s), during which time all the benefits will continue inclusive of the risk cover.
Discontinuance
Discontinuance of the policy during the first five (5) policy years: the Fund Value after deducting the applicable discontinuance charges shall be credited to the Pension Discontinued Policy Fund and the risk cover shall cease.
The proceeds of the Pension Discontinued Policy Fund shall be paid to you at the end of the revival period or lock-in period, whichever is later.
Discontinuance of the policy after completion of the first five (5) policy years: the policy shall be converted into a reduced paid-up policy.
The paid-up death benefit shall be 105% of total premiums paid. At the end of the revival period, the proceeds of the policy fund shall be paid to you, and the policy shall terminate.
Revival
You can revive the policy within the revival period of three years
Free Look Period for the ABSLI Smart Wealth Pension Plan
You shall have a period of 30 days from the date of receipt of the Policy to review the terms and conditions of this ABSLI Smart Wealth Pension Plan Policy.
In case you disagree with any of the terms and conditions, you shall have the right to return the Policy by providing written notice of cancellation, stating the reasons for such cancellation, together with the original Policy Document (where such Policy is issued in physical form).
Surrendering the ABSLI Smart Wealth Pension Plan
Single-pay policies
You have an option to surrender at any time during the lock-in period. Upon receipt of a request for surrender, the Fund Value, after deducting the applicable discontinuance charges, shall be credited to the Pension Discontinued Policy Fund
The ABSLI Smart Wealth Pension Plan policy shall continue to be invested in the Pension Discontinued Policy Fund, and the proceeds from the Pension Discontinued Policy Fund shall be paid at the end of the lock-in period.
Only the Fund Management Charge can be deducted from this fund during this period. Further, no risk cover shall be available on such policy during the discontinuance period.
Surrender of the policy after completion of first 5 policy years: You have an option to surrender the policy any time. Upon receipt of request for surrender, the Fund Value as on date of surrender shall be payable
For Regular/Limited Pay Policies
Surrender of the policy during the first 5 policy years: You have an option to surrender any time during the lock-in period. Upon receipt of a request for surrender, the Fund Value, after deducting the applicable discontinuance charges, shall be credited to the Pension Discontinued Policy Fund.
The policy shall continue to be invested in the Pension Discontinued Policy Fund, and the proceeds from the Pension Discontinued Policy Fund shall be paid at the end of the lock-in period.
Surrender of the policy after completion of the first 5 policy years: the Policyholder has an option to surrender the policy anytime, and the proceeds of the policy fund shall be payable
Options to avail Surrender Benefit:
You shall have the following options on surrender of the Policy.
To utilise the entire proceeds of the Policy to purchase an immediate annuity or deferred annuity from Us at the prevailing annuity rates.
You shall also have the option to purchase an immediate annuity or deferred annuity from another insurer at the prevailing annuity rates, by utilising not more than 50% of the proceeds of the Policy, net of commutation.
To commute/withdraw up to 60% of the proceeds of the Policy and utilise the balance amount to purchase an immediate annuity or deferred annuity from Us at the prevailing annuity rates.
You shall also have the option to purchase an immediate annuity or deferred annuity from another insurer at the prevailing annuity rates, by utilising not more than 50% of the proceeds of the Policy, net of commutation.
What are the advantages of the ABSLI Smart Wealth Pension Plan?
- Vesting Date Extension: Option to postpone the vesting date, subject to age conditions (below 60 years).
- Return of Charges: Premium allocation charges deducted up to the extension year are added back to the policy fund.
- Loyalty Additions: Additional units are allocated from the end of the 6th policy year until maturity.
- Fund Flexibility: Premium redirection, fund switching and investment option changes are permitted.
- Risk Profile Switching: Available under Smart Investment and Life Cycle Investment options.
- Partial Withdrawals: Allowed after completion of five policy years.
- Top-Up Premiums: Option to invest additional amounts during the policy term.
- Premium Flexibility: Change the Premium Payment Term and payment frequency, subject to conditions.
- Settlement Option: Nominees can receive the death benefit in instalments.
What are the disadvantages of the ABSLI Smart Wealth Pension Plan?
- The plan offers only the vested benefit at the end of the policy term.
- The sum assured is relatively low and may not provide adequate life cover.
- No loan facility is available.
- A 5-year lock-in applies to surrender and partial withdrawals during the accumulation phase.
Research Methodology of ABSLI Smart Wealth Pension Plan
The ABSLI Smart Wealth Pension Plan invests in market-linked funds to build a retirement corpus.
However, the accumulated corpus cannot be freely accessed at vesting and must be used, partially or fully, to purchase an annuity. Hence, evaluating the actual return potential is important.
Let’s calculate the Internal Rate of Return (IRR) using the benefit illustration in the policy brochure.
Benefit Illustration – IRR Return Analysis of ABSLI Smart Wealth Pension Plan
Illustration: A 40-year-old male invests ₹1 lakh annually for 10 years under a 20-year policy term.
| Male | 40 years |
| Sum Assured | ₹ 10,50,000 |
| Policy Term | 20 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 1,00,000 |
The brochure provides two return scenarios. Assuming a fund growth rate of 4% p.a., the vesting benefit amounts to ₹15.14 lakh, translating into an IRR of 2.70% as per the ABSLI Smart Wealth Pension Plan maturity calculator.
At an assumed growth rate of 8% p.a., the vesting benefit increases to ₹27.37 lakh, resulting in an IRR of 6.60% as per the ABSLI Smart Wealth Pension Plan maturity calculator.
| At 4% p.a. | At 8% p.a. | ||||
| Age | Year | Annualised premium / Maturity benefit | Death benefit | Annualised premium / Maturity benefit | Death benefit |
| 40 | 1 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 41 | 2 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 42 | 3 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 43 | 4 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 44 | 5 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 45 | 6 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 46 | 7 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 47 | 8 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 48 | 9 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 49 | 10 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 50 | 11 | 0 | 10,50,000 | 0 | 10,50,000 |
| 51 | 12 | 0 | 10,50,000 | 0 | 10,50,000 |
| 52 | 13 | 0 | 10,50,000 | 0 | 10,50,000 |
| 53 | 14 | 0 | 10,50,000 | 0 | 10,50,000 |
| 54 | 15 | 0 | 10,50,000 | 0 | 10,50,000 |
| 55 | 16 | 0 | 10,50,000 | 0 | 10,50,000 |
| 56 | 17 | 0 | 10,50,000 | 0 | 10,50,000 |
| 57 | 18 | 0 | 10,50,000 | 0 | 10,50,000 |
| 58 | 19 | 0 | 10,50,000 | 0 | 10,50,000 |
| 59 | 20 | 0 | 10,50,000 | 0 | 10,50,000 |
| 60 | 15,14,714 | 27,37,338 | |||
| IRR | 2.70% | 6.60% | |||
These returns are not guaranteed and depend on market performance and other factors. Further, the IRRs are indicative of the accumulation phase only.
Since the accumulated corpus must be used to purchase an annuity, the actual retirement income will depend on the annuity rates prevailing at vesting.
The restricted access to the accumulated corpus and uncertainty over future annuity rates reduce the plan’s flexibility.
Compared with more transparent and flexible retirement investment options, the ABSLI Smart Wealth Pension Plan appears less attractive.
ABSLI Smart Wealth Pension Plan Vs. Other Investments
The ABSLI Smart Wealth Pension Plan restricts how you can utilise your accumulated retirement corpus.
An alternative approach is to separate insurance and investments, giving you greater flexibility and control over your money while potentially generating better returns.
ABSLI Smart Wealth Pension Plan Vs. Pure-term + PPF/Equity Mutual Fund
Let’s consider the same example: A 40-year-old individual invests ₹1 lakh annually for 10 years, with a 20-year investment horizon.
Instead of investing the entire amount in a pension plan, one can purchase a pure-term insurance policy with a sum assured of ₹10.5 lakh.
The annual premium works out to ₹11,300 for a 20-year policy term and a 10-year premium payment period. The remaining ₹88,700 can be invested according to the individual’s risk appetite.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 10,50,000 |
| Policy Term | 20 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 11,300 |
| Investment | ₹ 88,700 |
Risk-averse investors can consider debt instruments such as PPF, while investors willing to take higher risks may opt for equity mutual funds.
| Term Insurance + PPF | Term insurance + Equity Mutual Fund | ||||
| Age | Year | Term Insurance premium + PPF | Death benefit | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 40 | 1 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 41 | 2 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 42 | 3 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 43 | 4 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 44 | 5 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 45 | 6 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 46 | 7 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 47 | 8 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 48 | 9 | -1,00,000 | 10,50,000 | -1,00,000 | 10,50,000 |
| 49 | 10 | -97,500 | 10,50,000 | -1,00,000 | 10,50,000 |
| 50 | 11 | -500 | 10,50,000 | 0 | 10,50,000 |
| 51 | 12 | -500 | 10,50,000 | 0 | 10,50,000 |
| 52 | 13 | -500 | 10,50,000 | 0 | 10,50,000 |
| 53 | 14 | -500 | 10,50,000 | 0 | 10,50,000 |
| 54 | 15 | -500 | 10,50,000 | 0 | 10,50,000 |
| 55 | 16 | 0 | 10,50,000 | 0 | 10,50,000 |
| 56 | 17 | 0 | 10,50,000 | 0 | 10,50,000 |
| 57 | 18 | 0 | 10,50,000 | 0 | 10,50,000 |
| 58 | 19 | 0 | 10,50,000 | 0 | 10,50,000 |
| 59 | 20 | 0 | 10,50,000 | 0 | 10,50,000 |
| 60 | 26,17,553 | 48,64,289 | |||
| IRR | 6.30% | 10.46% | |||
With minor adjustments to accommodate PPF’s 15-year contribution period, the investment grows to ₹26.17 lakh over 20 years, delivering an IRR of 6.30%.
This is comparable to the projected corpus under the ABSLI Smart Wealth Pension Plan at 8% assumed fund growth. However, the key advantage is that the entire maturity proceeds are available for withdrawal without any mandatory annuity purchase.
Equity mutual funds offer higher growth potential. At the assumed rate of return, the corpus grows to ₹54.14 lakh over 20 years. After accounting for long-term capital gains tax, the post-tax value stands at ₹48.64 lakh, translating into a post-tax IRR of 10.46%.
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 20 years | 54,14,616 |
| Purchase price | 8,87,000 |
| Long-Term Capital Gains | 45,27,616 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 44,02,616 |
| Tax paid on LTCG | 5,50,327 |
| Maturity value after tax | 48,64,289 |
Separating insurance and investments offers greater flexibility and potentially better returns. Unlike the ABSLI Smart Wealth Pension Plan, this approach does not impose mandatory annuity purchase requirements.
You retain control over your accumulated wealth and can decide how and when to utilise it during retirement.
This makes a combination of pure-term insurance and goal-based investments a more flexible alternative for retirement planning.
Final Verdict on the ABSLI Smart Wealth Pension Plan
The ABSLI Smart Wealth Pension Plan offers three variants, with differences mainly in their charges and the corresponding return of charges. Beyond these differences, there is little distinction between the options.
The plan allows you to invest in market-linked funds with the objective of building a retirement corpus. However, the accumulated corpus is not entirely accessible at maturity.
A portion must be used to purchase an annuity, and the resulting retirement income depends on the annuity rates prevailing at that time.
While the plan facilitates wealth accumulation during your working years, it does not adequately address the distribution phase – generating a steady income during retirement. More importantly, the annuity product and the income it will generate are not guaranteed under the plan.
This creates uncertainty about whether the eventual payouts will be sufficient to meet rising living expenses and combat inflation and it also has a high agent commission.
A more flexible approach is to build your retirement corpus independently through diversified investments across equity, debt and hybrid instruments.
You can then structure your portfolio to generate regular retirement income, with periodic rebalancing to manage market risks and account for inflation. This approach gives you greater control over your investments and withdrawals.
Starting early is one of the most important aspects of retirement planning. The power of compounding allows your investments to grow over time, making it easier to build a substantial retirement corpus.
A well-structured investment strategy, supported by regular reviews, can go a long way towards achieving financial independence during retirement.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
For personalised guidance on estimating your retirement needs and selecting suitable investments, consider consulting a Certified Financial Planner (CFP).
Leave a Comment