


 Listen to this article
Can the Bajaj Life Supreme – Advantage Plan truly help you build long-term financial security, or do its benefits come with important trade-offs?
Does the Bajaj Life Supreme – Advantage Plan offer the right balance between life protection and savings, or are there better alternatives available?
Is the Bajaj Life Supreme – Advantage Plan a smart choice for achieving your financial goals, or could its structure limit your wealth-creation potential?
In this article, let us examine the plan in detail and assess whether combining protection and investment is the right approach to financial planning.
What are the plan options in the Bajaj Life Supreme?
Bajaj Life Supreme is available in nine different variants, each designed with different features and benefits:
- Advantage
- Builder
- Classic
- Diamond
- Elite
- Fortune
- Gold
- Horizon
- Inspire
This article focuses on the Bajaj Life Supreme – Advantage variant. The plan’s features, benefits, costs, and potential returns will be examined to assess whether it offers a suitable combination of insurance protection and investment for long-term financial planning.
Table of Contents:
What is the Bajaj Life Supreme – Advantage?
What are the features of the Bajaj Life Supreme – Advantage?
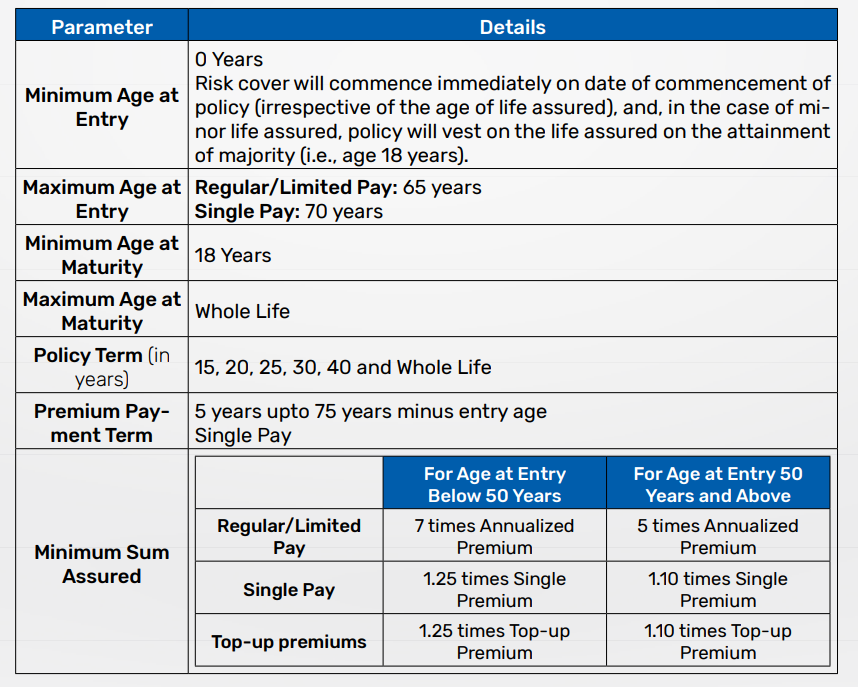
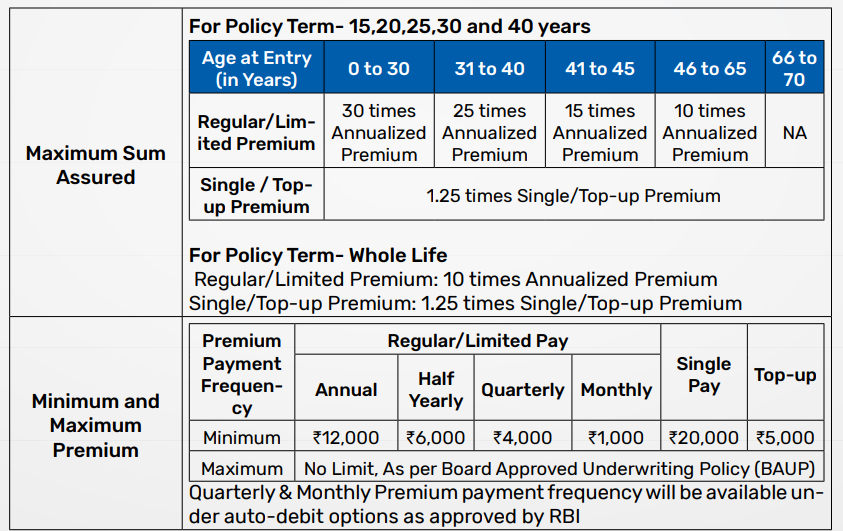
Who is eligible for the Bajaj Life Supreme – Advantage?
What are the benefits of the Bajaj Life Supreme – Advantage?
What are the Investment Strategies and Fund Options of the Bajaj Life Supreme – Advantage?
What are the charges of the Bajaj Life Supreme – Advantage?
Grace Period, Discontinuance and Revival of the Bajaj Life Supreme – Advantage
Free Look Period for the Bajaj Life Supreme – Advantage
Surrendering the Bajaj Life Supreme – Advantage
What are the advantages of the Bajaj Life Supreme – Advantage?
What are the disadvantages of the Bajaj Life Supreme – Advantage?
Research Methodology of Bajaj Life Supreme – Advantage
Benefit Illustration – IRR Analysis of Bajaj Life Supreme – Advantage
Bajaj Life Supreme – Advantage Vs. Other Investments
Bajaj Life Supreme – Advantage Vs. Pure-Term + Equity Mutual Fund
Final Verdict on Bajaj Life Supreme – Advantage
What is the Bajaj Life Supreme – Advantage?
Bajaj Life Supreme – Advantage is a Unit Linked Non-Participating Individual Life Savings Insurance Plan. It blends the power of life cover with market-linked returns.
This ULIP allows you to plan for any of your long-term goals. This all-in-one plan helps you to grow your wealth while financially securing your loved ones.
What are the features of the Bajaj Life Supreme – Advantage?
- Market-Linked Investment: Provides life insurance protection along with market-linked investment opportunities across a range of funds.
- Guaranteed Wealth Booster: Offers a Guaranteed Wealth Booster at the end of the 15th policy year, which is added to the policy corpus.
- Return of Mortality Charges: From the end of the 15th policy year and every five years thereafter, the mortality charges deducted during the specified period are added back to the corpus, subject to the policy terms.
- Loyalty Additions: From the end of the 16th policy year, Loyalty Additions are provided as a reward for continuing the policy, subject to applicable conditions.
- Systematic Partial Withdrawal: Provides liquidity from the policy after five policy years through Systematic Partial Withdrawals, subject to the applicable terms and limits.
- Fund Switching Flexibility: Allows switching between available funds without an additional switching charge, enabling policyholders to adjust their investment allocation based on their investment strategy and market conditions.
Who is eligible for the Bajaj Life Supreme – Advantage?
What are the benefits of the Bajaj Life Supreme – Advantage?
1. Maturity Benefit
Fund Value shall be payable to you on the Maturity Date, provided the life assured (person whose life is covered under the Bajaj Life Supreme – Advantage Plan policy) is alive.
You will have an option to receive the Maturity Benefit as a lump sum or as a systematic payout for a maximum of five years under the Settlement Option.
2. Death Benefit
In case of unfortunate death of the Life Assured during the Bajaj Life Supreme – Advantage Plan Policy term, provided all due premiums have been paid, and the policy is in force, the Death Benefit payable will be the higher of:
- Prevailing Sum Assured, including top-up sum assured, if any
- Fund Value as available on date of intimation of death
- Guaranteed Death Benefit i.e.105% of Total Premiums Paid till the date of death, including top-up premium
The policy will terminate on the date of intimation of death of the life assured. Benefits available under the Plan
3. Additions to the Fund
Guaranteed Wealth Booster
Premium Allocation Charges deducted during the Bajaj Life Supreme – Advantage Plan policy term are accumulated at a guaranteed rate of 7% per year (compounded annually) and will be added to your fund value at the end of the 15th policy year.
Loyalty Additions
At the end of every year from the 16th policy year till the end of the policy term, additional units will be added to your fund value as Loyalty Additions
Return of Mortality Charge (ROMC)
Life cover charges deducted during the policy term shall be added back to your fund value
What are the Investment Strategies and Fund Options of the Bajaj Life Supreme – Advantage?
A. Investor-selectable Portfolio Strategy:
If you want to allocate your Premiums based on your personal choice and decision, you can opt for this Investment Strategy and choose from among the 21 Funds below to suit your investment needs.
| Asset Allocation | |||||
| S no | Fund Name | Equity | Debt | Money Market | Risk profile |
| 1 | Nifty 500 Low Volatility 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 2 | Opportunities Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 3 | BSE 500 Quality 50 Index Fund3 | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 4 | BSE 500 Dividend Leaders 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 5 | India Consumption Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 6 | Pure Stock Innovation | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 7 | BSE 500 Enhanced Value 50 Index Fund3 | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 8 | Equity Growth Fund II | Not less than 60% | 0% – 40% | 0% – 40% | Very High |
| 9 | Accelerator Mid-Cap Fund II | Not less than 60% (at least 50% in Mid cap) | 0% – 40% | 0% – 40% | Very High |
| 10 | Pure Stock Fund | Not less than 60% | 0% – 40% | 0% – 40% | Very High |
| 11 | Pure Stock Fund II | Not less than 75% | — | 0% -25% | Very High |
| 12 | Flexi Cap Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 13 | Sustainable Equity Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 14 | Small Cap Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 15 | Midcap Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 16 | SmallCap Quality Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 17 | Nifty Alpha 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 18 | Nifty 200 Alpha 30 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 19 | Nifty 200 Momentum 30 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 20 | Nifty 500 Multicap Momentum Quality 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 21 | Focused 25 Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 22 | Nifty 500 Multifactor 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 23 | Asset Allocation Fund II | 40% – 90% | 0% – 60% | 0% – 50% | High |
| 24 | Blue-chip Equity Fund | Not less than 60% | 0% – 40% | 0% – 40% | High |
| 25 | Dynamic Asset Allocation Fund | 10% 90% | 10% 90% | 0% – 80% | High |
| 26 | Bond Fund | — | 40% – 100% | 0% – 60% | Moderate |
| 27 | Individual Short-Term Debt Fund | — | 40% – 100% | 0% – 60% | Moderate |
| 28 | Debt Plus Fund | Not less than 80% | 0%-20% | 0%-20% | Moderate |
| 29 | Liquid Fund | — | — | 100% | Low |
B. Wheel of Life Portfolio Strategy – II:
In this Portfolio Strategy, at the commencement of the Bajaj Allianz Long-Life Goal III Plan Policy, the Regular/Limited Premium and the Top-up Premium, if any, would be allocated in the Funds mentioned (namely Equity Growth Fund II, Accelerator Mid-Cap Fund II, Bond Fund & Liquid Fund) in the proportion as mentioned in the table below, depending on the outstanding years to maturity.
| Proportion in Following Funds | |||||
| Years to Maturity | Equity Growth Fund II | Accelerator Mid-Cap Fund II | Bond Fund | Liquid Fund | Total |
| 10 & above | 40% | 45% | 15% | 0% | 100% |
| 9 | 35% | 50% | 15% | 0% | 100% |
| 8 | 30% | 55% | 15% | 0% | 100% |
| 7 | 25% | 60% | 15% | 0% | 100% |
| 6 | 25% | 60% | 15% | 0% | 100% |
| 5 | 20% | 65% | 15% | 0% | 100% |
| 4 | 20% | 55% | 15% | 10% | 100% |
| 3 | 20% | 50% | 15% | 15% | 100% |
| 2 | 10% | 30% | 30% | 30% | 100% |
| 1 | 0% | 0% | 35% | 65% | 100% |
C. Trigger-Based Portfolio Strategy:
Under this Portfolio Strategy, Regular/Limited Premiums and Top-up Premiums, if any, will be allocated between two Funds, Equity Growth Fund II (an equity-oriented Fund) and Bond Fund (a debt-oriented Fund), in a 75%: 25% proportion.
The Fund value proportions may subsequently get altered due to market movements.
Any appreciation over three times the value of units is considered a gain and is switched to the Liquid Fund.
Later, it will be switched to the Equity Growth Fund II and the Bond Fund such that, after the transfer, the ratio of the value of units in the Equity Growth Fund II to that in the Bond Fund is restored to 75%:25%.
D. Auto Transfer Portfolio Strategy:
This strategy helps you to invest your money systematically by automatically transferring your money every month, from a low-risk Fund to the Fund(s) of your choice.
In this Portfolio Strategy, your Premium will be allocated to the Bond Fund and/or Liquid Fund, as specified by you.
At the start of each monthly anniversary of the Bajaj Allianz Long-Life Goal III Plan Policy, a proportion (as mentioned below) of the Fund value in the Bond Fund and/or Liquid Fund as on that date will be switched to the other Fund/s (available in the plan) as specified by you.
The proportion of Fund value = 1/ Outstanding no. of months till the next premium due date.
E. Capital Preservation – Orientation Strategy
You can opt for this strategy at the inception of the Policy if the Bajaj Life Supreme – Advantage Plan Policy term is at least 10 years, and the minimum difference between the Policy term and Premium payment term is at least 5 years.
The objective of the strategy is to optimise risk and return by investing across five predetermined Funds, which are a mix of very high to low-risk Funds, in such a way that the monies invested over the years, along with the accumulated returns, are subjected to lesser market volatility in the years closer to maturity.
At each policy anniversary, the Company will reallocate the Fund Value among various funds in the proportion based on the table below, depending on the outstanding years to maturity.
| Proportion in the Following Funds | ||||||
| Years to Maturity | Equity Growth Fund II | Accelerator Mid-Cap Fund II | Pure-Stock Fund II | Bond Fund | Liquid Fund | Total |
| 10 & above | 40% | 15% | 15% | 30% | 0% | 100% |
| 9 | 35% | 15% | 15% | 35% | 0% | 100% |
| 8 | 30% | 15% | 15% | 40% | 0% | 100% |
| 7 | 30% | 15% | 15% | 40% | 0% | 100% |
| 6 | 30% | 10% | 15% | 45% | 0% | 100% |
| 5 | 25% | 10% | 15% | 40% | 10% | 100% |
| 4 | 20% | 5% | 10% | 40% | 25% | 100% |
| 3 | 15% | 0% | 5% | 40% | 40% | 100% |
| 2 | 0% | 0% | 0% | 40% | 60% | 100% |
| 1 | 0% | 0% | 0% | 0% | 100% | 100% |
What are the charges of the Bajaj Life Supreme – Advantage?
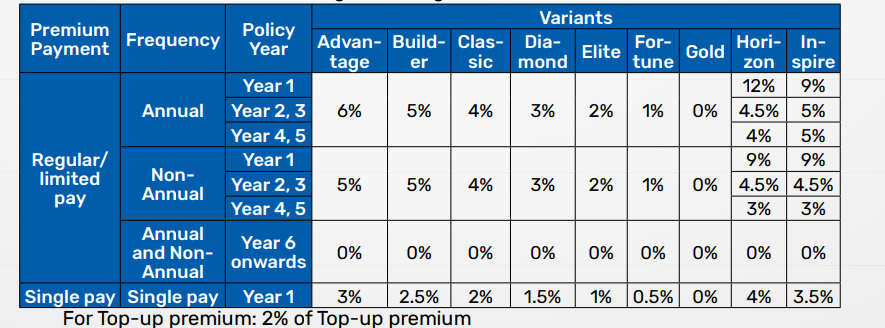
i. Premium Allocation Charge
A certain percentage of each premium paid by you will be deducted as Premium Allocation Charge, and the remaining amount will be invested at the prevailing unit price.
ii. Policy Administration Charge
| Mode | As % of Annualized/Single Premium | ||
| 1st to 5th Year | 6th Year to 20th Year | 21st Year onwards | |
| Regular/Limited Pay | 0.09% | 0.20% | Nil |
| Single Pay | 0.05% | Nil | |
iii. Fund Management Charge
| Fund | Fund Management Charge per annum |
| Nifty 500 Low Volatility 50 Index Fund | 1.35% |
| Opportunities Fund | 1.35% |
| BSE 500 Quality 50 Index Fund | 1.35% |
| BSE 500 Dividend Leaders 50 Index Fund | 1.35% |
| India Consumption Fund | 1.35% |
| Pure Stock Innovation Fund | 1.35% |
| BSE 500 Enhanced Value 50 Index Fund | 1.35% |
| Equity Growth Fund II | 1.35% |
| Accelerator Mid Cap Fund II | 1.35% |
| Pure Stock Fund | 1.35% |
| Flexi Cap Fund | 1.35% |
| Sustainable Equity Fund | 1.35% |
| Dynamic Asset Allocation Fund | 1.35% |
| Small Cap Fund | 1.35% |
| Midcap Index Fund | 1.35% |
| SmallCap Quality Index Fund | 1.35% |
| Nifty Alpha 50 Index Fund | 1.35% |
| Nifty 200 Alpha 30 Index Fund | 1.35% |
| Nifty 200 Momentum 30 Index Fund | 1.35% |
| Nifty 500 Multicap Momentum Quality 50 Index Fund | 1.35% |
| Nifty 500 Multifactor 50 Index Fund | 1.35% |
| Focused 25 Fund | 1.35% |
| Pure Stock Fund II | 1.30% |
| Asset Allocation Fund II | 1.25% |
| Bluechip Equity Fund | 1.25% |
| Liquid Fund | 0.95% |
| Bond Fund | 0.95% |
| Individual Short Term Debt Fund | 0.95% |
| Debt Plus Fund | 0.70% |
| Discontinued Life Policy Fund | 0.50% |
iv. Mortality Charge
Mortality Charge is the cost of the life insurance cover which depends on your age, gender, chosen sum assured and Board Approved Underwriting Policy (BAUP).
Mortality Charge will be deducted at each monthly anniversary by cancellation of units at the prevailing unit price.
v. Miscellaneous Charge
The miscellaneous charge will be charged at the rate of ₹100/- per transaction (as mentioned in the respective section). This charge will be deducted upon cancellation of Units.
vi. Discontinuance / Surrender Charge
Under a Regular/Limited Premium Policy, the Discontinuance Charge shall be applicable to the Regular Premium Fund Value based on the year of discontinuance and premium amount.
Inference from the charges: ULIPs often include costs that are not found in other market-linked investments, such as discontinuance fees, policy administration charges, and premium allocation fees. These expenses act as overheads for investors and can significantly impact returns over time, reducing the overall profitability of your investment.
Grace Period, Discontinuance and Revival of the Bajaj Life Supreme – Advantage
Grace Period
The grace period for payment of premium is 15 days for monthly mode of premium payment and 30 days for other modes of premium payment commencing from the premium due date.
Discontinuance
On Discontinuance of Regular/limited Premiums due during the first five Policy years, the Policy will be converted to a Discontinued Life Policy.
The Regular Premium Fund value less the Discontinuance/Surrender charge, along with the Top-up Premium Fund value, will be transferred to the Discontinued Life Policy Fund.
You can receive the Discontinued value (as Surrender Value) at the end of the lock-in period of five Policy years or the date of surrender, whichever is later.
On discontinuance of the due Regular/limited Premiums after the lock-in period of five Policy years, the Policy will be, immediately & automatically, converted to a Paid-up Policy, with risk cover under the base Policy reduced to the extent of the Paid-up Sum Assured and without any Loyalty Additions, Guaranteed Wealth Booster, ROMC or Rider cover.
Revival
A Discontinued Policy can only be revived within three (3) years from the date of first unpaid premium,
Free Look Period for the Bajaj Life Supreme – Advantage
You have a free look period of 30 days beginning from the date of receipt of the policy document, whether received electronically or otherwise, to review the terms and conditions of such policy, except for those policies with tenure of less than a year.
In the event you disagree with any of the Bajaj Life Supreme – Advantage Plan policy terms or conditions, or otherwise and have not made any claim, you shall have the option to return the policy to the insurer for cancellation
Surrendering the Bajaj Life Supreme – Advantage
On Surrender during the lock-in period of 5 years, the Fund Value, after deducting the applicable discontinuance/surrender charge, if any, as on the date of surrender, will be transferred to the Discontinued Life Policy Fund, and all risk and rider cover shall cease immediately.
The discontinuance value as at the end of the lock-in period will be available to you as surrender benefit.
The fund management charges of the Discontinued Life Policy Fund will be applicable during this period, and no other charges will be applied.
On Surrender after the lock-in period of 5 years, the Fund Value, as on the date of surrender, will be paid as Surrender Value. The Policy shall terminate upon payment of the full surrender value.
What are the advantages of the Bajaj Life Supreme – Advantage?
- Partial Withdrawal: Allows policyholders to access a portion of the accumulated fund value to meet immediate financial requirements, subject to applicable conditions.
- Systematic Partial Withdrawal: Provides the option to withdraw a predetermined percentage of the fund value at regular intervals, offering structured liquidity from the policy.
- Top-up Premiums: Allows policyholders to invest additional amounts through Top-up premiums, subject to the terms and conditions of the policy.
- Fund Switching: Under the Investor Selectable Portfolio Strategy, policyholders can switch between available funds to modify their investment allocation.
- Change in Premium Paying Term: The Premium Paying Term (PPT) can be changed after completion of the first five policy years, subject to the applicable terms.
- Reduction in Premium: Regular or limited premiums can be reduced after completion of five policy years, subject to the policy conditions.
- Change in Policy Features: Policyholders may have the option to reduce the Sum Assured, increase the policy term, or change the premium payment frequency, as permitted under the plan.
- Maturity Benefit in Instalments: The maturity benefit can be received in instalments under the Settlement Option instead of as a single lump-sum payment, subject to the applicable terms.
What are the disadvantages of the Bajaj Life Supreme – Advantage?
- No Policy Loan: The plan does not provide a policy loan facility, limiting access to the policy’s value during financial emergencies.
- Five-Year Lock-in: The policy has a five-year lock-in period, during which withdrawals or exit options are restricted as per the policy terms.
- Only Net Premium Is Invested: The premium is subject to applicable charges before being allocated to the investment funds. Therefore, the entire premium does not get invested from the outset.
- Insufficient Life Cover: The life cover offered may not be adequate to meet the policyholder’s actual protection needs. In addition, a Whole Life cover may not be necessary for most financial planning requirements.
- Delayed Return of Charges: Although certain charges are returned to the policy corpus at a later stage, the amount remains unavailable for investment during the intervening period. As a result, the potential for compounding on those amounts is lost.
Research Methodology of Bajaj Life Supreme – Advantage
The primary objective of market-linked investments is to generate long-term wealth. Therefore, evaluating the potential returns of Bajaj Life Supreme – Advantage is important to determine whether the plan justifies the premiums committed over the long term.
The Bajaj Life Supreme – Advantage Plan policy brochure provides illustrations, which can be analysed using the Internal Rate of Return (IRR) to facilitate comparison with other investment options.
Benefit Illustration – IRR Analysis of Bajaj Life Supreme – Advantage
Consider a 40-year-old male purchasing the plan with a Sum Assured of ₹50 lakh, a 60-year policy term, a 10-year Premium Paying Term, and an annual premium of ₹5 lakh.
| Male | 40 years |
| Sum Assured | ₹ 50,00,000 |
| Policy Term | Whole Life |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 5,00,000 |
The brochure illustrates returns based on assumed investment rates of 4% and 8% p.a. These rates are not guaranteed.
| At 4% p.a. | At 8% p.a. | ||||
| Age | Year | Annualised premium / Maturity benefit | Death benefit | Annualised premium / Maturity benefit | Death benefit |
| 40 | 1 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 41 | 2 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 42 | 3 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 43 | 4 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 44 | 5 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 45 | 6 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 46 | 7 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 47 | 8 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 48 | 9 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 49 | 10 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 50 | 11 | 0 | 50,00,000 | 0 | 50,00,000 |
| 51 | 12 | 0 | 50,00,000 | 0 | 50,00,000 |
| 52 | 13 | 0 | 50,00,000 | 0 | 50,00,000 |
| 53 | 14 | 0 | 50,00,000 | 0 | 50,00,000 |
| 54 | 15 | 0 | 50,00,000 | 0 | 50,00,000 |
| 55 | 16 | 0 | 50,00,000 | 0 | 50,00,000 |
| 56 | 17 | 0 | 50,00,000 | 0 | 50,00,000 |
| 57 | 18 | 0 | 50,00,000 | 0 | 50,00,000 |
| 58 | 19 | 0 | 50,00,000 | 0 | 50,00,000 |
| 59 | 20 | 0 | 50,00,000 | 0 | 50,00,000 |
| 60 | 21 | 0 | 50,00,000 | 0 | 50,00,000 |
| 61 | 22 | 0 | 50,00,000 | 0 | 50,00,000 |
| 62 | 23 | 0 | 50,00,000 | 0 | 50,00,000 |
| 63 | 24 | 0 | 50,00,000 | 0 | 50,00,000 |
| 64 | 25 | 0 | 50,00,000 | 0 | 50,00,000 |
| 65 | 26 | 0 | 50,00,000 | 0 | 50,00,000 |
| 66 | 27 | 0 | 50,00,000 | 0 | 50,00,000 |
| 67 | 28 | 0 | 50,00,000 | 0 | 50,00,000 |
| 68 | 29 | 0 | 50,00,000 | 0 | 50,00,000 |
| 69 | 30 | 0 | 50,00,000 | 0 | 50,00,000 |
| 70 | 31 | 0 | 50,00,000 | 0 | 50,00,000 |
| 71 | 32 | 0 | 50,00,000 | 0 | 50,00,000 |
| 72 | 33 | 0 | 50,00,000 | 0 | 50,00,000 |
| 73 | 34 | 0 | 50,00,000 | 0 | 50,00,000 |
| 74 | 35 | 0 | 50,00,000 | 0 | 50,00,000 |
| 75 | 36 | 0 | 50,00,000 | 0 | 50,00,000 |
| 76 | 37 | 0 | 50,00,000 | 0 | 50,00,000 |
| 77 | 38 | 0 | 50,00,000 | 0 | 50,00,000 |
| 78 | 39 | 0 | 50,00,000 | 0 | 50,00,000 |
| 79 | 40 | 0 | 50,00,000 | 0 | 50,00,000 |
| 80 | 41 | 0 | 50,00,000 | 0 | 50,00,000 |
| 81 | 42 | 0 | 50,00,000 | 0 | 50,00,000 |
| 82 | 43 | 0 | 50,00,000 | 0 | 50,00,000 |
| 83 | 44 | 0 | 50,00,000 | 0 | 50,00,000 |
| 84 | 45 | 0 | 50,00,000 | 0 | 50,00,000 |
| 85 | 46 | 0 | 50,00,000 | 0 | 50,00,000 |
| 86 | 47 | 0 | 50,00,000 | 0 | 50,00,000 |
| 87 | 48 | 0 | 50,00,000 | 0 | 50,00,000 |
| 88 | 49 | 0 | 50,00,000 | 0 | 50,00,000 |
| 89 | 50 | 0 | 50,00,000 | 0 | 50,00,000 |
| 90 | 51 | 0 | 50,00,000 | 0 | 50,00,000 |
| 91 | 52 | 0 | 50,00,000 | 0 | 50,00,000 |
| 92 | 53 | 0 | 50,00,000 | 0 | 50,00,000 |
| 93 | 54 | 0 | 50,00,000 | 0 | 50,00,000 |
| 94 | 55 | 0 | 50,00,000 | 0 | 50,00,000 |
| 95 | 56 | 0 | 50,00,000 | 0 | 50,00,000 |
| 96 | 57 | 0 | 50,00,000 | 0 | 50,00,000 |
| 97 | 58 | 0 | 50,00,000 | 0 | 50,00,000 |
| 98 | 59 | 0 | 50,00,000 | 0 | 50,00,000 |
| 99 | 60 | 0 | 50,00,000 | 0 | 50,00,000 |
| 2,39,28,296 | 19,20,06,784 | ||||
| IRR | 2.86% | 6.76% | |||
At 4%, the projected fund value is ₹2.39 crore, with an IRR of 2.86% as per the Bajaj Life Supreme – Advantage Plan maturity calculator.
At 8%, the fund value is ₹19.20 crore, with an IRR of 6.76% as per the Bajaj Life Supreme – Advantage Plan maturity calculator.
The IRR gives a more realistic measure of the return after considering the premium outflows and policy structure.
The policy matures at age 99, resulting in a very long investment commitment. The ₹50 lakh life cover may also be inadequate, while life insurance extending to age 99 may not be necessary for most financial planning needs.
Considering the long tenure, limited liquidity, relatively low life cover, and moderate IRR, Bajaj Life Supreme – Advantage may not be an attractive option compared with keeping insurance and investments separate.
Bajaj Life Supreme – Advantage Vs. Other Investments
Bajaj Life Supreme – Advantage is a market-linked product, but its projected IRR is relatively low compared with other investment options. A more meaningful comparison is to separate the insurance and investment components.
Bajaj Life Supreme – Advantage Vs. Pure-Term + Equity Mutual Fund
For the same ₹5 lakh annual outflow, a ₹50 lakh pure-term life insurance policy costs ₹26,700 annually.
With the remaining ₹4,73,300, the investor can choose an investment based on their risk profile. Here, we consider an equity mutual fund as the market-linked investment option.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 50,00,000 |
| Policy Term | 30 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 26,700 |
| Investment | ₹ 4,73,300 |
Based on the same assumptions, the equity mutual fund grows to ₹268 crore before tax and ₹235 crore after capital gains tax, resulting in a post-tax IRR of 11.63% when combined with the term insurance premium.
| Term insurance + Equity Mutual Fund | |||
| Age | Year | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 40 | 1 | -5,00,000 | 50,00,000 |
| 41 | 2 | -5,00,000 | 50,00,000 |
| 42 | 3 | -5,00,000 | 50,00,000 |
| 43 | 4 | -5,00,000 | 50,00,000 |
| 44 | 5 | -5,00,000 | 50,00,000 |
| 45 | 6 | -5,00,000 | 50,00,000 |
| 46 | 7 | -5,00,000 | 50,00,000 |
| 47 | 8 | -5,00,000 | 50,00,000 |
| 48 | 9 | -5,00,000 | 50,00,000 |
| 49 | 10 | -5,00,000 | 50,00,000 |
| 50 | 11 | 0 | 50,00,000 |
| 51 | 12 | 0 | 50,00,000 |
| 52 | 13 | 0 | 50,00,000 |
| 53 | 14 | 0 | 50,00,000 |
| 54 | 15 | 0 | 50,00,000 |
| 55 | 16 | 0 | 50,00,000 |
| 56 | 17 | 0 | 50,00,000 |
| 57 | 18 | 0 | 50,00,000 |
| 58 | 19 | 0 | 50,00,000 |
| 59 | 20 | 0 | 50,00,000 |
| 60 | 21 | 0 | 50,00,000 |
| 61 | 22 | 0 | 50,00,000 |
| 62 | 23 | 0 | 50,00,000 |
| 63 | 24 | 0 | 50,00,000 |
| 64 | 25 | 0 | 50,00,000 |
| 65 | 26 | 0 | 50,00,000 |
| 66 | 27 | 0 | 50,00,000 |
| 67 | 28 | 0 | 50,00,000 |
| 68 | 29 | 0 | 50,00,000 |
| 69 | 30 | 0 | 50,00,000 |
| 70 | 31 | 0 | 50,00,000 |
| 71 | 32 | 0 | 50,00,000 |
| 72 | 33 | 0 | 50,00,000 |
| 73 | 34 | 0 | 50,00,000 |
| 74 | 35 | 0 | 50,00,000 |
| 75 | 36 | 0 | 50,00,000 |
| 76 | 37 | 0 | 50,00,000 |
| 77 | 38 | 0 | 50,00,000 |
| 78 | 39 | 0 | 50,00,000 |
| 79 | 40 | 0 | 50,00,000 |
| 80 | 41 | 0 | 50,00,000 |
| 81 | 42 | 0 | 50,00,000 |
| 82 | 43 | 0 | 50,00,000 |
| 83 | 44 | 0 | 50,00,000 |
| 84 | 45 | 0 | 50,00,000 |
| 85 | 46 | 0 | 50,00,000 |
| 86 | 47 | 0 | 50,00,000 |
| 87 | 48 | 0 | 50,00,000 |
| 88 | 49 | 0 | 50,00,000 |
| 89 | 50 | 0 | 50,00,000 |
| 90 | 51 | 0 | 50,00,000 |
| 91 | 52 | 0 | 50,00,000 |
| 92 | 53 | 0 | 50,00,000 |
| 93 | 54 | 0 | 50,00,000 |
| 94 | 55 | 0 | 50,00,000 |
| 95 | 56 | 0 | 50,00,000 |
| 96 | 57 | 0 | 50,00,000 |
| 97 | 58 | 0 | 50,00,000 |
| 98 | 59 | 0 | 50,00,000 |
| 99 | 60 | 0 | 50,00,000 |
| 2,35,29,98,369 | |||
| IRR | 11.63% | ||
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 60 years | 2,68,84,46,994 |
| Purchase price | 47,33,000 |
| Long-Term Capital Gains | 2,68,37,13,994 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 2,68,35,88,994 |
| Tax paid on LTCG | 33,54,48,624 |
| Maturity value after tax | 2,35,29,98,369 |
Although the comparison assumes redemption at age 99 for consistency, a mutual fund provides significantly greater liquidity, allowing the investor to redeem when required rather than waiting until a predetermined maturity age.
Considering the long policy tenure, limited life cover, restricted liquidity, and lower potential IRR, Bajaj Life Supreme – Advantage may not be the most efficient way to combine insurance and wealth creation.
Separating term insurance for protection and mutual funds for investment can offer greater flexibility and potentially better long-term wealth creation.
Final Verdict on Bajaj Life Supreme – Advantage
Bajaj Life Supreme is a ULIP available in nine variants, with equity investment options that may appear attractive for long-term wealth creation. However, a closer analysis of the Bajaj Life Supreme – Advantage variant shows that the returns may not justify the costs and long-term commitment.
The impact of various charges reduces the amount available for investment and affects long-term compounding.
Although some charges are returned at a later stage, this does not fully offset the opportunity cost of having those amounts unavailable for investment.
Further, the ₹50 lakh life cover may be inadequate to meet future family needs and it also has a high agent commission.
For equity-oriented wealth creation, it may be more efficient to keep insurance and investment separate: choose adequate pure-term insurance for protection and build an investment portfolio based on your risk appetite, goals, and time horizon.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?If you need help aligning insurance and investments with your financial goals, consider consulting a qualified financial planner for a customised financial plan.


Leave a Reply