


 Listen to this article
Can the Bandhan Life iGuarantee Child Assure Plan truly secure your child’s financial future, or do its guaranteed benefits come with important trade-offs?
Does the Bandhan Life iGuarantee Child Assure Plan provide the right combination of protection and savings for your child, or are there better alternatives available?
Is the Bandhan Life iGuarantee Child Assure Plan a smart way to plan for your child’s future, or does the comfort of guarantees come at the cost of wealth creation?
This article examines the Bandhan Life iGuarantee Child Assure Plan, a traditional insurance product designed to combine life insurance with structured savings.
We take a closer look at its key features, benefits, and limitations, supported by a detailed illustration to understand how the plan works and what it could mean for long-term wealth creation.
Table of Contents:
What is the Bandhan Life iGuarantee Child Assure?
What are the features of the Bandhan Life iGuarantee Child Assure?
Who is eligible for the Bandhan Life iGuarantee Child Assure?
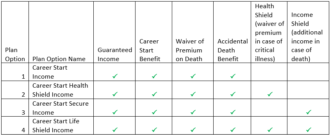
What are the Plan options and their benefits of the Bandhan Life iGuarantee Child Assure?
Grace Period, Discontinuance and Revival of the Bandhan Life iGuarantee Child Assure
Free Look Period for the Bandhan Life iGuarantee Child Assure
Surrendering the Bandhan Life iGuarantee Child Assure
What are the advantages of the Bandhan Life iGuarantee Child Assure?
What are the disadvantages of the Bandhan Life iGuarantee Child Assure?
Research Methodology of Bandhan Life iGuarantee Child Assure
Benefit Illustration – IRR Analysis of Bandhan Life iGuarantee Child Assure
Bandhan Life iGuarantee Child Assure Vs. Other Investments
Bandhan Life iGuarantee Child Assure Vs. Pure-Term + Equity Mutual Fund
Final Verdict on the Bandhan Life iGuarantee Child Assure
What is the Bandhan Life iGuarantee Child Assure?
Bandhan Life iGuarantee Child Assure is Non-Linked Non–Participating, Individual Life Insurance Savings Plan. It is designed for parents of newborn children to 21 years of age.
This plan enables long-term savings aligned with a child’s growth stages, ensuring that aspirations remain on track even in the parent’s absence.
What are the features of the Bandhan Life iGuarantee Child Assure?
- Multiple Plan Options: Options designed to support your child’s needs at different life stages.
- Guaranteed Income: Regular assured income throughout the chosen income period.
- Career Start Benefit: Additional lump sum for higher education or starting a career.
- Health Shield: Premium waiver on diagnosis of any of the five specified critical illnesses.
- Income Shield: Monthly income for 5 or 10 years in case of the Life Assured’s death.
- Double Death Benefit: Additional 100% of Base Sum Assured on Death for accidental death.
- Value-Added Service: Complimentary International Second Medical Opinion (ISMO) facility.
Who is eligible for the Bandhan Life iGuarantee Child Assure?
| Parameter | Minimum | Maximum |
| Entry Age (Life Assured) | 18 years | 50 years |
| Entry Age (Child) | 0 years | 21 years |
| Maturity Age | 27 years | 67 years |
| Premium Payment Term | 8,10,12 years | |
| Deferment Period | 1 to 5 years | |
| Policy Term | 9 years | 17 years |
| Premium | ₹ 36,000 | No Limit (Subject to Board-approved Underwriting Policy of the company) |
| Income Period | Premium Payment Term | Income Period |
| 8 years | 4/5/6 years | |
| 10 to 12 years | 4/5/6/7years | |
| Sum Assured on Death | 10.5 times annualised premiumMinimum Sum Assured: 3,78,000 | No limit, subject to ‘Board Approved Underwriting Policy’ of the Company |
| Premium Payment Mode | Yearly, Half-yearly, Quarterly and Monthly | |
What are the Plan options and their benefits of the Bandhan Life iGuarantee Child Assure?
1. Maturity Benefit
Guaranteed Income:
Under all Plan Options, on completion of the Policy Term, a regular Guaranteed Income shall be paid every year in arrears, from the end of (Policy Term +1) year till the end of the chosen Income Period, as opted at the start of the policy.
Guaranteed Income: Guaranteed Income Rate X Annualised Premium
Under all plan options, the income period shall be chosen at the inception, and no life cover shall be available during this period.
Career Start Benefit:
Under all Plan Options, in addition to Guaranteed Income, a lump sum amount known as the Career Start Benefit shall be paid at the end of the income period, which is equal to the sum of Career Start Additions attached during the policy term.
Career Start Additions will accrue at the end of each policy year starting from the end of the first policy year till the end of the Bandhan Life iGuarantee Child Assure Plan policy term.
The Career Start Addition percentage will vary by the Deferment Period, Income Period, Age, Gender, Premium Payment Term, Plan Option and Annualised Premium, and will be applicable on the Total Premiums Paid (year on year).
Career Start Additions = Career Start Addition Rate X Total Premiums Paid
2 Death Benefit
Under all Plan Options, in case of the unfortunate event of death of the Life Assured during the Bandhan Life iGuarantee Child Assure Plan Policy Term, when the policy is in force (where all due premiums have been paid), the lump sum benefit payable on Death will be the higher of
- Sum Assured on Death or
- Surrender Value as on the date of death.
Future premiums (if any) shall be waived off, and the policy shall continue as an in-force policy with all benefits except Death Benefit.
Wherein, the Sum Assured on Death is the higher of:
- 10.5 x Annualised Premium, which is Base Sum Assured plus Income Shield Benefit (for Plan Option 3 and Option 4, as defined above).
- 105% of Total Premiums Paid plus loading for modal premiums till date of death
Accidental Death Benefit:
In case of death of Life Assured due to Accident during the Bandhan Life iGuarantee Child Assure Plan Policy Term, an additional benefit equal to 100% of Base Sum Assured shall be paid to nominee in addition to Base Death Benefit.
Health Shield Applicable for Plan Option 2 and Option 4 only:
Under this feature, if the Life Assured is diagnosed with any of the 5 covered critical illnesses during the Premium Payment Term and the policy is in force, then all future premiums (if any) will be waived, and the policy will continue as an in-force policy with all benefits.
In case of death after a claim is made under this option, Base Death Benefit and Accidental Death Benefit (if applicable) will be paid.
Income Shield Applicable for Plan Option 3 and Option 4 only:
Under this feature, if the Life Assured dies during the Bandhan Life iGuarantee Child Assure Plan Policy Term, then an additional benefit equal to 25% of Base Sum Assured shall be payable.
This amount shall be converted into monthly income for 5 or 10 years using an interest rate. The monthly income will start from the next monthly anniversary following the date of acceptance of claim
Grace Period, Discontinuance and Revival of the Bandhan Life iGuarantee Child Assure
Grace Period
The Grace Period is 15 days for policies under monthly premium payment frequency and 30 Days for all other frequencies from the premium due date, during which the due premium can be paid (without any interest), and the policy is considered to be in-force with the risk cover
Discontinuance
If at least the first full year’s premium from the date of inception of the policy has not been paid by you, the policy will automatically and immediately lapse on the date of expiry of the Grace Period.
If a lapsed policy is not reinstated during the revival period and before the expiry of the Bandhan Life iGuarantee Child Assure Plan policy term, it will automatically stand terminated. No benefit will be paid in case of a lapsed policy on death, survival or surrender.
If at least the first full year’s premium has been paid and subsequent premiums are not paid, then the policy shall not lapse.
Instead, the policy will be immediately and automatically converted to a reduced paid-up policy at the expiry of the grace period. Once the policy is in reduced paid-up status, it is eligible for the reduced benefits.
Revival
The Bandhan Life iGuarantee Child Assure Plan policyholder may revive the policy within five consecutive completed years from the due date of the first unpaid premium (“Revival Period”) and before the expiry of the policy term.
Free Look Period for the Bandhan Life iGuarantee Child Assure
If the Policyholder is not satisfied with any of the terms and conditions of the policy or otherwise and has not made any claims, the Policyholder may request the Company for cancellation of the policy within 30 days from the date of receipt of the policy document, whether received electronically or otherwise.
Surrendering the Bandhan Life iGuarantee Child Assure
You can surrender the policy at any time during the Bandhan Life iGuarantee Child Assure Plan policy term after completion of the first policy year, provided one full year’s premium has been paid.
The surrender benefit payable will be the highest of the guaranteed surrender value (GSV) and special surrender value (SSV) as on the date of surrender.
Guaranteed Surrender Value (GSV) shall be payable provided 2 full years’ premiums have been paid. Special Surrender Value (SSV) shall be payable after completion of the first policy year, provided one full year’s premium has been received from the date of inception of the policy.
What are the advantages of the Bandhan Life iGuarantee Child Assure?
- Loan Facility: Loan available up to 80% of the Surrender Value.
- Inbuilt Benefits: Waiver of Premium and Accidental Death Benefit are included.
What are the disadvantages of the Bandhan Life iGuarantee Child Assure?
- No Death Benefit After Policy Term: No death benefit is payable if the Life Assured dies during the Income Period.
- Risk of Discretionary Spending: Regular annual payouts may encourage unnecessary spending.
- Reduced Compounding: Early payouts can limit the benefit of long-term compounding.
- Low Returns: Despite guaranteed benefits, the overall returns remain modest.
- Complex Plan Structure: Multiple variants and benefit combinations can make the plan difficult to understand.
Research Methodology of Bandhan Life iGuarantee Child Assure
The regular income paid as a maturity benefit is one of the key features of the Bandhan Life iGuarantee Child Assure Plan.
While guaranteed payouts may provide certainty, the real value of the plan depends on the returns generated on the premiums paid. Let’s calculate the Internal Rate of Return (IRR) using an illustration from the policy brochure.
Benefit Illustration – IRR Analysis of Bandhan Life iGuarantee Child Assure
Consider a 35-year-old male opting for the Career Start Health Shield Income option, with an annual premium of ₹1,00,000 payable for 10 years.
The income payout begins after a 10-year premium-paying term and a 5-year deferment period, making it 15 years before the payouts start. The income is paid for 5 years, with a Sum Assured of ₹10.5 lakh.
| Male | 35 years |
| Sum Assured | ₹ 10,50,000 |
| Policy Term | 15 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 1,00,000 |
Under this illustration, the policyholder receives a guaranteed income of ₹2,00,000 per year for 5 years, along with a Career Start Benefit of ₹8,54,700 at the end of the 20th policy year.
Based on these cash flows, the IRR works out to 4.34% as per the Bandhan Life iGuarantee Child Assure Plan maturity calculator, indicating relatively modest returns.
| Age | Year | Annualised premium / Maturity benefit | Death benefit |
| 35 | 1 | -1,00,000 | 10,50,000 |
| 36 | 2 | -1,00,000 | 10,50,000 |
| 37 | 3 | -1,00,000 | 10,50,000 |
| 38 | 4 | -1,00,000 | 10,50,000 |
| 39 | 5 | -1,00,000 | 10,50,000 |
| 40 | 6 | -1,00,000 | 10,50,000 |
| 41 | 7 | -1,00,000 | 10,50,000 |
| 42 | 8 | -1,00,000 | 10,50,000 |
| 43 | 9 | -1,00,000 | 10,50,000 |
| 44 | 10 | -1,00,000 | 10,50,000 |
| 45 | 11 | 0 | 10,50,000 |
| 46 | 12 | 0 | 10,50,000 |
| 47 | 13 | 0 | 10,50,000 |
| 48 | 14 | 0 | 10,50,000 |
| 49 | 15 | 0 | 10,50,000 |
| 50 | 16 | 0 | 10,50,000 |
| 51 | 17 | 2,00,000 | 10,50,000 |
| 52 | 18 | 2,00,000 | 10,50,000 |
| 53 | 19 | 2,00,000 | 10,50,000 |
| 54 | 20 | 2,00,000 | 10,50,000 |
| 55 | 10,54,700 | ||
| IRR | 4.34% |
While guaranteed income provides predictability, a low return can limit the plan’s ability to build a substantial corpus over the long term.
The extended deferment period also means that the money remains committed for many years before the major benefits are received. In addition, the Sum Assured of ₹10.5 lakh may be inadequate to provide meaningful financial protection for a family.
Therefore, parents should evaluate the plan not only on the certainty of its payouts but also on its return potential, liquidity, inflation impact, and adequacy of life cover before using it as a primary vehicle for funding their child’s future expenses.
Bandhan Life iGuarantee Child Assure Vs. Other Investments
While the Bandhan Life iGuarantee Child Assure Plan offers guaranteed benefits, the returns may not keep pace with inflation over the long term.
With modest returns and limited insurance coverage, the plan may not effectively serve either as a wealth-creation investment or as adequate life protection.
A combination of pure-term insurance and separate investments can provide greater flexibility in aligning savings with specific financial milestones.
Bandhan Life iGuarantee Child Assure Vs. Pure-Term + Equity Mutual Fund
For life protection, a pure-term insurance policy can provide substantial coverage at a relatively low premium. The premium saved can then be invested separately based on the investor’s risk profile and financial goals.
Risk-averse investors may consider debt instruments such as PPF, while investors with a higher risk appetite and a longer investment horizon may consider equity instruments such as Equity Mutual Funds.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 10,50,000 |
| Policy Term | 15 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 5,900 |
| Investment | ₹ 94,100 |
Consider a pure-term policy with a Sum Assured of ₹10.5 lakh, costing ₹5,900 annually for 10 years. The remaining ₹94,100 each year can be invested in an Equity Mutual Fund.
At the end of 15 years, this investment grows to approximately ₹32.59 lakh. After accounting for capital gains tax, the resulting corpus of ₹29.85 lakh can be moved to an investment earning 7% per annum.
| Term insurance + Equity Mutual Fund | |||
| Age | Year | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 35 | 1 | -1,00,000 | 10,50,000 |
| 36 | 2 | -1,00,000 | 10,50,000 |
| 37 | 3 | -1,00,000 | 10,50,000 |
| 38 | 4 | -1,00,000 | 10,50,000 |
| 39 | 5 | -1,00,000 | 10,50,000 |
| 40 | 6 | -1,00,000 | 10,50,000 |
| 41 | 7 | -1,00,000 | 10,50,000 |
| 42 | 8 | -1,00,000 | 10,50,000 |
| 43 | 9 | -1,00,000 | 10,50,000 |
| 44 | 10 | -1,00,000 | 10,50,000 |
| 45 | 11 | 0 | 10,50,000 |
| 46 | 12 | 0 | 10,50,000 |
| 47 | 13 | 0 | 10,50,000 |
| 48 | 14 | 0 | 10,50,000 |
| 49 | 15 | 0 | 10,50,000 |
| 50 | 16 | 0 | 10,50,000 |
| 51 | 17 | 2,00,000 | 10,50,000 |
| 52 | 18 | 2,00,000 | 10,50,000 |
| 53 | 19 | 2,00,000 | 10,50,000 |
| 54 | 20 | 2,00,000 | 10,50,000 |
| 55 | 32,36,839 | ||
| IRR | 9.54% | ||
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 15 years | 32,59,444 |
| Purchase price | 9,41,000 |
| Long-Term Capital Gains | 23,18,444 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 21,93,444 |
| Tax paid on LTCG | 2,74,181 |
| Maturity value after tax | 29,85,264 |
From this corpus, the investor can withdraw an annual amount similar to the income benefit offered by the Bandhan Life iGuarantee Child Assure Plan, while still retaining approximately ₹32.36 lakh.
The resulting IRR is 9.54%, compared with 4.34% for the Bandhan Life plan in the earlier illustration.
The alternative approach also provides greater control over the investment corpus. If withdrawals are not required immediately, the money can remain invested and continue to compound.
This combination of adequate protection, potentially higher returns, liquidity, and flexibility can make it easier to align the investment strategy with changing financial needs and long-term goals.
Final Verdict on the Bandhan Life iGuarantee Child Assure
The Bandhan Life iGuarantee Child Assure Plan is a traditional money-back policy that combines life insurance with periodic cash payouts.
While the plan offers multiple benefit combinations across its variants, the complexity of these options can make it difficult for investors to understand the product and select the most appropriate variant.
One of its notable features is the premium waiver and policy continuation benefit in the event of the policyholder’s death. However, the life cover does not continue beyond the income payout period.
When the objective is to build a corpus for a child’s education, the plan has important limitations.
Education expenses can rise significantly over time, and the relatively modest returns and limited liquidity of the policy may make it difficult to accumulate a corpus that keeps pace with rising costs.
Relying on fixed payouts may also leave parents with a funding shortfall when the actual education expense arises and it also has a high agent commission.
For long-term goals such as a child’s education, starting early and choosing investments based on the goal’s time horizon, inflation, and required corpus is essential.
A well-structured investment strategy can provide greater flexibility to adjust contributions and build wealth over time.
Life insurance and investments can also be addressed separately. A pure-term life insurance policy can provide adequate financial protection for the family, while goal-oriented investments can be selected separately for the child’s education and other milestones.
Ultimately, securing a child’s future requires more than guaranteed payouts—it requires adequate protection, appropriate returns, liquidity, and a strategy aligned with the family’s financial goals.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
A Certified Financial Planner (CFP) can help evaluate these factors and develop a comprehensive financial plan suited to your needs.


Leave a Reply