


 Listen to this article
Can Pramerica Life Poorna Rakshak help you achieve your long-term financial goals?
Can the guaranteed benefits and structured payouts of Pramerica Life Poorna Rakshak provide financial security?
Is Pramerica Life Poorna Rakshak suitable for meeting your future financial needs?
Can investing in Pramerica Life Poorna Rakshak help turn your long-term aspirations into financially secure realities?
This article takes a closer look at the plan’s various options, key features, advantages and limitations to help you assess whether it is the right choice for your financial goals.
Table of Contents
- What is the Pramerica Life Poorna Rakshak?
- What are the features of the Pramerica Life Poorna Rakshak?
- Who is eligible for the Pramerica Life Poorna Rakshak?
- What are the plan options and their benefits for the Pramerica Life Poorna Rakshak?
- Grace Period, Discontinuance and Revival of the Pramerica Life Poorna Rakshak
- Free Look Period for the Pramerica Life Poorna Rakshak
- Surrendering the Pramerica Life Poorna Rakshak
- What are the advantages of the Pramerica Life Poorna Rakshak?
- What are the disadvantages of the Pramerica Life Poorna Rakshak?
- Research Methodology of Pramerica Life Poorna Rakshak
- Pramerica Life Poorna Rakshak Vs. Other Investments
- Final Verdict on Pramerica Life Poorna Rakshak
1. What is the Pramerica Life Poorna Rakshak?
Pramerica Life Poorna Rakshak is a Non-Linked, Non-Participating Individual Savings Life Insurance Plan.
It is crafted to deliver assured payouts and flexible income structures aligned to your goals.
Through various variants, this plan empowers you to choose how and when you receive benefits, combining life protection with guaranteed returns and income certainty.
2. What are the features of the Pramerica Life Poorna Rakshak?
- Guaranteed Protection: Provides life cover throughout the policy term, helping safeguard your family’s financial needs and long-term goals.
- Guaranteed Benefits: Offers defined benefits with greater certainty, provided the policy remains in force and all premiums due are paid on time and in full.
- Choice of Four Variants: Allows you to choose from four plan variants designed to suit different financial goals and stages of life.
- Comprehensive Protection: Protection can be enhanced through optional riders covering risks such as death, disease and disability.
- Tax Benefits: Tax benefits may be available on premiums paid and benefits received, subject to prevailing Income Tax laws and applicable conditions. Tax regulations may change, so it is advisable to consult a tax professional.
- Other Benefits: Additional features include discounts for existing customers and employees, the option to accumulate Survival Benefits, and a Premium Offset facility.
3. Who is eligible for the Pramerica Life Poorna Rakshak?
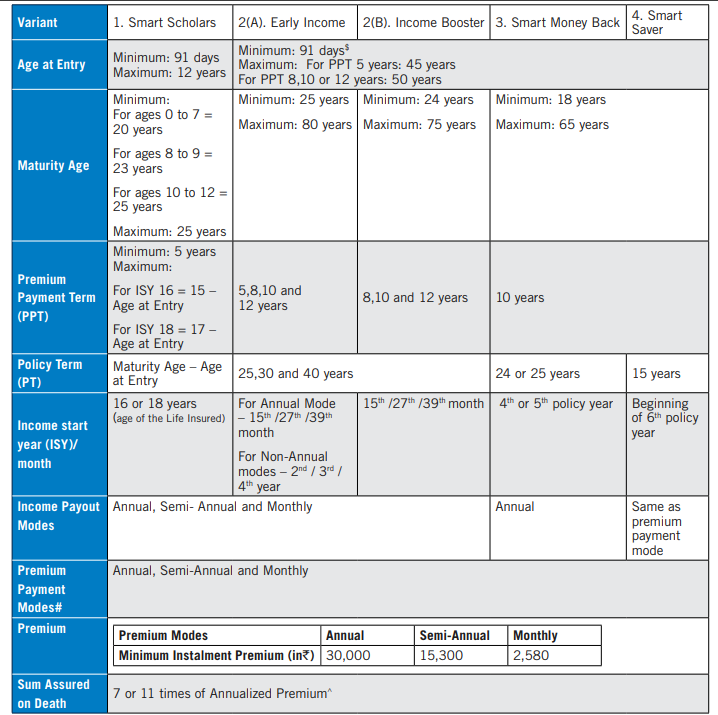
4. What are the plan options and their benefits for the Pramerica Life Poorna Rakshak?
a. Survival Benefit
Plan Variant 1: Smart Scholars
Survival Benefit comprising Guaranteed Income Benefit (GIB) along with Loyalty Income Benefit (LIB) will be paid as per the Income frequency chosen, from the end of the policy year where the age of the life insured as on Last Birthday is 16 or 18 years, as chosen by the proposer at inception and shall continue till the end of the Pramerica Life Poorna Rakshak Policy Term (as chosen at inception).
Guaranteed Income Benefit (GIB) – GIB is defined as a percentage of Annualised Premium and depends on the Age of Life Insured, Income Start Age, Premium and Policy Term as chosen at inception.
Loyalty Income Benefit, calculated as a percentage of Guaranteed Income Benefit, shall vary as per the premium payment term.
Plan Variant 2 (A): Early Income
The Policyholder/Life Insured shall receive Guaranteed Income Benefit (income pay-out) expressed as a percentage of Annualised Premium as per the Income Start Year/Month and Premium payment mode chosen at inception.
Plan Variant 2 (B): Income Booster
An Instant Cashback of 25% or 35% (to be chosen at inception) of Annualised Premium is paid back to the Policyholder/Beneficiary within 10 (ten) days of realisation of the first year’s premium by the company post issuance of the policy.
Only Annual mode of premium payment is allowed for this variant.
Upon survival of the Life Insured during the Pramerica Life Poorna Rakshak Policy Term, provided all due premiums have been paid in full, and the policy remains in force, the Policyholder/Life Insured shall receive the following benefit:
Guaranteed Income Benefit (income pay-out) expressed as a percentage of Annualised Premium is paid at an interval of 12 months starting from the end of 15th/ 27th/ 39th month (as chosen at inception) till the end of the Policy Term
Plan Variant 3: Smart Money Back
Guaranteed Income Benefit will be paid periodically commencing 4th / 5th policy year as chosen at inception will be paid to the Policyholder/Beneficiary.
Once the Guaranteed Income Benefit (GIB) starts, subsequent GIB will be paid after every 5 years.
The GIB will increase payouts, where each payout shall be twice the amount of the previous payout
Plan Variant 4: Smart Saver
Guaranteed Income Benefit (GIB) equal to 50% of One Modal Premium along with Loyalty Income Benefit (LIB) equal to 50% of One Modal Premium will be paid from the beginning of the 6th policy year till the beginning of the 10th policy year to the Life Insured as and when the premium payment is due.
Loyalty Income Benefit will only be paid if premium for first 5 years has been paid in full.
b. Maturity Benefit
Plan Variant 1: Smart Scholars
The Policyholder/Beneficiary shall receive an amount equal to one Annualised Premium as Guaranteed Lumpsum Benefit (GLB) at the end of the Pramerica Life Poorna Rakshak Policy Term.
Plan Variant 2 (A): Early Income and Plan Variant 2 (B): Income Booster
The Policyholder/ Life Insured shall receive Total Maturity Benefit defined as an amount equal to 80% or 100% (as chosen at inception) of the Total Annualised Premiums Paid, at the end of the Policy Term, out of which 50% shall be paid as Accrued Guaranteed Additions (AGA) and the remaining 50% shall be paid as Guaranteed Lumpsum Benefit (GLB).
Accrued Guaranteed Additions will accrue in arrears uniformly from the end of the 3rd policy year to the end of the Premium Paying Term, given that premiums are paid for that Policy year in full.
Plan Variant 3: Smart Money Back
There is no Maturity Benefit in this variant
Plan Variant 4: Smart Saver
The Policyholder/Beneficiary shall receive a Guaranteed Lumpsum Benefit (GLB) as an amount equal to X% of the Total Premiums Paid, to be paid at the end of the Policy Term.
Where X varies based on age, Premium Band & Sum Assured Multiple of the Life Insured
c. Death Benefit
For all Variants
In case of death of the Life Insured, provided all due premiums are paid in full, and the policy is in force, Death Benefit shall be the higher of:
- Sum Assured on Death
- 105% of Total Premiums Paid till the date of death (or)
- Surrender Value as on the date of death
Upon the payment of Death Benefit to the nominee/policyholder as the case may be, the policy shall terminate, and no further benefits will be payable.
5. Grace Period, Discontinuance and Revival of the Pramerica Life Poorna Rakshak
i. Grace Period
If you are unable to pay your premium by the due date, you will be given a grace period of 15 days for monthly mode and 30 days for all other premium payment modes
ii. Premium Discontinuance
The Pramerica Life Poorna Rakshak Policy will acquire Surrender Value after paying premium for the first complete policy year & will become payable after completion of first policy year.
If you discontinue the payment of premiums before your Policy has acquired a Surrender Value, your Policy will lapse at the end of the grace period, the Death Benefit will cease immediately, and no benefits will be paid when the Policy is in lapsed status.
If the Policy has acquired a Surrender Value and no future premiums are paid, you may choose to continue your Policy on a Reduced Paid-up basis. On your Policy becoming Reduced Paid-up, benefits under the plan will be reduced.
iii. Revival
You can revive your lapsed/Paid-up policy for its full coverage within five years from the due date of the first unpaid premium but before policy maturity, by paying all outstanding premiums together with the interest, as applicable.
6. Free Look Period for the Pramerica Life Poorna Rakshak
The Policyholder will have a period of 30 days from the date of receipt of the Policy Document to review the terms and conditions of the Policy and where he/she can disagree to any of these terms and conditions, he/she will have an option to return the Policy stating the reasons for objection.
7. Surrendering the Pramerica Life Poorna Rakshak
The policy will acquire a surrender value after paying the premium for the first complete policy year & will become payable after completion of the first policy year.
If you choose to discontinue your policy, you will be entitled to receive the Surrender Value, which will be the higher of the Guaranteed Surrender Value (GSV), if applicable or the Special Surrender Value (SSV) of the Pramerica Life Poorna Rakshak Policy.
8. What are the advantages of the Pramerica Life Poorna Rakshak?
- Premium Offset Facility: The policyholder can adjust the premium payable against the Survival Benefits payable by the company, subject to the applicable terms and conditions.
- Option to Accrue Survival Benefits: Under Variants 1 and 2, the policyholder can choose to accumulate the Survival Benefits instead of receiving them immediately.
- Flexible Premium Payment Modes: Premiums can be paid annually, half-yearly or monthly, providing flexibility in managing premium payments.
- Loan Facility: A loan can be availed against the policy, subject to the applicable terms and conditions. The maximum loan amount is 75% of the policy’s Surrender Value.
- Rider Options: Riders are available with all plan variants except Variant 4 – Smart Saver, allowing policyholders to enhance their protection based on their needs.
9. What are the disadvantages of the Pramerica Life Poorna Rakshak?
- Inadequate Life Cover: The sum assured may not be sufficient to fully meet your family’s future financial needs and obligations.
- Lower Return Potential: The plan may offer lower returns compared with other investment avenues available for long-term wealth creation.
- No Deferral of Survival Benefits: Under Plan Options 3 and 4, the Survival Benefit cannot be deferred, limiting the flexibility to retain the money within the policy for future needs.
- Risk of Unplanned Spending: Regular income payouts may encourage discretionary spending instead of being directed towards purposeful wealth accumulation.
- Impact on Compounding: Receiving Survival Benefits earlier interrupts the compounding process, potentially reducing the amount that could have accumulated over the long term.
10. Research Methodology of Pramerica Life Poorna Rakshak
From a liquidity perspective, the Pramerica Life Poorna Rakshak Plan provides guaranteed Survival Benefits, which may commence as early as the end of the first policy year or after the completion of the premium payment term, depending on the plan variant.
However, the availability of periodic payouts alone does not determine whether a product is financially attractive.
The actual return generated on the investment is equally important.
Therefore, the Internal Rate of Return (IRR) is a useful measure to assess the effectiveness of the plan based on the cash flows disclosed in the policy brochure.
Benefit Illustration – IRR Analysis of Pramerica Life Poorna Rakshak
Consider a 35-year-old male investing ₹1,00,000 annually in the Pramerica Life Poorna Rakshak Plan, with a 10-year premium payment term and a 25-year policy term under Plan Variant 1 – Smart Scholars.
The income benefits are received annually, along with a lump-sum maturity benefit.
The base Sum Assured is ₹11 lakh.
| Male | 35 years |
| Sum Assured | ₹ 11,00,000 |
| Policy Term | 25 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 1,00,000 |
Under this illustration, the Survival Benefit of ₹2,98,750 per annum begins from the end of the 18th policy year and is payable thereafter till the end of the policy term.
In addition, a lump-sum maturity benefit of ₹1 lakh is received at maturity. Based on the illustrated cash flows, the IRR works out to approximately 5.44% as per the Pramerica Life Poorna Rakshak maturity calculator.
| Age | Year | Annualised premium / Maturity benefit | Death benefit |
| 35 | 1 | -1,00,000 | 11,00,000 |
| 36 | 2 | -1,00,000 | 11,00,000 |
| 37 | 3 | -1,00,000 | 11,00,000 |
| 38 | 4 | -1,00,000 | 11,00,000 |
| 39 | 5 | -1,00,000 | 11,00,000 |
| 40 | 6 | -1,00,000 | 11,00,000 |
| 41 | 7 | -1,00,000 | 11,00,000 |
| 42 | 8 | -1,00,000 | 11,00,000 |
| 43 | 9 | -1,00,000 | 11,00,000 |
| 44 | 10 | -1,00,000 | 11,00,000 |
| 45 | 11 | 0 | 11,00,000 |
| 46 | 12 | 0 | 11,00,000 |
| 47 | 13 | 0 | 11,00,000 |
| 48 | 14 | 0 | 11,00,000 |
| 49 | 15 | 0 | 11,00,000 |
| 50 | 16 | 0 | 11,00,000 |
| 51 | 17 | 0 | 11,00,000 |
| 52 | 18 | 0 | 11,00,000 |
| 53 | 19 | 2,98,750 | 11,00,000 |
| 54 | 20 | 2,98,750 | 11,00,000 |
| 55 | 21 | 2,98,750 | 11,00,000 |
| 56 | 22 | 2,98,750 | 11,00,000 |
| 57 | 23 | 2,98,750 | 11,00,000 |
| 58 | 24 | 2,98,750 | 11,00,000 |
| 59 | 25 | 2,98,750 | 11,00,000 |
| 60 | 3,98,750 | ||
| IRR | 5.44% |
An IRR of around 5.44% over a 25-year period may not be compelling for a long-term investor, particularly when the objective is meeting future financial goals.
Further, the fixed Survival Benefits are not linked to inflation.
As the cost of living rises over time, the purchasing power of these payouts may decline significantly.
Therefore, while the plan provides guaranteed payouts and life cover, the combination of modest returns, fixed income benefits and limited growth potential raises concerns about its suitability as a long-term wealth-creation solution.
Investors should carefully compare the plan with alternative investment avenues before committing to such a long-term product.
11. Pramerica Life Poorna Rakshak Vs. Other Investments
The returns offered by the Pramerica Life Poorna Rakshak Plan may not be sufficient to beat inflation over the long term.
Investors seeking better wealth-creation potential may consider separating their insurance and investment needs.
A pure term insurance policy can provide the required protection at a relatively lower cost, while the remaining amount can be invested in suitable market-linked instruments.
This approach can potentially improve both returns and liquidity.
Pramerica Life Poorna Rakshak Vs. Pure-Term + Equity Mutual Fund
Consider the same annual outlay of ₹1 lakh used in the Pramerica Life Poorna Rakshak illustration.
Instead of investing the entire amount in the bundled plan, ₹10,800 is allocated towards a pure term insurance policy providing a Sum Assured of ₹11 lakh, with a 10-year premium payment term and a 25-year policy term.
The remaining ₹89,200 per year is invested to build wealth and generate income.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 11,00,000 |
| Policy Term | 25 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 10,800 |
| Investment | ₹ 89,200 |
For the investment component, an equity mutual fund is considered.
At the end of 17 years, the investment grows to approximately ₹38.75 lakh.
After considering capital gains tax, the post-tax corpus is approximately ₹35.18 lakh.
This amount is then reinvested in an instrument assumed to generate an annual return of 7%.
| Age | Year | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 35 | 1 | -1,00,000 | 11,00,000 |
| 36 | 2 | -1,00,000 | 11,00,000 |
| 37 | 3 | -1,00,000 | 11,00,000 |
| 38 | 4 | -1,00,000 | 11,00,000 |
| 39 | 5 | -1,00,000 | 11,00,000 |
| 40 | 6 | -1,00,000 | 11,00,000 |
| 41 | 7 | -1,00,000 | 11,00,000 |
| 42 | 8 | -1,00,000 | 11,00,000 |
| 43 | 9 | -1,00,000 | 11,00,000 |
| 44 | 10 | -1,00,000 | 11,00,000 |
| 45 | 11 | 0 | 11,00,000 |
| 46 | 12 | 0 | 11,00,000 |
| 47 | 13 | 0 | 11,00,000 |
| 48 | 14 | 0 | 11,00,000 |
| 49 | 15 | 0 | 11,00,000 |
| 50 | 16 | 0 | 11,00,000 |
| 51 | 17 | 0 | 11,00,000 |
| 52 | 18 | 0 | 11,00,000 |
| 53 | 19 | 2,98,750 | 11,00,000 |
| 54 | 20 | 2,98,750 | 11,00,000 |
| 55 | 21 | 2,98,750 | 11,00,000 |
| 56 | 22 | 2,98,750 | 11,00,000 |
| 57 | 23 | 2,98,750 | 11,00,000 |
| 58 | 24 | 2,98,750 | 11,00,000 |
| 59 | 25 | 2,98,750 | 11,00,000 |
| 60 | 32,78,899 | ||
| IRR | 9.23% |
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 17 years | 38,75,742 |
| Purchase price | 8,92,000 |
| Long-Term Capital Gains | 29,83,742 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 28,58,742 |
| Tax paid on LTCG | 3,57,343 |
| Maturity value after tax | 35,18,399 |
To replicate the annual Survival Benefit offered by the Pramerica Life Poorna Rakshak Plan, an annual withdrawal of ₹2,98,750 is made from this corpus.
After accounting for these withdrawals, the remaining corpus is eventually withdrawn in full.
Based on these cash flows, the overall IRR works out to approximately 9.23%.
The illustration highlights the potential advantage of keeping insurance and investments separate.
If the withdrawals are deferred and the corpus is allowed to compound for a longer period, the accumulated wealth could be significantly higher.
At the same time, this approach provides greater liquidity, flexibility and control, as the investor can decide when and how much to withdraw based on actual financial requirements rather than following a predetermined payout structure.
Thus, instead of combining protection and investment in a single product, investors may find it more effective to buy adequate term insurance for protection and invest the balance separately for wealth creation.
12. Final Verdict on Pramerica Life Poorna Rakshak
The Pramerica Life Poorna Rakshak Plan combines savings and life insurance, offering four plan variants designed to address different cash-flow requirements.
While the plan encourages disciplined savings and provides guaranteed benefits, it raises concerns on two important fronts: inflation-adjusted income and adequacy of life cover.
Although the payouts are guaranteed, the returns may not be attractive enough for long-term wealth creation.
The inability to defer income benefits under certain variants further limits flexibility, while the relatively low Sum Assured may not provide adequate financial protection for the family and it also has a high agent commission.
When both the protection and investment aspects are considered together, the plan may not offer sufficient value to justify committing to it for the long term.
Before starting an investment journey, it is important to first ensure adequate life insurance protection.
A pure-term insurance policy can provide substantial life cover at a relatively affordable premium, while the remaining surplus can be invested separately through a well-diversified portfolio based on the investor’s goals, risk profile and time horizon.
This approach can offer greater potential for wealth creation, liquidity and flexibility. Therefore, investors should carefully evaluate bundled insurance products rather than choosing them solely for their guaranteed income features.
For personalised guidance on insurance and investment planning, consider consulting a Certified Financial Planner.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
A professional can help structure a comprehensive financial plan that aligns your protection needs and investments with your risk appetite, investment horizon and long-term financial objectives.


Leave a Reply