 Listen to this article
Can the SUD Life Wealth Pro Plan truly help you build long-term wealth while protecting your family’s financial future, or do its charges and policy conditions limit its potential?
Does the SUD Life Wealth Pro Plan offer the right balance between market-linked investment growth and life insurance protection, or are there better alternatives available?
Is the SUD Life Wealth Pro Plan genuinely a smart wealth-building solution, or would separating life insurance and investments offer greater flexibility and value?
In this article, we take an in-depth look at the plan, examining its key features, benefits and drawbacks, supported by a detailed illustration to assess its potential as a wealth-creation tool.
Table of Contents:
What is the SUD Life Wealth Pro?
What are the features of the SUD Life Wealth Pro?
Who is eligible for the SUD Life Wealth Pro?
What are the benefits of the SUD Life Wealth Pro?
What are the investment strategies and fund options in the SUD Life Wealth Pro?
What are the charges in the SUD Life Wealth Pro?
Grace Period, Discontinuance and Revival of the SUD Life Wealth Pro
Free Look Period for the SUD Life Wealth Pro
Surrendering the SUD Life Wealth Pro
What are the advantages of the SUD Life Wealth Pro?
What are the disadvantages of the SUD Life Wealth Pro?
Research Methodology of SUD Life Wealth Pro
Benefit Illustration – IRR Analysis of SUD Life Wealth Pro
SUD Life Wealth Pro Vs. Other Investments
SUD Life Wealth Pro Plan vs. Pure-term + PPF/Equity Mutual Fund
Final Verdict on SUD Life Wealth Pro
What is the SUD Life Wealth Pro?
SUD Life Wealth Pro is an Individual Non-Participating Unit-linked Life Insurance Plan.
It combines life cover with market-linked growth opportunities, enabling efficient wealth creation. It facilitates disciplined investing while enhancing portfolio diversification.
What are the features of the SUD Life Wealth Pro?
- Offers two plan options to choose from: Growth PRO and Loyalty PRO.
- Zero Premium Allocation Charges.
- Return of Mortality Charges and Policy Administration Charges.
- Systematic Withdrawal Plan (SWP) facility to make regular withdrawals from the fund value during the SUD Life Wealth Pro Plan policy term to meet financial needs.
- Waiver of Premium benefit to ensure continued savings contributions even in the event of the policyholder’s death (under select variants).
- No charges for partial withdrawals or fund switching.
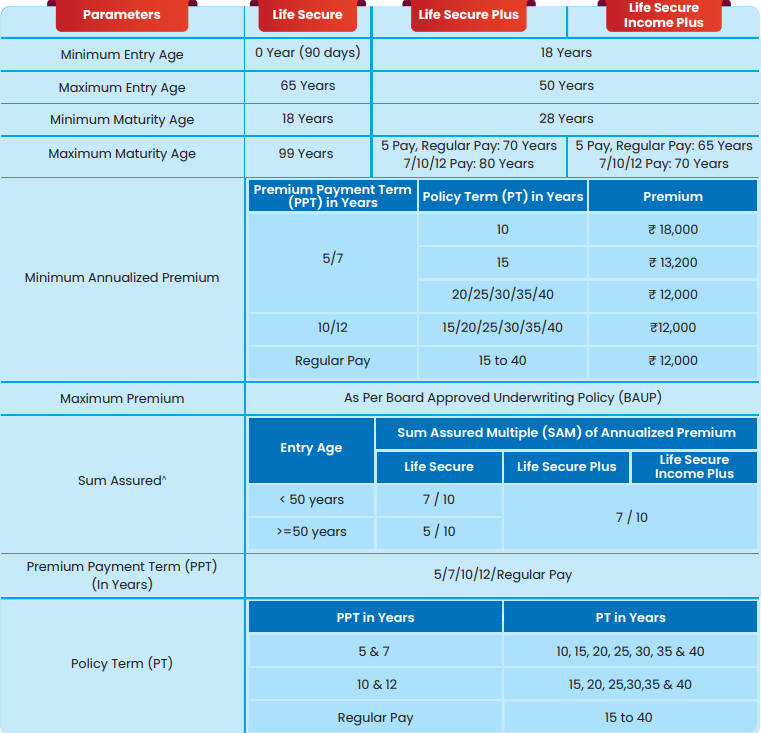
Who is eligible for the SUD Life Wealth Pro?
What are the benefits of the SUD Life Wealth Pro?
1. Death benefit
Life Secure
- Where the risk has commenced under the Policy:
The Death Benefit payable shall be the higher of:
- Sum Assured less relevant Partial Withdrawals; or
- Fund Value as on the date of intimation of death of the Life Assured after addition of Charges (if any) other than Fund Management Charges recovered subsequent to the date of death; or
- 105% of Total Premiums Paid
- Where the risk has not commenced under the Policy:
The Death Benefit payable shall be the higher of:
- Fund Value as on the date of intimation of death of the Life Assured after addition of Charges (if any) other than Fund Management Charges recovered subsequent to the date of death; or
- ii. 105% of Total Premiums Paid
Life Secure Plus
- Sum Assured, as specified in the SUD Life Wealth Pro Plan Policy Schedule, will be payable on intimation of death of the Life Assured, subject to the claims assessment;
- All future Premiums payable under the Policy, if any, after the date of death of the Life Assured, will be waived by the Company, provided the Policy is in force at the time of death;
- An amount equal to the modal/instalment Premium will be funded/credited in/to the Policyholder’s account on each future Premium due date(s);
- Fund Value, post adding Return of Policy Administration Charges, if any, at the prevailing NAV as on Maturity Date, will be payable to the Beneficiary/Claimant.
- Applicable Charges like Policy Administration Charges, Fund Management Charges etc. as detailed in Charges section will continue to be levied as and when due. The total Death Benefit will not be less than 105% of Total Premiums Paid by the Policyholder
Life Secure Income Plus
- Sum Assured, as specified in the Policy Schedule, will be payable on intimation of death of the Life Assured, subject to the claims assessment;
- All future Premiums payable under the SUD Life Wealth Pro Plan Policy, if any, after the date of death of the Life Assured, will be waived by the Company provided the Policy is in force at the time of death;
- An amount equal to the modal/instalment Premium will be funded/credited in/to the Policyholder’s account on each future Premium due date (s);
- During the intermediate period, the Company will pay Monthly Income instalments equal to 1% of the Sum Assured
- Fund Value post adding Return of Policy Administration Charges, if any, at the prevailing NAV as on Maturity Date will be payable to the Beneficiary/Claimant.
- Applicable Charges like Policy Administration Charges, Fund Management Charges, etc. as detailed in the Charges section will continue to be levied as and when due
2. Maturity Benefit
On survival of the Life Assured till the end of the policy term, provided the SUD Life Wealth Pro Plan policy is in force, the Fund Value calculated at the prevailing NAV as on the maturity date will be paid to the policyholder along with the Return of Mortality Charges (RoMC), if applicable, and Return of Policy Administration Charges (RoPAC), if applicable. The Policy will terminate on the maturity date.
3. Return of Charges
Return of Mortality Charge (RoMC): On survival of the Life Assured till the end of the Policy Term, on the Maturity Date, the total amount of Mortality Charges deducted (excluding any extra Mortality Charge, applicable taxes and taxes levied on Mortality Charge deducted, if any) in respect of the life cover provided throughout the Policy Term will be added back as RoMC to the Fund Value at different times during the Policy Term.
Return of Policy Administration Charge (RoPAC) (Applicable under plan option Loyalty PRO): The policy administration charges shall be returned by way of addition to the fund value. The charges will be added to the fund value, subject to the policyholder surviving at the time of the addition of the charges. The total of policy administration charges deducted for the first policy year shall be added back to the fund value at the end of the 5th Policy year. The administration charges deducted from the remaining policy year shall be added back to the fund value at the end of the SUD Life Wealth Pro Plan policy term.
What are the investment strategies and fund options in the SUD Life Wealth Pro?
A. Self-Managed Investment Strategy:
This strategy enables the policyholder to manage the investments actively.
Under this strategy, SUD Life Wealth Pro Plan policyholders can choose to invest the money in any of the following fund options in proportions of his/ her choice. Policyholders can switch money among these funds using the switch option.
| Asset Allocation | ||||||
| S no | Fund Name | Equity, Preference Shares and Convertible Debentures | Debt Instruments | Money Market Instruments | Mutual Fund & Fixed Deposit | Risk Profile |
| 1 | Blue Chip Equity Fund | 70-100% | 0 | 0-30% | 0-30% | High |
| 2 | Growth Plus Fund | 40-100% | 0-60% | 0-30% | 0-30% | Medium to High |
| 3 | Balanced Plus Fund | 0-60% | 40-100% | 0-30% | 0-30% | Low to Medium |
| 4 | Mid-Cap Fund | 70-100% | 0 | 0-30% | 0-30% | Very High |
| 5 | Income Fund | 0 | 0-70% | 0-30% | 0-30% | Low to Medium |
| 6 | Gilt Fund | 0 | 60-100% | 0-40% | 0-40% | Low to Medium |
| 7 | Dynamic Fund | 10-95% | 10-95% | 0-80% | 0-15% | High |
| 8 | Money Market Fund | 0 | 0 | 85-100% | 0-15% | Low |
| 9 | New India Leaders Fund | 80-100% | 0 | 0-20% | 0 | High |
| 10 | Viksit Bharat Fund | 80-100% | 0 | 0-20% | 0 | High |
| 11 | SUD Life Midcap Momentum Index Fund | 80-100% | 0 | 0-20% | 0 | High |
| 12 | SUD Life Nifty Alpha 50 Index Fund | 80-100% | 0 | 0-20% | 0 | High |
| Equity, Preference Shares and Convertible Debentures | Money Market Instruments | Government Securities | ||||
| Discontinued Policies Fund | 0 | 0-40% | 60-100% | |||
B. Age-Based Investment Strategy:
At policy inception, based on the risk preference (aggressive or conservative) of the policyholder, the investments are distributed between two funds, Blue Chip Equity Fund and Gilt Fund, based on the age.
As the life insured moves from one age band to another, the funds are redistributed based on the attained age.
The age-wise portfolio distribution for both risk preferences is shown in the table.
| Aggressive | Conservative | |||
| Attained age of Life Assured (years) | Blue Chip Equity Fund | Gilt Fund | Blue Chip Equity Fund | Gilt Fund |
| Up to 30 | 80% | 20% | 60% | 40% |
| 31-40 | 70% | 30% | 50% | 50% |
| 41-50 | 60% | 40% | 40% | 60% |
| 51-55 | 50% | 50% | 30% | 70% |
| 56-60 | 40% | 60% | 20% | 80% |
| 61-65 | 30% | 70% | 10% | 90% |
| 66-75 | 20% | 80% | 0% | 100% |
What are the charges in the SUD Life Wealth Pro?
i. Premium Allocation Charges:
Nil
ii. Policy Administration Charges: (Applicable only for Plan Option: Loyalty PRO):
Policy Administration Charge of 0.25% of annualised premium per month, with a maximum cap of Rs. 500, shall be deducted in advance on the first working day of every policy month by cancellation of units at the prevailing unit rates.
iii. Fund Management Charges:
| S no | Fund Name | Annual Rate of FMC |
| 1 | BlueChip Equity Fund | 1.35% |
| 2 | Growth Plus Fund | 1.35% |
| 3 | Balanced Plus Fund | 1.30% |
| 4 | Income Fund | 1.30% |
| 5 | Mid Cap Fund | 1.35% |
| 6 | Gilt Fund | 1.30% |
| 7 | Dynamic Fund | 1.35% |
| 8 | Money Market Fund | 1.00% |
| 9 | Viksit Bharat Fund | 1.35% |
| 10 | New India Leaders Fund | 1.35% |
| 11 | SUD Life Midcap Momentum Index Fund | 1.30% |
| 12 | SUD Life Nifty Alpha 50 Index Fund | 1.35% |
| Discontinued Policies Fund | 0.50% |
iv. Surrender/Discontinuance Charges:
It depends on the year of discontinuance and the annualised premium. There are no surrender or discontinuance charges after the 5th policy year.
v. Switching Charges:
All switches will be free of cost.
vi. Partial Withdrawal Charges:
All Partial withdrawals, including SWP, are free of cost.
vii. Mortality Charges:
The Company will levy mortality charges on the Sum at Risk for providing life cover to the Life Assured.
Mortality charges are recovered on a monthly basis, on the first working day of each policy month, by way of cancellation of the appropriate number of units
viii. Waiver of Premium Charges: (WoP) (Applicable for Death Benefit Options- Life Secure Plus & Life Secure Income Plus):
Waiver of Premium charges is recovered on a monthly basis, on the first working day of each policy month, by way of cancellation of the appropriate number of units.
ix. Monthly Income Charges: (for Death Benefit Option: Life Secure Income Plus):
Monthly Income charges are recovered on a monthly basis, on the first working day of each policy month, by way of cancellation of the appropriate number of units
Inference from the charges: The charges imposed under this plan act as an additional burden on the investor. Unlike most equity-based investment avenues that have minimal or no such costs, these charges can steadily chip away at your returns over time, reducing the overall wealth you could have accumulated.
Grace Period, Discontinuance and Revival of the SUD Life Wealth Pro
Grace Period
The company gives you a grace period of 30 days for yearly/half-yearly/quarterly modes and 15 days for monthly modes to pay the due premium.
Discontinuance
Discontinuance of Policy within the Lock-in Period of the First Five Years: Your policy will acquire discontinuance status. The fund value after deducting the applicable discontinuance charges shall be transferred to the discontinued policy fund, and the risk cover under the policy shall cease. At the end of the lock-in period, the proceeds of the discontinuance policy fund will be paid to the Policyholder, and the policy will terminate immediately.
Discontinuance of Policy after the Lock-in Period: The policy shall be converted into a reduced paid-up policy and will continue with the paid-up sum assured, i.e. original sum assured multiplied by the total number of premiums paid to the original number of premiums payable as per the terms and conditions of the policy.
Revival
The policy can be revived within the revival period of three years.
Free Look Period for the SUD Life Wealth Pro
If you disagree with any of those terms or conditions in the SUD Life Wealth Pro Plan policy, you have an option to return the policy to us within the free look period, i.e. 30 days from the date of receipt of the policy document.
Surrendering the SUD Life Wealth Pro
On surrender of the policy during the lock-in period: The SUD Life Wealth Pro Plan Policy will be discontinued, and no risk cover will be available during the discontinued period. Upon receipt of such a request, the fund value, less the applicable discontinuance charge, shall be transferred to the Discontinued Policies Fund, and the proceeds of the policy shall be paid to the policyholder at the end of the lock-in period. Surrender
After the Lock-in Period: When the policy is surrendered after completion of the lock-in period of five policy years, the surrender value, which is equal to the fund value as on the date of surrender, shall be paid to the policyholder
What are the advantages of the SUD Life Wealth Pro?
- Under the Loyalty PRO option, loyalty additions are credited to the fund from the end of the 6th policy year until the completion of the policy term.
- Partial withdrawals are permitted from the 6th policy year onwards or once the Life Assured attains 18 years of age, whichever is later.
- The Systematic Withdrawal Plan (SWP) facility allows policyholders to withdraw funds at pre-determined intervals to meet their financial needs.
- Settlement Option for Death Benefit: Available under the Life Secure Death Benefit Option, allowing the beneficiary to receive the death benefit in instalments.
- Policyholders can redirect future premiums to different funds and switch their existing investments between available fund options.
What are the disadvantages of the SUD Life Wealth Pro?
- The plan does not offer a top-up facility to make additional investments during the policy term.
- No policy loan facility is available against the accumulated fund value.
- The sum assured may be inadequate to meet the family’s life insurance protection needs.
- Premiums are invested only after deducting applicable charges, reducing the amount available for investment.
- The fund value remains locked in for the first five policy years, limiting liquidity.
- Overall returns may be less attractive compared to alternative investment avenues.
Research Methodology of SUD Life Wealth Pro
Evaluating the potential returns is an important step before investing in any market-linked product. In this section, we analyse the SUD Life Wealth Pro Plan using the benefit illustration provided in the SUD Life Wealth Pro Plan policy brochure.
This will help assess its wealth-creation potential and compare it with alternative investment avenues.
Benefit Illustration – IRR Analysis of SUD Life Wealth Pro
A 35-year-old male purchases the SUD Life Wealth Pro Plan with a Sum Assured of ₹10 lakh. The policy term is 30 years, while the premium-paying term is 10 years, with an annual premium of ₹1 lakh.
| Male | 35 years |
| Sum Assured | ₹ 10,00,000 |
| Policy Term | 30 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 1,00,000 |
On surviving the policy term, the SUD Life Wealth Pro Plan policyholder receives the accumulated fund value, provided all premiums are paid as scheduled.
The brochure illustrates two assumed investment return scenarios of 4% p.a. and 8% p.a. These are indicative rates and are not guaranteed returns.
- At 4% assumed return: The fund value at maturity is ₹19.31 lakh, translating into an IRR of just 2.60% as per the SUD Life Wealth Pro Plan maturity calculator.
- At 8% assumed return: The fund value increases to ₹51.17 lakh, generating an IRR of 6.54% as per the SUD Life Wealth Pro Plan maturity calculator.
| At 4% p.a. | At 8% p.a. | ||||
| Age | Year | Annualised premium / Maturity benefit | Death benefit | Annualised premium / Maturity benefit | Death benefit |
| 35 | 1 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 36 | 2 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 37 | 3 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 38 | 4 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 39 | 5 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 40 | 6 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 41 | 7 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 42 | 8 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 43 | 9 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 44 | 10 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 45 | 11 | 0 | 10,00,000 | 0 | 10,00,000 |
| 46 | 12 | 0 | 10,00,000 | 0 | 10,00,000 |
| 47 | 13 | 0 | 10,00,000 | 0 | 10,00,000 |
| 48 | 14 | 0 | 10,00,000 | 0 | 10,00,000 |
| 49 | 15 | 0 | 10,00,000 | 0 | 10,00,000 |
| 50 | 16 | 0 | 10,00,000 | 0 | 10,00,000 |
| 51 | 17 | 0 | 10,00,000 | 0 | 10,00,000 |
| 52 | 18 | 0 | 10,00,000 | 0 | 10,00,000 |
| 53 | 19 | 0 | 10,00,000 | 0 | 10,00,000 |
| 54 | 20 | 0 | 10,00,000 | 0 | 10,00,000 |
| 55 | 21 | 0 | 10,00,000 | 0 | 10,00,000 |
| 56 | 22 | 0 | 10,00,000 | 0 | 10,00,000 |
| 57 | 23 | 0 | 10,00,000 | 0 | 10,00,000 |
| 58 | 24 | 0 | 10,00,000 | 0 | 10,00,000 |
| 59 | 25 | 0 | 10,00,000 | 0 | 10,00,000 |
| 60 | 26 | 0 | 10,00,000 | 0 | 10,00,000 |
| 61 | 27 | 0 | 10,00,000 | 0 | 10,00,000 |
| 62 | 28 | 0 | 10,00,000 | 0 | 10,00,000 |
| 63 | 29 | 0 | 10,00,000 | 0 | 10,00,000 |
| 64 | 30 | 0 | 10,00,000 | 0 | 10,00,000 |
| 65 | 19,31,419 | 51,17,238 | |||
| IRR | 2.60% | 6.54% | |||
Even under the higher 8% return assumption, the plan’s returns are not particularly attractive when compared with alternative market-linked investment options that offer better long-term wealth-creation potential.
Moreover, a Sum Assured of ₹10 lakh provides inadequate life insurance protection for most families.
Apart from its modest return potential and insufficient life cover, the plan also raises concerns regarding transparency in fund management and the impact of various charges on investment returns.
These limitations considerably weaken its suitability as a long-term wealth-creation solution.
SUD Life Wealth Pro Vs. Other Investments
Any market-linked investment should ideally generate returns that beat inflation over the long term.
However, as seen in the earlier illustration, the SUD Life Wealth Pro Plan does not offer particularly attractive returns.
To understand its effectiveness as a wealth-creation tool, let us compare it with alternative investment strategies using the same investment assumptions.
SUD Life Wealth Pro Plan vs. Pure-term + PPF/Equity Mutual Fund
The SUD Life Wealth Pro Plan provides a life cover of ₹10 lakh along with market-linked investment exposure.
For a like-for-like comparison, let us consider a pure-term insurance policy with a Sum Assured of ₹10 lakh, a policy term of 30 years and a premium-paying term of 10 years. The annual premium is ₹12,500.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 10,00,000 |
| Policy Term | 30 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 12,500 |
| Investment | ₹ 87,500 |
By opting for pure-term insurance, the remaining ₹87,500 per year can be invested separately.
Depending on your risk appetite, you can choose between low-risk debt instruments and higher-risk equity investments. Let us examine both alternatives.
| Term Insurance + PPF | Term insurance + Equity Mutual Fund | ||||
| Age | Year | Term Insurance premium + PPF | Death benefit | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 35 | 1 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 36 | 2 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 37 | 3 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 38 | 4 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 39 | 5 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 40 | 6 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 41 | 7 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 42 | 8 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 43 | 9 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 44 | 10 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 45 | 11 | 0 | 10,00,000 | 0 | 10,00,000 |
| 46 | 12 | 0 | 10,00,000 | 0 | 10,00,000 |
| 47 | 13 | 0 | 10,00,000 | 0 | 10,00,000 |
| 48 | 14 | 0 | 10,00,000 | 0 | 10,00,000 |
| 49 | 15 | 0 | 10,00,000 | 0 | 10,00,000 |
| 50 | 16 | 0 | 10,00,000 | 0 | 10,00,000 |
| 51 | 17 | 0 | 10,00,000 | 0 | 10,00,000 |
| 52 | 18 | 0 | 10,00,000 | 0 | 10,00,000 |
| 53 | 19 | 0 | 10,00,000 | 0 | 10,00,000 |
| 54 | 20 | 0 | 10,00,000 | 0 | 10,00,000 |
| 55 | 21 | 0 | 10,00,000 | 0 | 10,00,000 |
| 56 | 22 | 0 | 10,00,000 | 0 | 10,00,000 |
| 57 | 23 | 0 | 10,00,000 | 0 | 10,00,000 |
| 58 | 24 | 0 | 10,00,000 | 0 | 10,00,000 |
| 59 | 25 | 0 | 10,00,000 | 0 | 10,00,000 |
| 60 | 26 | 0 | 10,00,000 | 0 | 10,00,000 |
| 61 | 27 | 0 | 10,00,000 | 0 | 10,00,000 |
| 62 | 28 | 0 | 10,00,000 | 0 | 10,00,000 |
| 63 | 29 | 0 | 10,00,000 | 0 | 10,00,000 |
| 64 | 30 | 0 | 10,00,000 | 0 | 10,00,000 |
| 65 | 51,27,107 | 1,46,40,781 | |||
| IRR | 6.55% | 10.91% | |||
1. Low-Risk Strategy – Public Provident Fund (PPF)
The investment schedule has been suitably adjusted to comply with the minimum 15-year investment period applicable to PPF.
By investing the surplus amount in PPF, the accumulated maturity value after 30 years works out to ₹51.27 lakh, translating into an IRR of 6.55% (tax-free).
Despite being a low-risk investment option, PPF delivers returns that match or exceed the SUD Life Wealth Pro Plan’s projected returns under the 8% illustration. This is achieved without exposure to equity market volatility or the additional charges associated with a ULIP.
2. High-Risk Strategy – Equity Mutual Funds
Investors with a higher risk appetite can consider equity mutual funds for long-term wealth creation.
Under this strategy, the projected pre-tax maturity value is ₹1.65 crore, while the post-tax maturity value, after accounting for LTCG tax, works out to ₹1.46 crore. This translates into a post-tax IRR of 10.91%.
Like ULIPs, equity mutual funds are market-linked investments. However, they offer greater transparency in portfolio disclosure, better liquidity and flexibility in investment and withdrawal decisions.
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 30 years | 1,65,89,464 |
| Purchase price | 8,75,000 |
| Long-Term Capital Gains | 1,57,14,464 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 1,55,89,464 |
| Tax paid on LTCG | 19,48,683 |
| Maturity value after tax | 1,46,40,781 |
The SUD Life Wealth Pro Plan falls short in terms of return potential, liquidity and transparency. Even its higher assumed return scenario does not provide a compelling advantage over alternative investment avenues.
Separating insurance and investment through a pure-term insurance policy combined with a suitable investment strategy offers better life protection, potentially higher returns and greater financial flexibility.
This approach also allows investors to choose investments based on their risk appetite and financial goals, making it a more efficient way to approach long-term financial planning.
Final Verdict on SUD Life Wealth Pro
The SUD Life Wealth Pro Plan is a typical Unit-Linked Insurance Plan (ULIP) that combines life insurance coverage with market-linked investment options.
It offers three death benefit options: a basic death benefit, a death benefit with a premium waiver benefit, and a combination of death benefit, premium waiver and monthly income benefit.
However, these additional benefits come at the cost of higher premium allocations, leaving a smaller portion of your money available for investment.
Although the plan offers multiple investment strategies and fund choices, the actual diversification is limited. Most of the available funds follow similar asset allocation patterns, restricting the scope for meaningful portfolio customisation.
One of the major drawbacks is its inability to generate attractive inflation-adjusted returns, primarily due to the impact of various charges and it also has a high agent commission.
This could affect your ability to accumulate the required corpus for important financial goals. Furthermore, the Sum Assured is inadequate, making the plan less appealing as both an investment and a life protection solution.
When it comes to financial protection, it is generally more efficient to keep insurance and investments separate.
A pure-term insurance policy provides adequate life cover at a relatively low cost, allowing the remaining funds to be invested in suitable instruments based on your financial goals, investment horizon and risk appetite.
Before committing to any financial product, carefully evaluate its costs, potential returns, liquidity and suitability for your financial objectives.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
Consulting a Certified Financial Planner (CFP) can help you make informed decisions and develop an investment strategy aligned with your goals, risk tolerance and time horizon.
Leave a Comment