 Listen to this article
Can the ABSLI Nishchit Aayush – Her Nishchit Plan truly provide women with lasting financial security, or do its benefits come with important limitations?
Does the ABSLI Nishchit Aayush – Her Nishchit Plan offer the right combination of financial protection and long-term benefits, or are there better alternatives available?
Is the ABSLI Nishchit Aayush – Her Nishchit Plan a smart financial choice for women, or could its features and restrictions limit its overall value?
In this context, is investing your savings in the ABSLI Nishchit Aayush – Her Nishchit Plan the right strategy? Designed to combine life insurance with regular income for women, this article examines whether the plan offers meaningful financial benefits and supports a woman’s long-term financial goals.
Table of Contents:
What is the ABSLI Nishchit Aayush – Her Nishchit?
What are the features of the ABSLI Nishchit Aayush – Her Nishchit?
Who is eligible for the ABSLI Nishchit Aayush – Her Nishchit?
What are the benefits of the ABSLI Nishchit Aayush – Her Nishchit?
Grace Period, Discontinuance and Revival of the ABSLI Nishchit Aayush – Her Nishchit
Free Look Period for the ABSLI Nishchit Aayush – Her Nishchit
Surrendering the ABSLI Nishchit Aayush – Her Nishchit
What are the advantages of the ABSLI Nishchit Aayush – Her Nishchit?
What are the disadvantages of the ABSLI Nishchit Aayush – Her Nishchit?
Research Methodology for ABSLI Nishchit Aayush – Her Nishchit
Benefit Illustration – IRR Analysis of ABSLI Nishchit Aayush – Her Nishchit
ABSLI Nishchit Aayush – Her Nishchit Vs. Other Investments
ABSLI Nishchit Aayush – Her Nishchit Vs. Pure-term + Equity Mutual Fund
Final Verdict on ABSLI Aayush Nishchit – Her Nishchit
What is the ABSLI Nishchit Aayush – Her Nishchit?
ABSLI Nishchit Aayush – Her Nishchit is a Non-Linked, Non-Participating, Individual Savings Life Insurance Plan.
It provides life insurance cover with guaranteed regular income and lump sum benefits, empowering you to fulfil your goals and financially secure your family even in your absence
What are the features of the ABSLI Nishchit Aayush – Her Nishchit?
- Choice of Benefit Option: Select between Long Term Income and Whole Life Income.
- Guaranteed Regular Income: Receive guaranteed income after the deferment period until the end of the policy term.
- Flexible Plan Customisation: Choose the income benefit, income variant, premium payment term, policy term, and deferment period to suit your needs.
- Choice of Income Variant: Opt for Level Income or Increasing Income.
- Guaranteed Maturity Benefit: Receive a guaranteed lump sum at the end of the policy term.
- Life Insurance Protection: Enjoy life cover throughout the policy term.
Who is eligible for the ABSLI Nishchit Aayush – Her Nishchit?
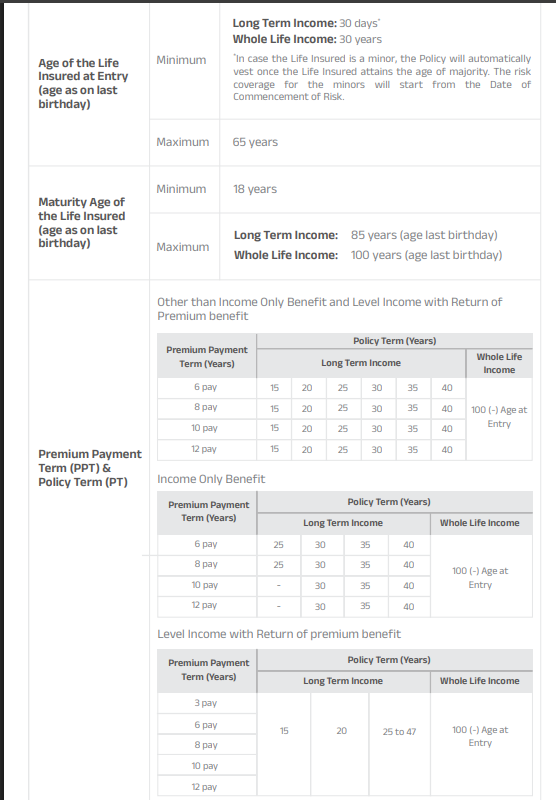
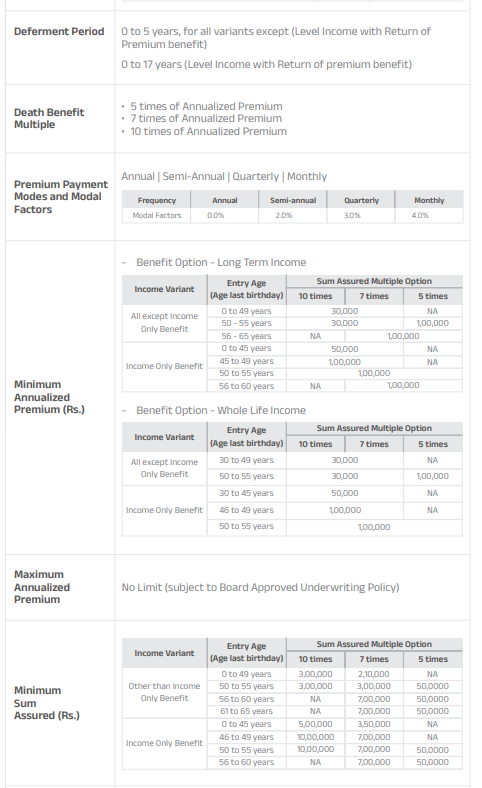
What are the benefits of the ABSLI Nishchit Aayush – Her Nishchit?
1. Death benefits
In the unfortunate event of Death of the Life Insured at any time during the ABSLI Nishchit Aayush – Her Nishchit Plan Policy Term, provided the Policy is in force, Death Benefit shall be payable as a lump sum to the nominee. Death Benefit is defined as the higher of:
- Sum Assured on Death
- Surrender Benefit
Where, ‘Sum Assured on Death’ is the higher of
- Sum Assured
- 105% of Total Premiums Paid till date of death
Sum Assured is a multiple of the Annualised Premium.
The ABSLI Nishchit Aayush – Her Nishchit Plan Policyholder can choose one of the following Sum Assured Multiples at policy inception-
- 5 times of Annualised Premium
- 7 times of Annualised Premium
- 10 times of Annualised Premium
2. Survival benefit
On Survival of the life insured, provided all due premiums have been paid, Survival Benefit in the form of Guaranteed Income will be paid at the end of each year starting from the first policy year (if ‘0 Year’ deferment is chosen) until Policy Maturity.
Level Income with Lump Sum Benefit/Level Income with Enhanced Lump Sum Benefit / Level Income with Return of Premium / Income Only Benefit:
Income Benefit is expressed as a percentage of Annualised Premium.
Income Benefit varies by Benefit Option, Income Variant, Deferment Period, Premium Payment Term, Policy Term, Life Insured’s Age at inception of the policy, Sum Assured Multiple and Annualised Premium.
Increasing Income with Lump Sum Benefit:
Under this option, Income benefit payout will increase at a simple interest rate of 5% every 5 years from the policy commencement date, as per the deferment option chosen.
3. Maturity benefit
On survival of the life insured till the end of the ABSLI Nishchit Aayush – Her Nishchit Plan policy term, Guaranteed Lump Sum Benefit (GLB) is payable.
Guaranteed Lump Sum Benefit is equal to Total Premiums Paid by You multiplied by the applicable Lump Sum Factor. The lump sum Factor varies by Benefit Option, Income Variant, Premium Payment Term, and Policy Term.
Grace Period, Discontinuance and Revival of the ABSLI Nishchit Aayush – Her Nishchit
Grace Period
In case the premium is not paid by the due date, you will be given a Grace Period of thirty (30) days from the due date for payment of each premium for all premium paying modes except for the monthly mode, where a grace period of only fifteen (15) days will be allowed.
Discontinuance
Discontinuance of Payment of Premium before the Policy has acquired surrender value: the Policy shall lapse w.e.f. the due date of unpaid premium, and all benefits under the policy, including the insurance cover, shall cease and no benefits shall be payable.
Discontinuance of Payment of Premium after the Policy has acquired surrender value: the Policy shall become a Reduced Paid Up (RPU) Policy; however, you will have the option to revive the Policy within 5 years from the due date of first unpaid premium.
Revival
You can revive your Policy within a revival period of five years from the due date of the first unpaid premium.
Free Look Period for the ABSLI Nishchit Aayush – Her Nishchit
You will have the right to return your ABSLI Nishchit Aayush – Her Nishchit Plan Policy within 30 days from the date of receipt of the Policy, in case you disagree with the terms & conditions of your Policy.
The company will refund the premium paid upon receipt of written notice of cancellation (along with reasons thereof) together with the original Policy document from your end.
Surrendering the ABSLI Nishchit Aayush – Her Nishchit
You can surrender the ABSLI Nishchit Aayush – Her Nishchit Plan policy any time during the Policy Term after the policy has acquired a Surrender Value. Your policy will acquire a Surrender Value, provided all due premiums for at least one full policy year are paid.
Where the Policyholder opts to surrender the policy in the first policy year, the Surrender Value payable will be equal to the Special Surrender Value.
The Surrender Value shall become payable immediately after receipt of the first full year’s premium, for a Premium Payment Term of less than 5 years.
However, where all the due instalment premiums for the first two policy years have been received, the Surrender Value payable will be equal to the higher of Guaranteed Surrender Value and Special Surrender Value.
What are the advantages of the ABSLI Nishchit Aayush – Her Nishchit?
- Death Benefit Payout Flexibility: The nominee can choose to receive the death benefit in monthly or annual instalments over five years instead of as a lump sum.
- Optional Riders: Additional rider benefits can be added to the base policy for enhanced coverage.
- Policy Loan Facility: A loan can be availed against the policy, subject to a minimum amount of ₹5,000 and a maximum of 80% of the applicable surrender value.
What are the disadvantages of the ABSLI Nishchit Aayush – Her Nishchit?
- Inadequate Life Cover: The sum assured may be insufficient to provide adequate financial protection for your family’s long-term needs.
- Limited Wealth Creation: Regular survival benefit payouts reduce the amount available for compounding, potentially limiting long-term wealth accumulation.
- Relatively Low Returns: The plan may deliver modest returns compared with other long-term investment options offering similar or lower levels of risk.
Research Methodology for ABSLI Nishchit Aayush – Her Nishchit
From a liquidity perspective, the ABSLI Nishchit Aayush – Her Nishchit Plan offers guaranteed annual survival benefits along with a guaranteed maturity payout.
However, to evaluate its investment potential, it is important to assess the Internal Rate of Return (IRR) rather than focusing solely on the guaranteed benefits.
Benefit Illustration – IRR Analysis of ABSLI Nishchit Aayush – Her Nishchit
Consider a 35-year-old woman paying an annual premium of ₹1,00,000 for 12 years under the Long Term Income Option (Level Income with Lump Sum Benefit). The policy term is 40 years, with a sum assured of ₹10 lakhs.
Starting at the end of the first policy year, she receives a guaranteed annual survival benefit of ₹38,050 throughout the applicable payout period.
At the end of the policy term, she also receives a guaranteed lump-sum maturity benefit of ₹24 lakhs.
| Female | 35 years |
| Sum Assured | ₹ 10,00,000 |
| Policy Term | 40 years |
| Premium Paying Term | 12 years |
| Annualised Premium | ₹ 1,00,000 |
| Age | Year | Annualised premium / Maturity benefit | Death benefit |
| 35 | 1 | -1,00,000 | 10,00,000 |
| 36 | 2 | -61,950 | 10,00,000 |
| 37 | 3 | -61,950 | 10,00,000 |
| 38 | 4 | -61,950 | 10,00,000 |
| 39 | 5 | -61,950 | 10,00,000 |
| 40 | 6 | -61,950 | 10,00,000 |
| 41 | 7 | -61,950 | 10,00,000 |
| 42 | 8 | -61,950 | 10,00,000 |
| 43 | 9 | -61,950 | 10,00,000 |
| 44 | 10 | -61,950 | 10,00,000 |
| 45 | 11 | -61,950 | 10,00,000 |
| 46 | 12 | -61,950 | 10,00,000 |
| 47 | 13 | 38,050 | 10,00,000 |
| 48 | 14 | 38,050 | 10,00,000 |
| 49 | 15 | 38,050 | 10,00,000 |
| 50 | 16 | 38,050 | 10,00,000 |
| 51 | 17 | 38,050 | 10,00,000 |
| 52 | 18 | 38,050 | 10,00,000 |
| 53 | 19 | 38,050 | 10,00,000 |
| 54 | 20 | 38,050 | 10,00,000 |
| 55 | 21 | 38,050 | 10,00,000 |
| 56 | 22 | 38,050 | 10,00,000 |
| 57 | 23 | 38,050 | 10,00,000 |
| 58 | 24 | 38,050 | 10,00,000 |
| 59 | 25 | 38,050 | 10,00,000 |
| 60 | 26 | 38,050 | 10,00,000 |
| 61 | 27 | 38,050 | 10,00,000 |
| 62 | 28 | 38,050 | 10,00,000 |
| 63 | 29 | 38,050 | 10,00,000 |
| 64 | 30 | 38,050 | 10,00,000 |
| 65 | 31 | 38,050 | 10,00,000 |
| 66 | 32 | 38,050 | 10,00,000 |
| 67 | 33 | 38,050 | 10,00,000 |
| 68 | 34 | 38,050 | 10,00,000 |
| 69 | 35 | 38,050 | 10,00,000 |
| 70 | 36 | 38,050 | 10,00,000 |
| 71 | 37 | 38,050 | 10,00,000 |
| 72 | 38 | 38,050 | 10,00,000 |
| 73 | 39 | 38,050 | 10,00,000 |
| 74 | 40 | 38,050 | 10,00,000 |
| 75 | 24,38,050 | ||
| IRR | 5.39% |
Despite these guaranteed benefits, the policy delivers an IRR of just 5.39% as per the ABSLI Nishchit Aayush – Her Nishchit Plan maturity calculator over the 40-year term. This is relatively modest for such a long investment horizon.
The recurring survival benefit payouts limit the amount that remains invested for compounding, thereby restricting the potential for long-term wealth accumulation.
Consequently, the income stream and maturity proceeds may not be sufficient to meet significant future financial goals, particularly after accounting for inflation.
Considering its modest returns and limited wealth creation potential, the ABSLI Nishchit Aayush – Her Nishchit Plan may not be an ideal choice for those seeking long-term capital appreciation or effective goal-based financial planning.
ABSLI Nishchit Aayush – Her Nishchit Vs. Other Investments
Although the ABSLI Nishchit Aayush – Her Nishchit Plan offers guaranteed benefits, its long-term returns may struggle to keep pace with inflation.
Combined with its relatively low life cover, the plan may not be an efficient choice for either wealth creation or financial protection. A more effective strategy is to separate insurance from investments.
ABSLI Nishchit Aayush – Her Nishchit Vs. Pure-term + Equity Mutual Fund
For life insurance protection, a pure-term insurance policy provides higher life cover at a relatively lower premium, leaving more money available for investment.
Conservative investors may consider instruments such as PPF, while those with a longer investment horizon and higher risk tolerance may consider diversified equity mutual funds.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 10,00,000 |
| Policy Term | 35 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 12,600 |
| Investment | ₹ 87,400 |
Consider the same illustration. A pure-term policy providing a sum assured of ₹10 lakh costs approximately ₹12,600 annually, with a 35-year policy term and a 10-year premium-paying term.
Compared with the annual premium of ₹1,00,000 under the ABSLI Nishchit Aayush Plan, this leaves ₹87,400 available for investment during the premium-paying period.
| Term insurance + Equity Mutual Fund | |||
| Age | Year | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 35 | 1 | -1,00,000 | 10,00,000 |
| 36 | 2 | -61,950 | 10,00,000 |
| 37 | 3 | -61,950 | 10,00,000 |
| 38 | 4 | -61,950 | 10,00,000 |
| 39 | 5 | -61,950 | 10,00,000 |
| 40 | 6 | -61,950 | 10,00,000 |
| 41 | 7 | -61,950 | 10,00,000 |
| 42 | 8 | -61,950 | 10,00,000 |
| 43 | 9 | -61,950 | 10,00,000 |
| 44 | 10 | -61,950 | 10,00,000 |
| 45 | 11 | -61,950 | 10,00,000 |
| 46 | 12 | -61,950 | 10,00,000 |
| 47 | 13 | 38,050 | 10,00,000 |
| 48 | 14 | 38,050 | 10,00,000 |
| 49 | 15 | 38,050 | 10,00,000 |
| 50 | 16 | 38,050 | 10,00,000 |
| 51 | 17 | 38,050 | 10,00,000 |
| 52 | 18 | 38,050 | 10,00,000 |
| 53 | 19 | 38,050 | 10,00,000 |
| 54 | 20 | 38,050 | 10,00,000 |
| 55 | 21 | 38,050 | 10,00,000 |
| 56 | 22 | 38,050 | 10,00,000 |
| 57 | 23 | 38,050 | 10,00,000 |
| 58 | 24 | 38,050 | 10,00,000 |
| 59 | 25 | 38,050 | 10,00,000 |
| 60 | 26 | 38,050 | 10,00,000 |
| 61 | 27 | 38,050 | 10,00,000 |
| 62 | 28 | 38,050 | 10,00,000 |
| 63 | 29 | 38,050 | 10,00,000 |
| 64 | 30 | 38,050 | 10,00,000 |
| 65 | 31 | 38,050 | 10,00,000 |
| 66 | 32 | 38,050 | 10,00,000 |
| 67 | 33 | 38,050 | 10,00,000 |
| 68 | 34 | 38,050 | 10,00,000 |
| 69 | 35 | 38,050 | 10,00,000 |
| 70 | 36 | 38,050 | 10,00,000 |
| 71 | 37 | 38,050 | 10,00,000 |
| 72 | 38 | 38,050 | 10,00,000 |
| 73 | 39 | 38,050 | 10,00,000 |
| 74 | 40 | 38,050 | 10,00,000 |
| 75 | 61,59,830 | ||
| IRR | 7.41% | ||
For a meaningful comparison, let us account for the guaranteed annual income of ₹38,050 offered by the insurance plan.
Under the alternative strategy, ₹38,050 is treated as the annual cash flow available to the investor, leaving ₹49,350 (₹87,400 − ₹38,050) to be invested annually in a diversified equity mutual fund.
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 12 years | 15,12,046 |
| Purchase price | 6,55,450 |
| Long-Term Capital Gains | 8,56,596 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 7,31,596 |
| Tax paid on LTCG | 91,449 |
| Maturity value after tax | 14,20,596 |
Based on the assumed returns, these investments could grow to approximately ₹15.12 lakh at the end of 12 years. After accounting for capital gains tax, the estimated post-tax corpus of ₹14.20 lakh can be transferred to a debt instrument earning an assumed annual return of 7%.
This corpus can then support annual withdrawals comparable to the plan’s guaranteed income while retaining the potential to accumulate a larger final corpus.
Under this alternative strategy, the projected corpus at the end of the 40-year period could reach approximately ₹61.59 lakh, compared with the ₹24 lakh maturity benefit under the ABSLI Nishchit Aayush Plan.
Separating insurance from investments can offer several advantages: Higher wealth creation potential, Adequate life protection, Greater liquidity, flexibility and Goal-oriented planning.
Final Verdict on ABSLI Aayush Nishchit – Her Nishchit
The ABSLI Nishchit Aayush – Her Nishchit Plan offers multiple variants combining guaranteed income with maturity benefits, providing predictable cash flows that are not subject to market fluctuations.
However, guaranteed benefits alone do not ensure the achievement of long-term financial goals.
Despite being positioned to address women’s life insurance needs, the plan is essentially a traditional money-back policy with guaranteed benefits.
A long-term financial commitment spanning 30–40 years should ideally generate returns that help preserve purchasing power against inflation.
However, the plan’s relatively modest returns may limit corpus growth and make it challenging to meet rising future expenses and it also has a high agent commission.
The early commencement of survival benefits also reduces the amount available for compounding, while the life cover may be insufficient to adequately protect a family’s long-term financial needs.
Life insurance protection is essential for women, but it need not be bundled with investments. A pure-term life insurance policy can provide adequate financial protection at a significantly lower premium, leaving more savings available for investment.
These savings can be allocated to a diversified portfolio based on individual risk tolerance, investment horizon, and financial goals.
This approach offers greater flexibility, better wealth creation potential, and more effective goal-based financial planning.
Before committing to any long-term financial product, evaluate more than just its guaranteed benefits.
Consider its potential to generate inflation-beating returns, the adequacy of its life cover, its liquidity, and its ability to support your financial goals.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
A Certified Financial Planner can help you develop a personalised strategy that balances financial protection, liquidity, and long-term wealth creation.
Leave a Comment