


 Listen to this article
Can the Bajaj Life Smart Wealth Goal VII – Wealth Variant truly accelerate your long-term wealth creation, or do its charges and conditions tell a different story?
Does the Bajaj Life Smart Wealth Goal VII – Wealth Variant offer the right combination of market-linked growth and life protection, or are there better alternatives available?
Is the Bajaj Life Smart Wealth Goal VII – Wealth Variant a smart way to build wealth, or would separating insurance and investment provide greater flexibility?
This article takes a closer look at the plan and evaluates its potential returns through a detailed illustration.
Table of Contents:
What is the Bajaj Life Smart Wealth Goal VII?
What are the features of the Bajaj Life Smart Wealth Goal VII?
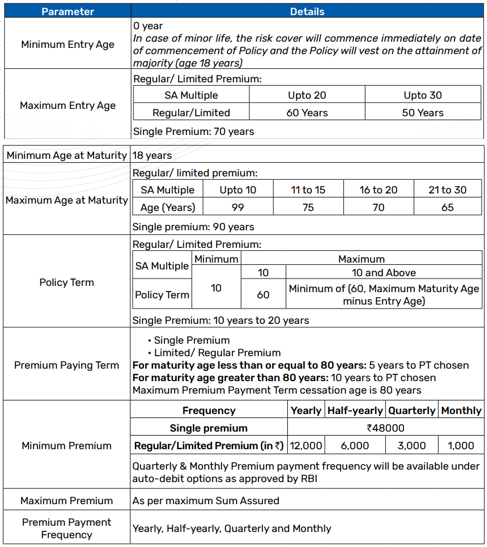
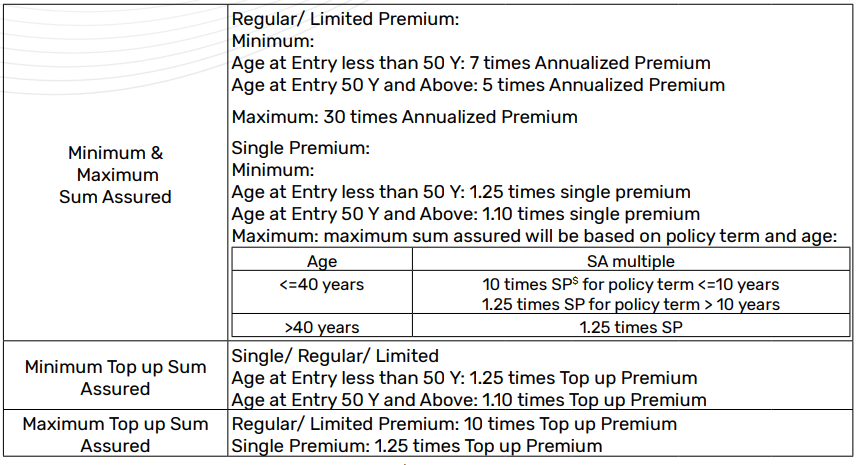
Who is eligible for the Bajaj Life Smart Wealth Goal VII?
What are the benefits of the Bajaj Life Smart Wealth Goal VII?
What are the investment strategies and fund options in the Bajaj Life Smart Wealth Goal VII?
What are the charges of the Bajaj Life Smart Wealth Goal VII?
Grace Period, Discontinuance and Revival of the Bajaj Life Smart Wealth Goal VII
Free Look Period for the Bajaj Life Smart Wealth Goal VII
Surrendering the Bajaj Life Smart Wealth Goal VII
What are the advantages of the Bajaj Life Smart Wealth Goal VII?
What are the disadvantages of the Bajaj Life Smart Wealth Goal VII?
Research Methodology of Bajaj Life Smart Wealth Goal VII
Benefit Illustration – IRR Analysis of Bajaj Life Smart Wealth Goal VII
Bajaj Life Smart Wealth Goal VII Vs. Other Investments
Bajaj Life Smart Wealth Goal VII Vs. Pure-Term + PPF/Equity Mutual Fund
Final Verdict on Bajaj Life Smart Wealth Goal VII
What is the Bajaj Life Smart Wealth Goal VII?
Bajaj Life Smart Wealth Goal VII is a non-participating, life, individual, Unit-Linked single and limited/regular premium payment plan.
This plan is loaded with features like Life cover, multiple investment strategies, and Return of Life Cover charge to make the most of your savings.
What are the features of the Bajaj Life Smart Wealth Goal VII?
- Fund Booster: Additional allocation to the fund value starting from the 15th policy year.
- Return of Mortality Charge (ROMC): Mortality charges may be returned at maturity if the policy term is more than 15 years.
- Instalment Option: Maturity or death benefits can be received in instalments, along with a Return Enhancer.
- Investment Choice: Five investment portfolio strategies are available, along with multiple funds to choose from.
- Premium Reduction: Option to reduce the regular or limited premium, subject to the policy terms.
- Premium-Paying Term: Option to change the premium-paying term, subject to applicable conditions.
- Tax Benefits: Tax benefits may be available as per the prevailing tax laws.
Who is eligible for the Bajaj Life Smart Wealth Goal VII?
What are the benefits of the Bajaj Life Smart Wealth Goal VII?
1. Maturity benefit
Provided the Bajaj Life Smart Wealth Goal VII Policy is in force, and the Life Assured is alive, the Maturity Benefit will be the Fund value as on the date of maturity of your Policy.
2. Death benefit
The Death Benefit payable will be
Higher of,
- Prevailing Sum Assured or
- Regular Premium Fund Value/Single Premium Fund Value
plus
Higher of,
- Prevailing Top-up Sum Assured or
- Top-up Premium Fund value, if any.
The Death Benefit payable is subject to the Guaranteed Benefit of 105% of the Total Premiums paid till the date of death.
3. Fund Booster
For Limited/Regular Premium: At the end of the 15th policy year and every 5th policy year thereafter till PT (maximum till 60th policy year), Fund Booster 2% of the Average of the daily Regular Premium Fund value during the previous 3 years (including the current year) will be added to the Fund.
For Single Premium: At the end of the 15th policy year and every 5th policy year thereafter till PT, Fund Booster 2% (15th year) / 3% (thereafter) of the average of the daily single premium fund values during the previous 3 years (including the current year) will be added to the Fund.
Return of Mortality Charge (ROMC): For a Policy Term greater than 15, the total amount of mortality charges deducted in respect of life cover provided throughout the Bajaj Life Smart Wealth Goal VII Policy term will be added back as ROMC to the Fund value on the date of maturity of your Policy.
Additional Allocation (Applicable only for Regular/Limited Premium Policies): During the first policy year, 1.08% of each modal Premium paid by you will be added to your Regular Premium Fund Value at the time of allocation of each premium
What are the investment strategies and fund options in the Bajaj Life Smart Wealth Goal VII?
Bajaj Life Smart Wealth Goal VII provides you with five unique portfolio strategies, out of which any one can be chosen at the inception of your Policy:
- Investor Selectable Portfolio Strategy
- Wheel of Life Portfolio Strategy II
- Trigger-Based Portfolio Strategy II
- Auto Transfer Portfolio Strategy
- Capital Preservation-Oriented Strategy
A. Investor Selectable Portfolio Strategy:
If you want to allocate your Premiums based on your personal choice and decision, you can opt for this Investment Strategy and choose from among the Funds below to suit your investment needs.
| S.no | Fund Name | Equity | Debt | Money Market | Risk profile |
| 1 | Equity Growth Fund II | Not less than 60% | 0% – 40% | 0% – 40% | Very High |
| 2 | Accelerator Mid-Cap Fund II | Not less than 60% (at least 50% in Mid cap) | 0% – 40% | 0% – 40% | Very High |
| 3 | Pure Stock Fund | Not less than 60% | 0% – 40% | 0% – 40% | Very High |
| 4 | Pure Stock Fund II | Not less than 75% | — | 0% -25% | Very High |
| 5 | Asset Allocation Fund II | 40% – 90% | 0% – 60% | 0% – 50% | High |
| 6 | Blue-chip Equity Fund | Not less than 60% | 0% – 40% | 0% – 40% | High |
| 7 | Bond Fund | — | 40% – 100% | 0% – 60% | Moderate |
| 8 | Liquid Fund | — | — | 100% | Low |
| 9 | Flexi Cap Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 10 | Sustainable Equity Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 11 | Small Cap Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 12 | Dynamic Asset Allocation Fund | 10% 90% | 10% 90% | 0% – 80% | High |
| 13 | Individual Short-Term Debt Fund | — | 40% – 100% | 0% – 60% | Moderate |
| 14 | Midcap Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 15 | SmallCap Quality Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 16 | Nifty Alpha 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 17 | Nifty 200 Alpha 30 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 18 | Nifty 200 Momentum 30 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 19 | Nifty 500 Multicap Momentum Quality 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 20 | Focused 25 Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 21 | Nifty 500 Multifactor 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 22 | BSE 500 Enhanced Value 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 23 | BSE 500 Dividend Leaders 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 24 | India Consumption Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 25 | Pure Stock Innovation Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 26 | BSE 500 Quality 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 27 | Opportunities Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 28 | Nifty 500 Low Volatility 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 29 | Nifty 200 Value 30 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 30 | BSE 500 Momentum Value 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
B. Wheel of Life Portfolio Strategy – II:
In this Portfolio Strategy, at the commencement of the Policy, the Regular/Limited Premium and the top-up Premium, if any, would be allocated to the Funds mentioned (namely Equity Growth Fund II, Accelerator Mid-Cap Fund II, Bond Fund & Liquid Fund) in the proportion as mentioned in the table below, depending on the outstanding years to maturity.
| Proportion in Following Funds | |||||
| Years to Maturity | Equity Growth Fund II | Accelerator Mid-Cap Fund II | Bond Fund | Liquid Fund | Total |
| 10 & above | 40% | 45% | 15% | 0% | 100% |
| 9 | 35% | 50% | 15% | 0% | 100% |
| 8 | 30% | 55% | 15% | 0% | 100% |
| 7 | 25% | 60% | 15% | 0% | 100% |
| 6 | 25% | 60% | 15% | 0% | 100% |
| 5 | 20% | 65% | 15% | 0% | 100% |
| 4 | 20% | 55% | 15% | 10% | 100% |
| 3 | 20% | 50% | 15% | 15% | 100% |
| 2 | 10% | 30% | 30% | 30% | 100% |
| 1 | 0% | 0% | 35% | 65% | 100% |
C. Trigger-Based Portfolio Strategy II:
Under this Portfolio Strategy, Regular/Limited Premiums and Top-up Premiums if any, will be allocated between two Funds, Equity Growth Fund II (an equity-oriented Fund), and Bond Fund (a debt-oriented Fund), in a 75%: 25% proportion. The Fund value proportions may subsequently get altered due to market movements.
Any appreciation over three times the value of units is considered a gain and is switched to the Liquid Fund.
Later, it will be switched to the Equity Growth Fund II and the Bond Fund such that, after the transfer, the ratio of the value of units in the Equity Growth Fund II to that in the Bond Fund is restored to 75%:25%.
D. Auto Transfer Portfolio Strategy:
This strategy helps you to invest your money systematically by automatically transferring your money every month, from a low-risk Fund to the Fund(s) of your choice.
In this Portfolio Strategy, your Premium will be allocated to the Bond Fund and/or Liquid Fund, as specified by you.
At the start of each monthly anniversary of the Policy, a proportion (as mentioned below) of Fund value in the Bond Fund and/or Liquid Fund as on that date will be switched to the other Fund/s (available in the plan) as specified by you.
The proportion of Fund value = 1/ Outstanding no. of months till the next premium due date.
E. Capital Preservation-Oriented Strategy:
The objective of the strategy is to optimise risk and return by investing across five pre-determined Funds, which are a mix of very high to low-risk Funds, in such a way that the monies invested over the years along with the accumulated returns are subjected to lesser market volatility, in the years closer to maturity.
Under this strategy, at the commencement of the Bajaj Life Smart Wealth Goal VII policy, the Regular Premium and the Top-Up premium, if any, would be allocated to the Funds mentioned (namely Equity Growth Fund II, Accelerator Mid-Cap Fund II, Pure Stock Fund II, Bond Fund & Liquid Fund) in the proportion as mentioned in the table below.
| Proportion in Following Funds | ||||||
| Years to Maturity | Equity Growth Fund II | Accelerator Mid-Cap Fund II | Pure Stock Fund II | Bond Fund | Liquid Fund | Total |
| 10 & above | 40% | 15% | 15% | 30% | 0% | 100% |
| 9 | 35% | 15% | 15% | 35% | 0% | 100% |
| 8 | 30% | 15% | 15% | 40% | 0% | 100% |
| 7 | 30% | 15% | 15% | 40% | 0% | 100% |
| 6 | 30% | 10% | 15% | 45% | 0% | 100% |
| 5 | 25% | 10% | 15% | 40% | 10% | 100% |
| 4 | 20% | 5% | 10% | 40% | 25% | 100% |
| 3 | 15% | 0% | 5% | 40% | 40% | 100% |
| 2 | 0% | 0% | 0% | 40% | 60% | 100% |
| 1 | 0% | 0% | 0% | 0% | 100% | 100% |
What are the charges of the Bajaj Life Smart Wealth Goal VII?
i. Premium Allocation Charge:
Nil
ii. Policy Administration Charge:
| Year 1 – 5 | 1.08% of Annualised Premium |
| Year 6 – 10 | 3% p.a. of the prevailing annualized Premium |
| 11th year onward | NIL |
| Single Premium | Year 6 – 10: 0.5% p.a. of the Single Premium |
iii. Fund Management Charge:
| Fund Name | Fund Management Charge |
| Equity Growth Fund II | 1.35% |
| Accelerator Mid-Cap Fund II | 1.35% |
| Pure Stock Fund | 1.35% |
| Pure Stock Fund II | 1.30% |
| Asset Allocation Fund II | 1.25% |
| Blue-chip Equity Fund | 1.25% |
| Flexi Cap Fund | 1.35% |
| Sustainable Equity Fund | 1.35% |
| Small Cap Fund | 1.35% |
| Dynamic Asset Allocation Fund | 1.35% |
| Individual Short Term Debt Fund | 0.95% |
| Liquid Fund | 0.95% |
| Bond Fund | 0.95% |
| Midcap Index Fund | 1.35% |
| SmallCap Quality Index Fund | 1.35% |
| Nifty Alpha 50 Index Fund | 1.35% |
| Nifty 200 Alpha 30 Index Fund | 1.35% |
| Nifty 200 Momentum 30 Index Fund | 1.35% |
| Nifty 500 Multicap Momentum Quality 50 Index Fund | 1.35% |
| Focused 25 Fund | 1.35% |
| Nifty 500 Multifactor 50 Index Fund | 1.35% |
| BSE 500 Enhanced Value 50 Index Fund | 1.35% |
| BSE 500 Dividend Leaders 50 Index Fund | 1.35% |
| India Consumption Fund | 1.35% |
| Pure Stock Innovation Fund | 1.35% |
| BSE 500 Quality 50 Index Fund | 1.35% |
| Opportunities Fund | 1.35% |
| Nifty 500 Low Volatility 50 Index Fund | 1.35% |
| Nifty 200 Value 30 Index Fund | 1.35% |
| BSE 500 Momentum Value 50 Index Fund | 1.35% |
| Discontinued Life Policy Fund | 0.50% |
iv. Miscellaneous Charge
A miscellaneous charge of Rs. 100 per transaction will be charged.
v. Discontinuance /Surrender Charge:
It depends on the Annual premium amount & the year of discontinuance or surrender. Theirs is no Discontinuance /Surrender Charge from the 5th policy year.
vi. Mortality Charge:
Mortality Charges will be deducted at each monthly anniversary by the cancellation of units. Female Life Assured will be eligible for an age setback of 3 years.
Inference from the charges: The Bajaj Life Smart Wealth Goal VII involves relatively high charges and limited transparency. In comparison, other market-linked investment options generally have lower and more clearly disclosed costs. This can make them a more cost-effective alternative to Bajaj Life Smart Wealth Goal VII.
Grace Period, Discontinuance and Revival of the Bajaj Life Smart Wealth Goal VII
(For Limited / Regular Premium Policies)
Grace period
A grace period of 30 days is available for yearly, half-yearly & quarterly premium payment frequency, and 15 days is available for monthly premium payment frequency from the due date of Regular/Limited Premium payment.
Discontinuance
On Discontinuance of Regular Premiums due during the first 5 Policy years, the Bajaj Life Smart Wealth Goal VII Policy will be converted to a Discontinued Life Policy and the Regular Premium Fund Value less the Discontinuance/Surrender charge along with Top-up Premium Fund Value, if any, will be transferred to the Discontinued Life Policy fund.
The Discontinuance Value shall be payable as the Surrender Benefit at the end of the lock-in period of five Policy years.
On Discontinuance of Regular Premiums due after the lock-in period of 5 Policy years, the Policy will be, immediately & automatically, converted to a Paid-up Policy.
The Paid-up Sum Assured will be the Sum Assured in the Policy multiplied by the proportion of the number of Regular Premiums paid to the number of Regular Premiums payable in the Policy.
Revival
A policy that has been discontinued or is paid up due to non-payment of premiums can only be revived within 3 years from the date of the first unpaid premium.
Free Look Period for the Bajaj Life Smart Wealth Goal VII
You will be provided a free look period of 30 days beginning from the date of receipt of the policy document, whether received electronically or otherwise, to review the terms and conditions of such policy except for those policies with tenure of less than a year.
In the event you disagree with any of the Bajaj Life Smart Wealth Goal VII policy terms or conditions, or otherwise and has not made any claim, you shall have the option to return the policy to the insurer for cancellation.
Surrendering the Bajaj Life Smart Wealth Goal VII
On surrender during the lock-in period, the Fund value, less the Discontinuance/ Surrender charge, as on the date of surrender, will be transferred to the Discontinued Life Policy Fund, and all risk covers and rider covers, if any, will cease immediately.
The option to revive the policy will not be available to such a surrendered policy. The Discontinued value as at the end of the lock-in period will be available to you as Surrender Value.
On surrender after the lock-in period, the Surrender Value available will be Regular Premium Fund value/ Single premium fund value, along with Top up Premium Fund value, if any, as on the date of surrender, and will be payable immediately.
What are the advantages of the Bajaj Life Smart Wealth Goal VII?
- Partial Withdrawals: You can make partial withdrawals any time after completing five policy years, subject to the applicable conditions.
- Retired Life Income: You can opt to receive a regular income through systematic partial withdrawals.
- Top-up Premiums: You can pay additional top-up premiums during the policy term, except during the last five policy years.
- Portfolio Switching: You can switch between five different portfolio strategies on any policy anniversary.
- Premium Flexibility: After completing five policy years, you can modify the premium-paying term and premium payment frequency, and reduce the premium, subject to the policy terms.
- Reduction in Sum Assured: You can reduce the Sum Assured applicable to the top-up premium.
- Maturity Benefit in Instalments: You can choose to receive the maturity benefit in instalments over a period of up to five years.
What are the disadvantages of the Bajaj Life Smart Wealth Goal VII?
- No Loan Facility: The plan does not provide a loan facility against the policy.
- Limited Fund Differentiation: The fund options have similar asset allocations, which makes the choice between them appear less meaningful.
- Unattractive Return of Charges: The return of charges may appear less attractive because it does not account for the time value of money.
- Limited Liquidity: The plan does not provide liquidity through partial withdrawals during the first five policy years.
Research Methodology of Bajaj Life Smart Wealth Goal VII
Estimating the potential returns of a market-linked product is important before investing.
The Internal Rate of Return (IRR) helps evaluate the annualised return generated by the investment and compare it with inflation and other investment options.
Let’s examine the IRR based on the benefit illustration provided in the policy brochure.
Benefit Illustration – IRR Analysis of Bajaj Life Smart Wealth Goal VII
Consider a 35-year-old male who purchases the Bajaj Life Smart Wealth Goal VII – Wealth Variant with a policy term of 20 years. He pays an annual premium of ₹1 lakh for 10 years and receives a Sum Assured of ₹10 lakhs.
| Male | 35 years |
| Sum Assured | ₹ 10,00,000 |
| Policy Term | 20 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 1,00,000 |
By paying the premiums as scheduled, he becomes eligible for benefits such as the return of allocation charges and Fund Booster, along with the fund value payable at maturity.
The 4% and 8% scenarios shown in the illustration are assumed rates of return and are not guaranteed.
| At 4% p.a. | At 8% p.a. | ||||
| Age | Year | Annualised premium / Maturity benefit | Death benefit | Annualised premium / Maturity benefit | Death benefit |
| 35 | 1 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 36 | 2 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 37 | 3 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 38 | 4 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 39 | 5 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 40 | 6 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 41 | 7 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 42 | 8 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 43 | 9 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 44 | 10 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 45 | 11 | 0 | 10,00,000 | 0 | 10,00,000 |
| 46 | 12 | 0 | 10,00,000 | 0 | 10,00,000 |
| 47 | 13 | 0 | 10,00,000 | 0 | 10,00,000 |
| 48 | 14 | 0 | 10,00,000 | 0 | 10,00,000 |
| 49 | 15 | 0 | 10,00,000 | 0 | 10,00,000 |
| 50 | 16 | 0 | 10,00,000 | 0 | 10,00,000 |
| 51 | 17 | 0 | 10,00,000 | 0 | 10,00,000 |
| 52 | 18 | 0 | 10,00,000 | 0 | 10,00,000 |
| 53 | 19 | 0 | 10,00,000 | 0 | 10,00,000 |
| 54 | 20 | 0 | 10,00,000 | 0 | 10,00,000 |
| 55 | 15,19,361 | 27,58,535 | |||
| IRR | 2.72% | 6.65% | |||
At a 4% return scenario, the illustrated maturity fund value is ₹15.19 lakhs, resulting in an IRR of 2.72% as per the Bajaj Life Smart Wealth Goal VII Plan maturity calculator.
At an 8% return scenario, the illustrated maturity fund value is ₹27.58 lakhs, resulting in an IRR of 6.65% as per the Bajaj Life Smart Wealth Goal VII Plan maturity calculator.
These IRRs should be considered in the context of inflation and the risk involved in market-linked investments.
The difference between the assumed fund returns and the investor’s actual IRR also highlights the impact of policy charges and other deductions on the overall outcome.
Therefore, the plan should be evaluated alongside alternative investment options before deciding whether it fits the investor’s financial goals.
Bajaj Life Smart Wealth Goal VII Vs. Other Investments
Let’s compare the Bajaj Life Smart Wealth Goal VII with alternative investment strategies using the same assumptions as in the earlier illustration.
Instead of combining insurance and investment in a single product, we can consider a separate term insurance policy and invest the remaining amount towards financial goals.
Bajaj Life Smart Wealth Goal VII Vs. Pure-Term + PPF/Equity Mutual Fund
A pure-term life insurance policy with a Sum Assured of ₹10 lakhs costs ₹7,500 annually for 20 years, with premiums payable for 10 years.
This leaves ₹92,500 per year from the ₹1 lakh annual budget, which can be invested separately based on the investor’s risk profile.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 10,00,000 |
| Policy Term | 20 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 7,500 |
| Investment | ₹ 92,500 |
For Low-Risk Investors — PPF
The Public Provident Fund (PPF) requires a minimum annual investment of ₹500 and has a 15-year tenure. The available investment amount is adjusted during the final years to align the cash flows with the comparison.
At maturity, the PPF corpus grows to ₹27.29 lakhs, resulting in an IRR of 6.58%. This is broadly comparable to the 6.65% IRR in the 8% illustrated scenario of Bajaj Life Smart Wealth Goal VII, despite PPF being a debt-oriented investment.
For High-Risk Investors — Equity Mutual Fund
If the same amount is invested in an equity mutual fund, assuming the return used in the illustration, the maturity value grows to ₹56.46 lakhs.
After accounting for capital gains tax, the post-tax value is ₹50.72 lakhs, resulting in an IRR of 10.74%.
| Term Insurance + PPF | Term insurance + ELSS | ||||
| Age | Year | Term Insurance premium + PPF | Death benefit | Term Insurance premium + ELSS | Death benefit |
| 35 | 1 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 36 | 2 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 37 | 3 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 38 | 4 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 39 | 5 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 40 | 6 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 41 | 7 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 42 | 8 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 43 | 9 | -1,00,000 | 10,00,000 | -1,00,000 | 10,00,000 |
| 44 | 10 | -97,500 | 10,00,000 | -1,00,000 | 10,00,000 |
| 45 | 11 | -500 | 10,00,000 | 0 | 10,00,000 |
| 46 | 12 | -500 | 10,00,000 | 0 | 10,00,000 |
| 47 | 13 | -500 | 10,00,000 | 0 | 10,00,000 |
| 48 | 14 | -500 | 10,00,000 | 0 | 10,00,000 |
| 49 | 15 | -500 | 10,00,000 | 0 | 10,00,000 |
| 50 | 16 | 0 | 10,00,000 | 0 | 10,00,000 |
| 51 | 17 | 0 | 10,00,000 | 0 | 10,00,000 |
| 52 | 18 | 0 | 10,00,000 | 0 | 10,00,000 |
| 53 | 19 | 0 | 10,00,000 | 0 | 10,00,000 |
| 54 | 20 | 0 | 10,00,000 | 0 | 10,00,000 |
| 55 | 27,29,733 | 50,72,011 | |||
| IRR | 6.58% | 10.74% | |||
| ELSS Tax Calculation | |
| Maturity value after 20 years | 56,46,584 |
| Purchase price | 9,25,000 |
| Long-Term Capital Gains | 47,21,584 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 45,96,584 |
| Tax paid on LTCG | 5,74,573 |
| Maturity value after tax | 50,72,011 |
This comparison highlights the potential benefit of keeping insurance and investments separate.
A term insurance policy can provide the required life cover, while the remaining funds can be invested separately according to the investor’s risk profile and financial goals.
Separate investments may also provide greater liquidity and flexibility than the policy structure.
Final Verdict on Bajaj Life Smart Wealth Goal VII
The Bajaj Life Smart Wealth Goal VII combines market-linked investments with life insurance and offers features such as Fund Boosters and the return of certain charges.
While the plan is positioned as a wealth accumulation solution, the illustrated returns may be lower than those available through other market-linked investment options.
This raises questions about whether the returns adequately compensate for the risks and charges involved.
For long-term investors, generating returns that can keep pace with inflation is important for preserving purchasing power and achieving financial goals.
Lower-than-expected returns can increase the amount required to achieve a goal or extend the time needed to reach it and it also has a high agent commission.
Therefore, the plan should be evaluated carefully as part of the investor’s overall financial plan.
An alternative approach is to use a standalone pure-term life insurance policy for life protection and invest the remaining surplus separately.
The investment can then be aligned with the financial goal, investment horizon, and risk profile. A well-diversified portfolio can provide greater flexibility in managing different financial goals.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
If making these decisions feels overwhelming, consulting a Certified Financial Planner can help. A customised financial plan can bring together insurance, investments, goals, and risk management based on your individual circumstances.


Leave a Reply