
 Listen to this article
Can the ICICI Life Guaranteed Indexed Pension Plan truly provide a dependable retirement income that keeps pace with rising living costs, or do its benefits come with important limitations?
Does the ICICI Life Guaranteed Indexed Pension Plan offer the financial security retirees need, or could inflation still erode the purchasing power of its pension payouts?
Is the ICICI Life Guaranteed Indexed Pension Plan a smart retirement planning solution, or could alternative investment strategies offer greater flexibility and long-term value?
But can the ICICI Life Guaranteed Indexed Pension Plan serve as a comprehensive retirement solution? Let us examine its features, benefits, limitations and potential returns to find out.
Table of Contents:
What is the ICICI Life Guaranteed Indexed Pension?
What are the features of the ICICI Life Guaranteed Indexed Pension?
Who is eligible for the ICICI Life Guaranteed Indexed Pension?
What are the plan options and their benefits of the ICICI Life Guaranteed Indexed Pension?
Life Annuity with Return of Balance Purchase Price
Life Annuity with Return of Purchase Price
Grace Period, Discontinuance and Revival of ICICI Life Guaranteed Indexed Pension
Free Look Period for the ICICI Life Guaranteed Indexed Pension
Surrendering the ICICI Life Guaranteed Indexed Pension
What are the advantages of the ICICI Life Guaranteed Indexed Pension?
What are the disadvantages of the ICICI Life Guaranteed Indexed Pension?
Research Methodology of ICICI Life Guaranteed Indexed Pension
Benefit Illustration – IRR Analysis of ICICI Life Guaranteed Pension Plan
ICICI Pru Guaranteed Indexed Pension Vs. Other Investments
ICICI Pru Guaranteed Indexed Pension Vs. Equity Mutual Fund
Final Verdict on the ICICI Life Guaranteed Indexed Pension Plan
What is the ICICI Life Guaranteed Indexed Pension?
ICICI Life Guaranteed Indexed Pension is a Non-Participating Non-Linked General Annuity Individual Savings Plan.
It is a retirement solution designed around your unique needs. This plan gives you the freedom to choose your retirement income that adapts to your risk appetite and financial goals.
What are the features of the ICICI Life Guaranteed Indexed Pension?
- Guaranteed lifelong income: Receive a fixed income throughout your lifetime.
- Index-linked additional income: Opportunity to earn additional income based on the performance of the publicly available NIFTY 50 TRI, under the Life Annuity with Return of Purchase Price option.
- Customisable income mix: Choose the proportion of guaranteed income and index-linked income based on your preference.
- Single or joint-life option: Receive income either for your lifetime or jointly with your spouse.
- Lump-sum payout option: Choose to receive future guaranteed income as a lump sum, subject to the plan’s terms and conditions.
- Flexi Save Wallet: Option to accumulate your income in the wallet instead of receiving regular payouts.
- Health and wellness benefits: Access health management and wellness services to support your healthcare needs.
Who is eligible for the ICICI Life Guaranteed Indexed Pension?
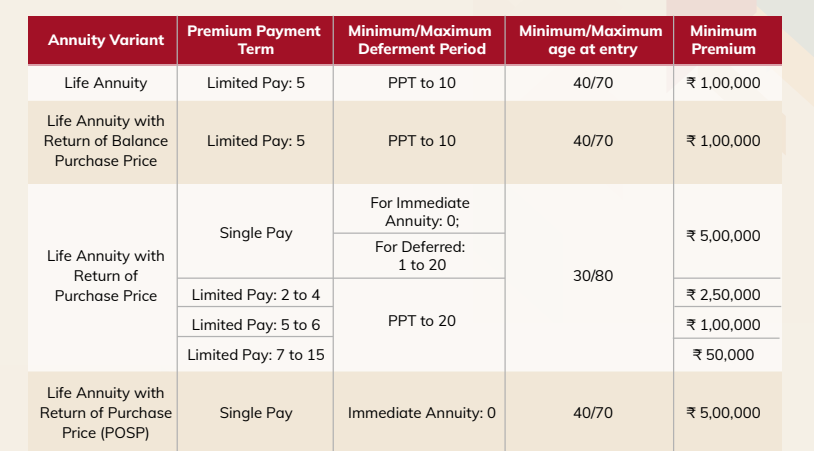
What are the plan options and their benefits of the ICICI Life Guaranteed Indexed Pension?
The ICICI Life Guaranteed Indexed Pension Plan offers 3 variants to choose from, as per your retirement needs:
- Life Annuity
- Life Annuity with Return of Balance Purchase Price
- Life Annuity with Return of Purchase Price
1. Life Annuity
For Single Life policies:
Annuity shall be paid for the life of the Annuitant.
In the event of death of the Annuitant during the Deferment Period, provided the ICICI Life Guaranteed Indexed Pension Plan Policy is in force or premium paying, the Death benefit payable by the Company to the Claimant shall be the higher of:
- 105% of Total Premiums Paid up to the date of death, or
- Surrender Value payable as on the date of death
In the event of death of the Annuitant after the Deferment period or under Immediate Annuity option, no death benefit would be payable by the Company.
For Joint Life policies:
Annuity is paid for life of the Primary Annuitant. In the event of the death of the Primary Annuitant, Annuity shall be payable for the life of the Secondary Annuitant.
Death benefit is payable only on death of the last surviving Annuitant
In the event of death of the last surviving Annuitant during the Deferment Period, then the Death Benefit payable by the Company to the Claimant shall be the higher of:
- 105% of Total Premiums Paid up to the date of death, or
- Surrender Value payable as on the date of death.
In the event of death of the last surviving Annuitant after the Deferment period or under Immediate Annuity option, no death benefit would be payable by the Company.
2. Life Annuity with Return of Balance Purchase Price
For Single Life policies:
Annuity shall be paid for the life of the Annuitant.
In the event of death of the Annuitant during the Deferment Period, provided the ICICI Life Guaranteed Indexed Pension Plan Policy is in force or premium paying, the Death benefit payable by the Company to the Claimant shall be the higher of
- 105% of Total Premiums Paid up to the date of death, or
- Surrender Value payable as on the date of death
In the event of death of the Annuitant after the Deferment Period for Deferred Annuity option or under Immediate Annuity option, Death Benefit payable by the Company to the Claimant shall be equal to Total Premiums Paid up to the date of death less all Annuities paid out till the date of death, subject to a minimum of zero.
For Joint Life policies:
Annuity is paid for life of the Primary Annuitant. In the event of the death of the Primary Annuitant, Annuity shall be payable for the life of the Secondary Annuitant.
Death benefit is payable only on death of the last surviving Annuitant.
In the event of death of the last surviving Annuitant during the Deferment Period, the Death Benefit payable by the Company to the Claimant shall be the higher of:
- 105% of Total Premiums Paid up to the date of death, or
- Surrender Value payable as on the date of death.
In the event of death of the last surviving Annuitant after the Deferment Period for Deferred Annuity option or under Immediate Annuity option, Death Benefit payable by the Company to the Claimant shall be equal to Total Premiums Paid up to the date of death of last surviving Annuitant less all Annuities paid out till the date of death, subject to a minimum of zero.
3. Life Annuity with Return of Purchase Price
Annuity Instalment = Guaranteed Annuity instalment + Variable Annuity instalment where,
Guaranteed Annuity Instalment will depend on the Guaranteed proportion chosen by You at inception and can range from 60% to 100%, in multiples of 10%.
Here, the Guaranteed Annuity Instalment amount will be calculated as Base Annuity Amount x Annuity Modal factor ÷ Annuity Frequency Factor.
Base Annuity Amount (BAA) is equal to the Annuity amount, payable annually in arrears, for a given Purchase Price (as applicable under the applicable Annuity variant), where such amount shall be computed as Base Annuity rate x Single or Annualised Premium payable under a policy, inclusive of high premium benefit and/or enhanced benefit, if applicable.
Variable annuity instalment will vary as per the returns of the Index. The applicable Index for benchmarking of variable annuity offering shall be NIFTY 50 Total Returns Index
For Single Life Policies:
Annuity shall be paid for the life of the Annuitant.
In the event of death of the Annuitant during the Deferment Period, the Death Benefit payable by the Company to the Claimant shall be the higher of
- 105% of Total Premiums Paid up to the date of death, or
- Surrender Value payable as on the date of death
In the event of death of the Annuitant after the Deferment Period for Deferred Annuity option or under the Immediate Annuity option, Death Benefit payable by the Company to the Claimant shall be equal to Total Premiums Paid up to the date of death of the Annuitant.
For Joint Life Policies:
Annuity is paid for life of the Primary Annuitant. In the event of the death of the Primary Annuitant, Annuity shall be payable for the life of the Secondary Annuitant.
Death benefit is payable only on death of the last surviving Annuitant.
In the event of death of the last surviving Annuitant during the Deferment Period, the Death Benefit payable by the Company to the Claimant shall be the higher of:
- 105% of Total Premiums Paid up to the date of death, or
- Surrender Value payable as on the date of death
In the event of death of the last surviving Annuitant after the Deferment Period for Deferred Annuity option or under Immediate Annuity option, Death Benefit payable by the Company to the Claimant shall be equal to Total Premiums Paid up to the date of death of last surviving Annuitant.
Grace Period, Discontinuance and Revival of ICICI Life Guaranteed Indexed Pension
Grace Period
If you are unable to pay an Instalment premium by the due date, you will be given a Grace Period of 15 days for payment of the due instalment premium if you have chosen monthly frequency, and 30 days for payment of the due instalment premium if you have chosen any other frequency, commencing from the premium date.
Discontinuance
If any Premium Instalment is not paid within the Grace Period before at least one full year’s Premium is paid, then the ICICI Life Guaranteed Indexed Pension Plan Policy shall lapse, and the insurance cover will cease. No benefits are payable under a lapsed Policy.
In case the lapsed policy is not revived by the end of the Revival Period, the Policy shall terminate, and no benefits will be payable.
For Limited Pay policies, if premium payment is discontinued before the end of the Premium Payment Term, but after you have paid at least one full year’s Premium, the ICICI Life Guaranteed Indexed Pension Plan Policy shall continue as a Reduced Paid-Up Policy with reduced benefits.
Revival
A Policy which has discontinued payment of Premium may be revived within 5 years from the due date of the first unpaid premium, or before the end of the Deferment Period, whichever is earlier.
Free Look Period for the ICICI Life Guaranteed Indexed Pension
On receipt of the Policy document, whether received electronically or otherwise, you have an option to review the ICICI Life Guaranteed Indexed Pension Plan Policy terms and conditions.
If you are not satisfied or have any disagreement with the terms and conditions of the Policy or otherwise and have not made any claim, the Policy document needs to be returned to the Company with reasons for cancellation of the Policy within 30 days from the date of receipt of the Policy document.
Surrendering the ICICI Life Guaranteed Indexed Pension
Single Pay Policies: You can surrender the Policy any time after the Date of commencement of the Policy.
Limited Pay Policies: You can surrender the policy any time after payment of at least one full Policy Year’s premium(s). Prior to receipt of one full year’s premium, no Surrender Value is payable.
The Surrender Value (if payable) shall be based on Guaranteed Surrender Value (GSV), wherever applicable, and Special Surrender Value (SSV).
What are the advantages of the ICICI Life Guaranteed Indexed Pension?
- Advance Annuity Option: You can receive a portion of your future Guaranteed Annuity payments as a lump sum instead of waiting for the respective payment due dates.
- Flexi Save Option: You can choose to accumulate your entire Annuity income with the Company rather than receiving it as regular payouts.
- Health and Wellness Services: Eligible Annuitants can access various health management and wellness services through service providers empanelled with the Company.
- Loan Facility: A loan facility is available only under the ‘Life Annuity with Return of Purchase Price’ variant and can be availed only during the deferment period.
What are the disadvantages of the ICICI Life Guaranteed Indexed Pension?
- Taxation of Annuity Income: The annuity income is fully taxable as per the applicable income tax provisions.
- Limited Surrender Facility: Surrender benefits are available only under select plan variants and are subject to restrictions.
- Restricted Loan Facility: The loan facility is available only under specific plan options and is subject to conditions.
- Uncertain Income Component: Under Plan Option 3, only a portion of the annuity income is guaranteed, while the remaining portion is linked to index performance. This may result in variations in your periodic income and affect cash flow planning.
Research Methodology of ICICI Life Guaranteed Indexed Pension
The ICICI Life Guaranteed Indexed Pension Plan offers three annuity options, including Single Life and Joint Life variants, with or without a return of the purchase price.
However, choosing a pension plan requires more than looking at its features.
It is important to evaluate the actual returns generated by the plan using the Internal Rate of Return (IRR) and compare them with other investment alternatives.
Benefit Illustration – IRR Analysis of ICICI Life Guaranteed Pension Plan
Let us consider a 50-year-old individual investing ₹10 lakh annually under Plan Option 3 – Life Annuity with 100% Return of Purchase Price.
The premium payment term is 5 years, followed by a deferment period of another 5 years.
| Male | 50 years |
| Sum Assured (Purchase Price) | ₹ 50,00,000 |
| Policy Term | Life Annuity after the deferment period |
| Premium Paying Term | 5 years |
| Annualised Premium | ₹ 10,00,000 |
Illustrative case study:
- Total premiums paid: ₹50 lakh
- Annual lifetime annuity: ₹3.57 lakh
- Guaranteed annuity proportion: 100%
- Assumed life expectancy: 85 years
- Return of purchase price to the nominee on death: ₹50 lakh
In this illustration, the individual opts for a 100% guaranteed annuity.
If a portion of the annuity is allocated to the index-linked component, the actual payouts will vary depending on the performance of the underlying index.
Based on the above cash flows and the assumed life expectancy, the plan generates an IRR of approximately 4.31% as per the ICICI Life Guaranteed Indexed Pension Plan maturity calculator.
| Age | Year | Annualised premium / Maturity benefit | Death benefit |
| 50 | 1 | -10,00,000 | 50,00,000 |
| 51 | 2 | -10,00,000 | 50,00,000 |
| 52 | 3 | -10,00,000 | 50,00,000 |
| 53 | 4 | -10,00,000 | 50,00,000 |
| 54 | 5 | -10,00,000 | 50,00,000 |
| 55 | 6 | 0 | 50,00,000 |
| 56 | 7 | 0 | 50,00,000 |
| 57 | 8 | 0 | 50,00,000 |
| 58 | 9 | 0 | 50,00,000 |
| 59 | 10 | 0 | 50,00,000 |
| 60 | 11 | 0 | 50,00,000 |
| 61 | 12 | 3,57,000 | 50,00,000 |
| 62 | 13 | 3,57,000 | 50,00,000 |
| 63 | 14 | 3,57,000 | 50,00,000 |
| 64 | 15 | 3,57,000 | 50,00,000 |
| 65 | 16 | 3,57,000 | 50,00,000 |
| 66 | 17 | 3,57,000 | 50,00,000 |
| 67 | 18 | 3,57,000 | 50,00,000 |
| 68 | 19 | 3,57,000 | 50,00,000 |
| 69 | 20 | 3,57,000 | 50,00,000 |
| 70 | 21 | 3,57,000 | 50,00,000 |
| 71 | 22 | 3,57,000 | 50,00,000 |
| 72 | 23 | 3,57,000 | 50,00,000 |
| 73 | 24 | 3,57,000 | 50,00,000 |
| 74 | 25 | 3,57,000 | 50,00,000 |
| 75 | 26 | 3,57,000 | 50,00,000 |
| 76 | 27 | 3,57,000 | 50,00,000 |
| 77 | 28 | 3,57,000 | 50,00,000 |
| 78 | 29 | 3,57,000 | 50,00,000 |
| 79 | 30 | 3,57,000 | 50,00,000 |
| 80 | 31 | 3,57,000 | 50,00,000 |
| 81 | 32 | 3,57,000 | 50,00,000 |
| 82 | 33 | 3,57,000 | 50,00,000 |
| 83 | 34 | 3,57,000 | 50,00,000 |
| 84 | 35 | 3,57,000 | 50,00,000 |
| 85 | 50,00,000 | ||
| IRR | 4.31% |
This return is relatively unattractive when compared with alternative investment avenues. Even a bank Fixed Deposit (FD) may potentially offer better returns along with greater liquidity.
Opting for an index-linked annuity component introduces additional uncertainty, and the actual returns may be lower than those illustrated under the 100% guaranteed annuity option.
Another major drawback is the limited liquidity. The premiums invested in the plan remain largely committed for the long term, restricting access to your accumulated funds when you need them.
Overall, the ICICI Life Guaranteed Indexed Pension Plan falls short in terms of both return potential and investment flexibility.
There are more efficient ways to build a retirement corpus and generate regular income while retaining better control over your investments. Let us explore some of these alternatives in the following section.
ICICI Pru Guaranteed Indexed Pension Vs. Other Investments
Let us examine an alternative investment strategy using the same assumptions as in our earlier illustration.
Under the ICICI Life Indexed Pension Plan, the death benefit payable during both the deferment period and the annuity phase is restricted to the total premiums paid.
Considering this limited life cover, we have excluded the insurance component from our comparison and assumed that the entire premium amount is invested towards retirement.
ICICI Pru Guaranteed Indexed Pension Vs. Equity Mutual Fund
The annual investment can be allocated across different asset classes based on the investor’s risk appetite.
Conservative investors may prefer low-risk options such as PPF, while those with a longer investment horizon and higher risk tolerance may consider equity mutual funds.
For this illustration, we assume that the annual premium is invested in an equity mutual fund to build a larger retirement corpus.
| Year | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 1 | -10,00,000 | 50,00,000 |
| 2 | -10,00,000 | 50,00,000 |
| 3 | -10,00,000 | 50,00,000 |
| 4 | -10,00,000 | 50,00,000 |
| 5 | -10,00,000 | 50,00,000 |
| 6 | 0 | 50,00,000 |
| 7 | 0 | 50,00,000 |
| 8 | 0 | 50,00,000 |
| 9 | 0 | 50,00,000 |
| 10 | 0 | 50,00,000 |
| 11 | 0 | 50,00,000 |
| 12 | 3,57,000 | 50,00,000 |
| 13 | 3,57,000 | 50,00,000 |
| 14 | 3,57,000 | 50,00,000 |
| 15 | 3,57,000 | 50,00,000 |
| 16 | 3,57,000 | 50,00,000 |
| 17 | 3,57,000 | 50,00,000 |
| 18 | 3,57,000 | 50,00,000 |
| 19 | 3,57,000 | 50,00,000 |
| 20 | 3,57,000 | 50,00,000 |
| 21 | 3,57,000 | 50,00,000 |
| 22 | 3,57,000 | 50,00,000 |
| 23 | 3,57,000 | 50,00,000 |
| 24 | 3,57,000 | 50,00,000 |
| 25 | 3,57,000 | 50,00,000 |
| 26 | 3,57,000 | 50,00,000 |
| 27 | 3,57,000 | 50,00,000 |
| 28 | 3,57,000 | 50,00,000 |
| 29 | 3,57,000 | 50,00,000 |
| 30 | 3,57,000 | 50,00,000 |
| 31 | 3,57,000 | 50,00,000 |
| 32 | 3,57,000 | 50,00,000 |
| 33 | 3,57,000 | 50,00,000 |
| 34 | 3,57,000 | 50,00,000 |
| 35 | 3,57,000 | 50,00,000 |
| 4,08,03,670 | ||
| IRR | 8.17% |
Illustrative investment outcome:
- Pre-tax corpus from equity mutual funds: ₹1.25 crore
- Post-tax corpus after capital gains tax: ₹1.16 crore
If the post-tax corpus is subsequently invested in an instrument generating an assumed return of 7% per annum, it can support annual withdrawals of ₹3.57 lakh while allowing the remaining corpus to grow.
Under this illustration, the corpus could potentially reach ₹4.08 crore by age 85.
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 10 years | 1,25,39,394 |
| Purchase price | 50,00,000 |
| Long-Term Capital Gains | 75,39,394 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 74,14,394 |
| Tax paid on LTCG | 9,26,799 |
| Maturity value after tax | 1,16,12,595 |
For comparison, we have considered a fixed annual withdrawal similar to the annuity received under the pension plan. However, this investment-led approach offers the flexibility to increase withdrawals over time to account for inflation.
The overall strategy generates an estimated IRR of 8.17%, significantly higher than the 4.31% IRR from the ICICI pension plan.
The biggest advantage of this approach is the flexibility it offers. The accumulated corpus can be used not only to generate regular retirement income but also to meet unexpected expenses, healthcare requirements and other financial goals, depending on the retiree’s priorities.
Further, following a diversified asset allocation strategy and periodically rebalancing the portfolio can help manage investment risk and generate inflation-adjusted retirement income.
This allows retirees to preserve their purchasing power over the long term.
In contrast, the ICICI Pru Guaranteed Indexed Pension Plan offers relatively lower return potential and restricts access to the accumulated funds through its annuity structure.
Therefore, a well-planned investment-led retirement strategy may prove more effective in achieving financial independence, maintaining flexibility and meeting long-term retirement goals.
Final Verdict on the ICICI Life Guaranteed Indexed Pension Plan
The ICICI Life Guaranteed Indexed Pension Plan aims to encourage retirement savings and provide a regular income during retirement.
While the plan follows a two-stage structure involving accumulation and annuity payouts, its return potential may not be sufficient to meet long-term retirement objectives effectively.
The plan offers certain features, such as the flexibility to choose the proportion of guaranteed and index-linked annuity income, along with options to advance or accumulate future annuity payments.
However, a closer examination of these features raises questions about their practical usefulness. The index-linked component depends on the company’s chosen investment approach, offering limited control to the annuitant.
Similarly, the options to discount or accumulate annuity payments may provide limited additional value to retirees who require a predictable and flexible income stream.
Another major drawback is the lack of liquidity, as the invested amount remains largely locked into the plan.
The assurance of a guaranteed annuity does not adequately compensate for this lack of flexibility, particularly when the overall returns are relatively modest.
Consequently, the plan may not be suitable for retirees who prioritise better returns, liquidity and control over their retirement savings and it also has a high agent commission.
A more effective retirement strategy would involve systematically building a corpus through a diversified portfolio of equities, fixed-income instruments and other asset classes, based on one’s risk appetite and investment horizon.
Periodic portfolio reviews and rebalancing can help maintain the desired asset allocation as retirement goals and financial circumstances evolve.
Once the required retirement corpus is accumulated, allocating an appropriate portion to debt instruments for relatively stable income while retaining some equity exposure for long-term growth can help generate sustainable retirement income and manage the impact of inflation.
Ultimately, retirement planning should focus not just on securing a regular income but also on preserving purchasing power, maintaining liquidity and retaining control over your accumulated wealth.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
Consulting a Certified Financial Planner (CFP) can help you develop a personalised retirement strategy aligned with your financial goals, risk appetite and individual circumstances.
Leave a Comment