 Listen to this article
Can the ICICI Life Signature Secure Plan truly help you build long-term wealth while protecting your family’s financial future, or do its charges and conditions limit its potential?
Does the ICICI Life Signature Secure Plan offer the right balance between market-linked growth and life insurance protection, or are there better alternatives available?
Is the ICICI Life Signature Secure Plan a smart investment choice, or would separating life insurance and investments offer greater flexibility and value?
This article examines the plan’s key features, benefits, and drawbacks in detail. It also includes an illustration-based analysis to help you evaluate the plan’s returns and understand whether it is a suitable choice for your financial goals.
Table of Contents:
What is the ICICI Life Signature Secure?
What are the features of the ICICI Life Signature Secure?
Who is eligible for the ICICI Life Signature Secure?
What are the benefits of the ICICI Life Signature Secure?
What are the investment strategies and fund options in the ICICI Life Signature Secure?
What are the charges of the ICICI Life Signature Secure?
Free Look Period for the ICICI Life Signature Secure
Surrendering the ICICI Life Signature Secure
What are the advantages of the ICICI Life Signature Secure?
What are the disadvantages of the ICICI Life Signature Secure?
Research Methodology of ICICI Life Signature Secure
Benefit Illustration – IRR Analysis of ICICI Life Signature Secure
ICICI Life Signature Secure Vs. Other Investments
ICICI Life Signature Secure Vs. Pure-term + Equity Mutual Fund
Final Verdict on the ICICI Life Signature Secure
What is the ICICI Life Signature Secure?
ICICI Life Signature Secure is a Single Pay Non-Participating Linked Life Individual Savings Insurance Plan. It offers market-linked returns with a built-in guaranteed maturity benefit.
Customers can make a one-time investment and receive a guaranteed maturity benefit up to 140% of the investment amount after 5 years, along with tax-efficient returns and life cover benefits.
What are the features of the ICICI Life Signature Secure?
- Single-Premium Payment: Pay the premium just once and enjoy policy benefits throughout the entire policy term.
- Life Cover: Provides life insurance coverage for the full policy term, helping secure your family’s financial future in your absence.
- Guaranteed Benefits with Wealth-Growth Potential: Combines guaranteed benefits with an opportunity to grow your wealth.
- Guaranteed Returns: Offers a Guaranteed Maturity Benefit of 140%/100% of the single premium paid, subject to the policy’s terms and conditions.
- No Policy Administration or Premium Allocation Charges: The plan specifies zero charges under these two categories.
- Tax Benefits: Tax benefits may be available on premiums paid and benefits received, subject to prevailing tax laws and eligibility conditions.
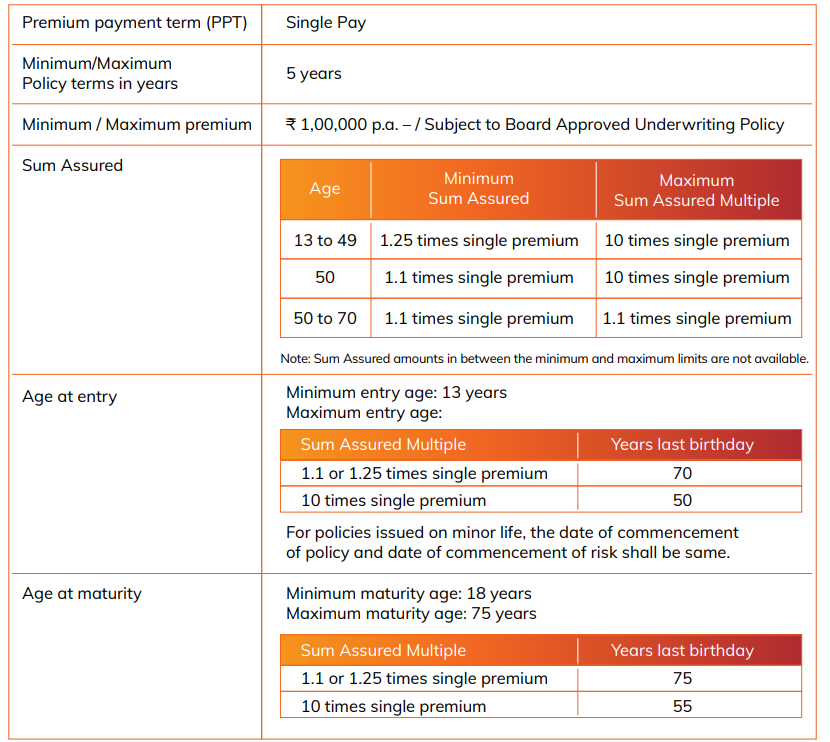
Who is eligible for the ICICI Life Signature Secure?
What are the benefits of the ICICI Life Signature Secure?
1. Maturity Benefit
Under this ICICI Life Signature Secure Plan policy, on survival of the life assured till the date of maturity, the Maturity Benefit payable shall be the highest of:
- Fund Value as on the Date of Maturity, or
- Guaranteed Maturity Benefit
Guaranteed Maturity Benefit is defined as a percentage of the single premium paid by you as follows:
| Sum Assured Multiple | % of Single Premium |
| 1.10x or 1.25x | 140% |
| 10x | 100% |
2. Death Benefit
In the event of death of the Life Assured during the ICICI Life Signature Secure Plan Policy Term, provided the monies are not in the Discontinued Policy fund, the Company shall pay the Death Benefit to the Claimant.
The Death Benefit payable shall be the highest of:
- Sum Assured,
- Fund Value as available on the date of intimation of death or the Date of Maturity, whichever is earlier; and
- Minimum Death Benefit
Minimum Death Benefit will be 105% of Total Premiums Paid.
What are the investment strategies and fund options in the ICICI Life Signature Secure?
The policy monies will be allowed to be invested only in the Secure Income Fund.
| Fund Name | Asset Allocation | Risk Profile | ||
| Equity and Equity-related Securities | Debt | Money market and cash | ||
| Secure Income Fund | 0 | 80-100% | 0-20% | Low |
What are the charges of the ICICI Life Signature Secure?
A. Premium Allocation Charge
Nil
B. Fund Management Charge (FMC)
Fund Management Charge will be 0.75% of the Fund Value
If the monies are in the Discontinued Policy Fund, a Fund Management Charge of 0.50% p.a. will apply.
C. Policy Administration Charge
Nil
D. Mortality Charges
Mortality charge will be levied every month by redemption of units and shall be calculated based on the Sum at Risk during ICICI Life Signature Secure Plan Policy Term.
E. Discontinuance charge
It depends on the year of discontinuance and the annualised premium amount. There is no discontinuance charge from the 5th policy year.
Inference from charges: The plan applies these charges before investing your premium, including Fund Management and Mortality Charges, which persist throughout the policy term. In contrast, other market-linked products typically have lower charges and offer more transparency in their investment processes. These higher charges in ULIPs can significantly affect your returns over time.
Free Look Period for the ICICI Life Signature Secure
On receipt of the Policy Document, whether received electronically or otherwise, you have an option to review the policy terms and conditions.
If you are not satisfied or have any disagreement with the terms and conditions of the ICICI Life Signature Secure Plan Policy or otherwise and have not made any claim, the Policy Document needs to be returned to the Company with reasons for cancellation within 30 days from the date of receipt of the Policy Document.
Surrendering the ICICI Life Signature Secure
Surrender during the Lock-in period: the Fund Value after deduction of applicable Discontinuance Charge shall be credited to the Discontinued Policy Fund and risk cover and rider cover, if any, shall cease. The fund management charges of the discontinued policy fund will be applicable during this period, and no other charges will be applied. You or the Claimant, as the case may be, will be entitled to receive the Discontinued Policy Fund Value on the earlier of death of the Life Assured or the expiry of the lock-in period. Currently, the lock-in period is five years from policy inception.
Surrender after completion of Lock-in period: The policy matures at the end of the lock-in period and hence, surrender of the policy after the lock-in period is not applicable.
What are the advantages of the ICICI Life Signature Secure?
- Flexible Maturity Payout: You can choose to receive the maturity benefit in structured payouts over a period of up to five years after the policy matures.
- One-Time Investment: A hassle-free, single-premium payment eliminates the need for recurring premium payments throughout the policy term.
What are the disadvantages of the ICICI Life Signature Secure?
- Limited Investment Choice: The plan offers only one fund, leaving policyholders with no alternative funds to choose from.
- No Loan Facility: Policyholders cannot avail of a loan against the policy to meet financial emergencies.
- Restricted Liquidity: Access to the invested funds is limited during the policy term, reducing financial flexibility.
- Inadequate Life Cover: The sum assured may be insufficient to meet a family’s essential financial needs in the policyholder’s absence.
- Limited Policy Flexibility: The plan requires a single premium payment and has a fixed five-year policy term, with no flexibility to modify the policy structure to suit individual needs.
- No Risk-Based Investment Options: The plan does not offer different investment strategies to match an individual’s risk appetite or financial objectives.
Research Methodology of ICICI Life Signature Secure
A single-premium investment may offer convenience, but its suitability ultimately depends on the returns it generates.
In this section, we analyse the Internal Rate of Return (IRR) of the ICICI Pru Signature Secure Plan to evaluate its investment efficiency and compare it with alternative market-linked investment options.
Benefit Illustration – IRR Analysis of ICICI Life Signature Secure
Consider a 45-year-old male investing a single premium of ₹10,00,000 in the ICICI Pru Signature Secure Plan for a policy term of five years.
The sum assured is ₹12.5 lakh, equivalent to 1.25 times the single premium.
| Male | 45 years |
| Sum Assured | ₹ 12,50,000 |
| Policy Term | 5 years |
| Premium Paying Term | Single pay |
| Annualised Premium | ₹ 10,00,000 |
At maturity, the policyholder receives the fund value, which depends on the investment performance.
The illustrated return scenarios of 4% and 8% are purely indicative and are neither guaranteed nor upper or lower limits on potential returns.
| At 4% p.a. | At 8% p.a. | ||||
| Age | Year | Annualised premium / Maturity benefit | Death benefit | Annualised premium / Maturity benefit | Death benefit |
| 45 | 1 | -10,00,000 | 12,50,000 | -10,00,000 | 12,50,000 |
| 46 | 2 | 0 | 12,50,000 | 0 | 12,50,000 |
| 47 | 3 | 0 | 12,50,000 | 0 | 12,50,000 |
| 48 | 4 | 0 | 12,50,000 | 0 | 12,50,000 |
| 49 | 5 | 0 | 12,50,000 | 0 | 12,50,000 |
| 50 | 11,70,000 | 14,17,151 | |||
| IRR | 3.19% | 7.22% | |||
At a 4% assumed return: The maturity fund value is ₹11.70 lakh, translating into an IRR of 3.19% as per the ICICI Life Signature Secure Plan maturity calculator.
Such a modest return offers limited wealth creation potential and may fail to preserve the purchasing power of the investment after accounting for inflation.
At an 8% assumed return: The maturity fund value increases to ₹14.17 lakh, resulting in an IRR of 7.22% as per the ICICI Life Signature Secure Plan maturity calculator.
Although the outcome is better, the return may still be less attractive than that of alternative investments, depending on their performance, risk, costs and taxation.
The IRR analysis highlights the plan’s limited wealth-creation potential under the illustrated scenarios. Over a five-year period, the returns may not generate meaningful inflation-adjusted growth, particularly for investors seeking to build wealth efficiently.
Those considering a lump-sum investment should evaluate alternative instruments that offer a suitable balance of return potential, risk, liquidity and flexibility, in line with their financial goals.
ICICI Life Signature Secure Vs. Other Investments
The IRR analysis indicates that the returns offered by the plan may not adequately compensate investors for the underlying investment risk.
To assess its effectiveness more practically, let us compare the ICICI Pru Signature Secure Plan with an alternative strategy using the same assumptions as those in the benefit illustration.
ICICI Life Signature Secure Vs. Pure-term + Equity Mutual Fund
A pure-term life insurance policy providing life cover of ₹12.5 lakh for five years can be purchased with a single premium of approximately ₹31,800. This leaves ₹9.68 lakh available for investment.
Depending on the investor’s risk appetite and financial objectives, this surplus could be allocated to suitable debt or equity instruments.
For this comparison, we consider an equity mutual fund investment.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 12,50,000 |
| Policy Term | 5 years |
| Premium Paying Term | Single pay |
| Annualised Premium | ₹ 31,800 |
| Investment | ₹ 9,68,200 |
| Term insurance + Equity Mutual Fund | |||
| Age | Year | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 45 | 1 | -10,00,000 | 12,50,000 |
| 46 | 2 | 0 | 12,50,000 |
| 47 | 3 | 0 | 12,50,000 |
| 48 | 4 | 0 | 12,50,000 |
| 49 | 5 | 0 | 12,50,000 |
| 50 | 16,29,662 | ||
| IRR | 10.26% | ||
Under this alternative strategy, the investment grows to a pre-tax maturity value of ₹17.06 lakh. After accounting for capital gains tax, the post-tax value stands at ₹16.29 lakh.
The combined strategy of term insurance and equity mutual fund investment delivers an IRR of 10.26%, based on the assumed investment returns and applicable tax treatment.
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 5 years | 17,06,299 |
| Purchase price | 9,68,200 |
| Long-Term Capital Gains | 7,38,099 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 6,13,099 |
| Tax paid on LTCG | 76,637 |
| Maturity value after tax | 16,29,662 |
This comparison highlights the potential benefits of separating insurance and investment.
While the ICICI Pru Signature Secure Plan offers a bundled solution with limited investment flexibility, combining pure-term insurance with an equity mutual fund provides greater control over investment choices and the potential for higher returns.
Final Verdict on the ICICI Life Signature Secure
The ICICI Pru Signature Secure Plan may seem like a convenient option for investors looking to invest surplus funds through a single premium.
However, despite being positioned as a market-linked investment product, its high charges and inadequate life cover limit its overall appeal.
Furthermore, the illustrated returns raise concerns about its effectiveness as a wealth-creation instrument.
The plan’s fixed five-year policy term and single-fund investment option significantly restrict flexibility. More importantly, it may not adequately address long-term family protection needs or broader financial goals.
With limited investment choices and modest illustrated returns, the plan may not be an efficient vehicle for wealth creation and it also has a high agent commission.
For life protection, a pure-term insurance policy remains a more cost-effective and flexible solution, allowing individuals to secure adequate coverage based on their family’s financial needs.
For wealth creation, investors should consider building a diversified portfolio across suitable asset classes, aligned with their risk appetite, investment horizon, and financial objectives, rather than relying on insurance-linked investment products.
Ultimately, separating insurance from investment can provide greater flexibility and transparency in financial planning.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
Choosing appropriate investment avenues, preferably with the guidance of a qualified financial advisor, can help you work towards your long-term financial goals with greater clarity and discipline.
Leave a Comment