 Listen to this article
Can the LIC New Bima Platinum Plan truly provide long-term financial security, or are its benefits less attractive than they initially appear?
Does the LIC New Bima Platinum Plan offer the right balance between life insurance protection and financial benefits, or are there better alternatives available?
Is the LIC New Bima Platinum Plan a smart financial choice, or does its premium positioning overshadow its actual benefits?
Let us examine the features, advantages, and drawbacks of LIC New Bima Platinum to assess its value.
This review aims to help you evaluate whether your savings are being utilised effectively and whether better financial strategies could help you achieve your goals.
Table of Contents:
What is the LIC New Bima Platinum?
What are the features of the LIC New Bima Platinum?
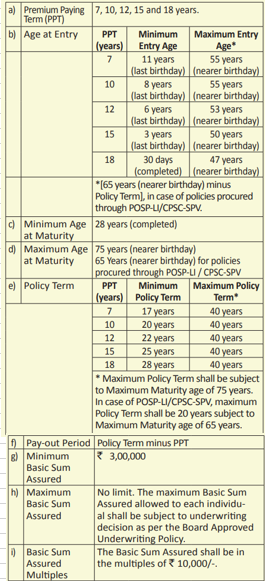
Who is eligible for LIC New Bima Platinum?
What are the benefits of LIC New Bima Platinum?
Grace Period, Discontinuance and Revival of LIC New Bima Platinum
Free Look Period for LIC New Bima Platinum
Surrendering LIC New Bima Platinum
What are the advantages of LIC New Bima Platinum?
What are the disadvantages of LIC New Bima Platinum?
Research Methodology of LIC New Bima Platinum
Benefit Illustration – IRR Analysis of LIC New Bima Platinum
LIC New Bima Platinum Vs. Other Investments
LIC New Bima Platinum Vs. Pure-term + Equity Mutual Fund
Final Verdict on LIC New Bima Platinum
What is the LIC New Bima Platinum?
LIC’s New Bima Platinum is a Non-Par, Non-Linked, Life, Individual, Savings Plan. It offers an attractive combination of savings and protection.
This is a Limited Premium payment plan with accrual of Guaranteed Additions during the Premium Paying Term (PPT).
What are the features of the LIC New Bima Platinum?
- Protection and Savings: Provides life insurance coverage along with savings benefits.
- Guaranteed Additions: Offers guaranteed additions of ₹70 per ₹1,000 of total annualised premiums for premiums paid during the Premium Paying Term (PPT).
- Regular Income Benefit: Pays 10% of the Basic Sum Assured upon survival during the payout period. The payout period is the policy term minus the Premium Paying Term.
- Booster Income Benefit: Pays 70% of the Basic Sum Assured upon survival at the end of the (PPT + 5)th policy year.
- Deferred Income Option: Allows policyholders to defer the Regular Income Benefit and/or Booster Income Benefit, subject to the plan’s conditions.
- Flexible Premium Payment Term: Offers a choice of premium payment terms of 7, 10, 12, 15, or 18 years.
- Instalment Payout Option: Allows the maturity benefit or death benefit to be received in instalments instead of as a lump sum, subject to the applicable terms and conditions.
Who is eligible for LIC New Bima Platinum?
What are the benefits of LIC New Bima Platinum?
1. Death Benefit
Death benefit payable on death of the life assured during the LIC New Bima Platinum Plan policy term after the date of commencement of risk but before the stipulated date of maturity, provided the policy is in-force, shall be “Sum Assured on Death” along with accrued Guaranteed Additions for in-force policy; Where, “Sum Assured on Death” is defined as the higher of
- 11 times the Annualised Premium or
- Basic Sum Assured.
This Death Benefit shall not be less than 105% of the “Total Premiums Paid” up to the date of death
2. Income Benefit
The Income Benefit, comprising the Regular Income Benefit and the Booster Income Benefit, shall be payable upon the survival of the Life Assured to the specified durations during the Pay-out Period as mentioned below:
Regular Income Benefit
On survival of the Life Assured to the end of the Premium Paying Term, provided the LIC New Bima Platinum Plan policy is in force, Regular Income Benefit equal to 10% of Basic Sum Assured shall be payable.
The first Regular Income Benefit shall be payable at the end of the Premium Paying Term, and thereafter on completion of each subsequent Policy Year till the Life Assured survives or till the policy anniversary prior to the date of maturity, whichever is earlier.
Booster Income Benefit
On survival of the Life Assured on the specified policy anniversary, provided the LIC New Bima Platinum Plan policy is in-force, a Booster Income Benefit equal to 70% of Basic Sum Assured shall be payable.
| Premium Paying Term | Policy anniversary on which the Booster Benefit is payable |
| 7 years | 12th policy anniversary |
| 10 years | 15th policy anniversary |
| 12 years | 17th policy anniversary |
| 15 years | 20th policy anniversary |
| 18 years | 23rd policy anniversary |
3. Maturity Benefit
On the Life Assured surviving the stipulated Date of Maturity, provided the policy is in-force, “Sum Assured on Maturity” along with accrued Guaranteed Additions for an in-force policy shall be payable, where “Sum Assured on Maturity” is equal to the Basic Sum Assured.
4. Guaranteed Additions
Under an in-force policy (in which all the due premiums have been paid), the Guaranteed Additions shall accrue at the end of each policy year during the Premium Paying Term (PPT).
The Rate of Guaranteed Additions for an in-force policy shall be Rs. 70 per thousand Total Annualised Premium in respect of Premiums Paid.
Grace Period, Discontinuance and Revival of LIC New Bima Platinum
Grace Period
A grace period of 30 days shall be allowed for payment of yearly, half-yearly or quarterly premiums and 15 days for monthly premiums from the date of First Unpaid Premium.
Discontinuance
Paid-up Value: If less than one full year’s premium(s) have been paid in respect of this policy and any subsequent premium is not duly paid, all the benefits under this policy shall cease after the expiry of the grace period from the date of First Unpaid Premium, and nothing shall be payable.
If, after at least one full year’s premium(s) has been paid and any subsequent premiums are not duly paid, on completion of first policy year, this policy shall not be wholly void, but shall subsist as a paid-up policy till the end of the LIC New Bima Platinum Plan policy term.
Revival
If the premiums are not paid within the grace period, then the policy will lapse. A lapsed policy can be revived within a period of 5 consecutive complete years from the date of First Unpaid Premium but before the date of maturity, as the case may be.
Free Look Period for LIC New Bima Platinum
If the LIC New Bima Platinum Plan Policyholder is not satisfied with the “Terms and Conditions” of the policy, the policy may be returned to the Corporation within 30 days from the date of receipt of electronic or physical mode of the Policy Document, whichever is earlier, stating the reason for objections.
Surrendering LIC New Bima Platinum
The policy can be surrendered by the LIC New Bima Platinum Plan policyholder after completion of the first policy year provided one full year’s premium(s) has been paid.
On surrender of an in-force or a paid-up policy, the Corporation shall pay the Surrender Value, whichever is higher of the
Guaranteed Surrender Value and surrender value of any accrued Guaranteed Additions; or
Special Surrender Value.
What are the advantages of LIC New Bima Platinum?
- Rider Benefits: Offers the option to enhance insurance coverage by choosing additional rider benefits at an extra premium, subject to the applicable terms and conditions.
- Settlement Option: Allows the policyholder to receive the maturity or death benefit in instalments over a selected period of 5, 10, or 15 years instead of as a lump sum.
- High Sum Assured Incentive: Provides incentives for opting for a higher Basic Sum Assured, as specified under the plan.
- Loan Facility: Offers a loan facility against the policy to help meet financial needs, subject to the applicable terms and conditions.
What are the disadvantages of LIC New Bima Platinum?
- Inadequate Life Cover: The sum assured may be insufficient to meet long-term financial needs and provide adequate financial security for the family.
- Reduced Compounding Benefits: The periodic survival benefits can interrupt the compounding of the accumulated funds, potentially limiting long-term wealth creation.
- Relatively Low Returns: The overall returns may be lower than those achievable through suitable alternative investment options, depending on the investment horizon and risk profile.
Research Methodology of LIC New Bima Platinum
The LIC New Bima Platinum Plan offers periodic income benefits after the completion of the Premium Paying Term, along with a maturity benefit at the end of the policy term.
To evaluate whether these benefits provide reasonable value, let us examine the cash flows using an illustration from the policy brochure.
Benefit Illustration – IRR Analysis of LIC New Bima Platinum
Consider a 35-year-old male opting for a Basic Sum Assured of ₹16.13 lakh, with a Premium Paying Term of 12 years and a Policy Term of 25 years.
The annual premium is ₹1.46 lakh.
| Male | 35 years |
| Sum Assured | ₹ 16,13,150 |
| Policy Term | 25 years |
| Premium Paying Term | 12 years |
| Annualised Premium | ₹ 1,46,650 |
After completing the premium payments, the policy provides an annual Regular Income Benefit of ₹1 lakh and a Booster Income Benefit of ₹7 lakh, as specified in the illustration.
At maturity, the policy pays ₹19.15 lakh.
However, the estimated Internal Rate of Return (IRR) for these cash flows is only 5.41% as per the LIC New Bima Platinum Plan maturity calculator, which may be less attractive than the returns available from alternative debt instruments.
| Age | Year | Annualised premium / Maturity benefit | Death benefit |
| 35 | 1 | -1,46,650 | 16,24,882 |
| 36 | 2 | -1,46,650 | 16,48,346 |
| 37 | 3 | -1,46,650 | 16,83,542 |
| 38 | 4 | -1,46,650 | 17,30,470 |
| 39 | 5 | -1,46,650 | 17,89,130 |
| 40 | 6 | -1,46,650 | 18,59,522 |
| 41 | 7 | -1,46,650 | 19,41,646 |
| 42 | 8 | -1,46,650 | 20,35,502 |
| 43 | 9 | -1,46,650 | 21,41,090 |
| 44 | 10 | -1,46,650 | 22,58,410 |
| 45 | 11 | -1,46,650 | 23,87,462 |
| 46 | 12 | -1,46,650 | 25,28,246 |
| 47 | 13 | 1,00,000 | 25,28,246 |
| 48 | 14 | 1,00,000 | 25,28,246 |
| 49 | 15 | 1,00,000 | 25,28,246 |
| 50 | 16 | 1,00,000 | 25,28,246 |
| 51 | 17 | 1,00,000 | 25,28,246 |
| 52 | 18 | 8,00,000 | 25,28,246 |
| 53 | 19 | 1,00,000 | 25,28,246 |
| 54 | 20 | 1,00,000 | 25,28,246 |
| 55 | 21 | 1,00,000 | 25,28,246 |
| 56 | 22 | 1,00,000 | 25,28,246 |
| 57 | 23 | 1,00,000 | 25,28,246 |
| 58 | 24 | 1,00,000 | 25,28,246 |
| 59 | 25 | 1,00,000 | 25,28,246 |
| 60 | 20,15,096 | ||
| IRR | 5.41% |
Furthermore, the life cover and periodic income may be inadequate to meet the policyholder’s financial needs.
Given the long policy duration, inflation can significantly erode the purchasing power of the fixed income benefits and maturity proceeds.
Overall, the plan may not be an efficient choice for individuals seeking adequate life insurance protection and long-term wealth creation through a well-balanced financial portfolio.
LIC New Bima Platinum Vs. Other Investments
Analysing cash flows and comparing returns with alternative investment options is essential for making informed financial decisions.
To ensure a fair comparison, we follow the same evaluation methodology used in our earlier analyses.
The LIC New Bima Platinum Plan combines life insurance coverage with periodic income benefits. To assess its effectiveness, let us separate the insurance and investment components and evaluate them independently.
LIC New Bima Platinum Vs. Pure-term + Equity Mutual Fund
A pure-term life insurance policy with a sum assured of ₹25 lakh costs an annual premium of ₹18,100, with a 10-year Premium Paying Term and a 25-year Policy Term.
The remaining ₹1.28 lakh per year can be invested separately, based on the investor’s risk appetite.
The accumulated corpus can then be used to fund periodic withdrawals, replicating the income benefits offered by LIC New Bima Platinum.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 25,00,000 |
| Policy Term | 25 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 18,100 |
| Investment | ₹ 1,28,550 |
For this illustration, we assume that the remaining ₹1.28 lakh per year is invested in an equity mutual fund. After 12 years, the investment grows to ₹35.17 lakh.
After accounting for capital gains tax, the post-tax corpus is ₹32.90 lakh, which is subsequently invested in a fixed-income instrument yielding 7% annually.
| Age | Year | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 35 | 1 | -1,46,650 | 16,24,882 |
| 36 | 2 | -1,46,650 | 16,48,346 |
| 37 | 3 | -1,46,650 | 16,83,542 |
| 38 | 4 | -1,46,650 | 17,30,470 |
| 39 | 5 | -1,46,650 | 17,89,130 |
| 40 | 6 | -1,46,650 | 18,59,522 |
| 41 | 7 | -1,46,650 | 19,41,646 |
| 42 | 8 | -1,46,650 | 20,35,502 |
| 43 | 9 | -1,46,650 | 21,41,090 |
| 44 | 10 | -1,46,650 | 22,58,410 |
| 45 | 11 | -1,46,650 | 23,87,462 |
| 46 | 12 | -1,46,650 | 25,28,246 |
| 47 | 13 | 1,00,000 | 25,28,246 |
| 48 | 14 | 1,00,000 | 25,28,246 |
| 49 | 15 | 1,00,000 | 25,28,246 |
| 50 | 16 | 1,00,000 | 25,28,246 |
| 51 | 17 | 1,00,000 | 25,28,246 |
| 52 | 18 | 8,00,000 | 25,28,246 |
| 53 | 19 | 1,00,000 | 25,28,246 |
| 54 | 20 | 1,00,000 | 25,28,246 |
| 55 | 21 | 1,00,000 | 25,28,246 |
| 56 | 22 | 1,00,000 | 25,28,246 |
| 57 | 23 | 1,00,000 | 25,28,246 |
| 58 | 24 | 1,00,000 | 25,28,246 |
| 59 | 25 | 1,00,000 | 25,28,246 |
| 60 | 45,72,653 | ||
| IRR | 8.01% |
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 12 years | 35,17,569 |
| Purchase price | 15,78,800 |
| Long-Term Capital Gains | 19,38,769 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 18,13,769 |
| Tax paid on LTCG | 2,26,721 |
| Maturity value after tax | 32,90,848 |
To replicate the cash flows of LIC New Bima Platinum, ₹1 lakh is withdrawn annually to match the plan’s regular income benefit.
At the end of the 25-year period, the remaining corpus is withdrawn as a lump sum, comparable to the plan’s maturity benefit.
Under these assumptions, the alternative strategy delivers an estimated IRR of 8.01%, significantly higher than the 5.41% offered by LIC New Bima Platinum.
Furthermore, if the annual withdrawals are deferred or avoided, the corpus has the potential to grow further through compounding.
This approach offers the additional advantages of greater liquidity, flexibility in withdrawals, and independent control over investments.
Separating insurance from investments may therefore provide better value than combining both within the rigid structure of LIC New Bima Platinum.
Final Verdict on LIC New Bima Platinum
The LIC New Bima Platinum Plan allows policyholders to pay premiums for a limited period and receive a fixed income thereafter. An additional Booster Income Benefit is also payable once during the payout period.
While the promise of guaranteed income may appeal to those seeking predictable cash flows, our analysis indicates that the plan’s returns may not justify the investment.
The plan’s limited liquidity and relatively low returns further weaken its appeal as a wealth-building option.
Consequently, it may not be the most suitable choice for investors seeking to balance income generation, capital growth, and financial flexibility and it also has a high agent commission.
A more effective approach to meeting regular income needs is to build an adequate corpus through investments aligned with your risk tolerance and financial goals.
This approach offers greater flexibility over withdrawals and investment choices, while a separate pure-term life insurance policy can provide adequate financial protection for your family. A well-diversified investment portfolio can then focus on long-term wealth creation.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
Since a systematic withdrawal from an insurance policy may not suit every investor, consulting a Certified Financial Planner (CFP) can help you identify the right combination of insurance and investments.
A personalised, goal-based financial plan can help you balance regular income, liquidity, risk management, and long-term financial security.
Leave a Comment